• KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10830
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
18 October 2026

Viewing results 1 - 6 of 42

Russian Lawmakers Propose School Fees for Central Asian Migrants’ Children

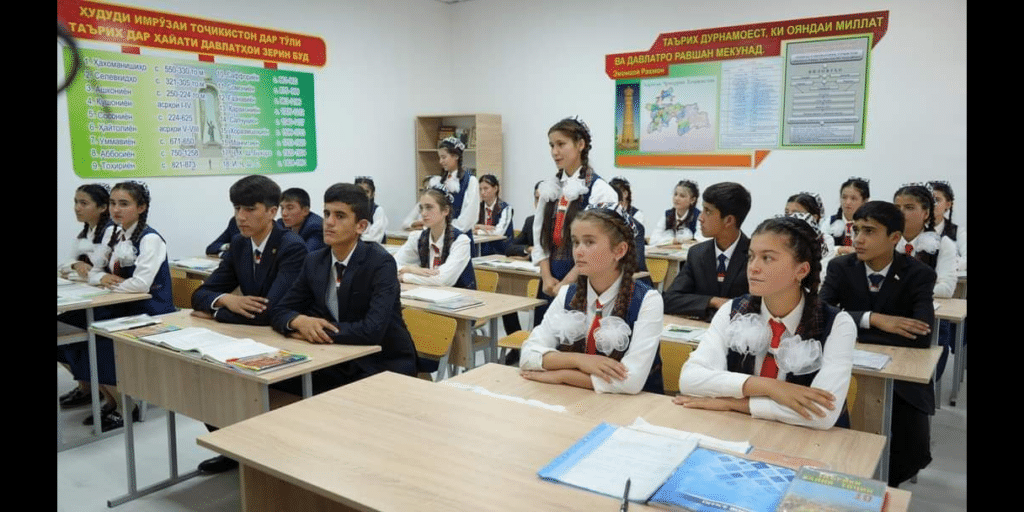
Russia relies on millions of workers from Central Asia, but lawmakers want to charge some of their children, typically aged 15–17, for the final two years of public schooling. The move comes after tougher enrollment rules that have left thousands of migrant children struggling to attend Russian schools. The proposal, submitted to the government by deputies from the Liberal Democratic Party of Russia (LDPR) on October 14, would require foreign citizens and stateless people to pay for education in grades 10 and 11. LDPR leader Leonid Slutsky argued that migrant families should bear the costs of educating their children in Russian upper-secondary schools, allowing public funds to be redirected toward Russian students. The party claimed that more than 130,000 foreign children attend grades 10–11, costing the state over 37 billion rubles (about $440 million) annually. However, these figures contradict data from Russia's Ministry of Education analyzed by the data project Tochno, which found approximately 130,000 foreign pupils and another 3,000 stateless pupils enrolled across all school grades in 2025–26, with only 4% of foreign pupils attending grades 10–11. That would put the number of foreign pupils in the final two grades at roughly 5,200, casting doubt on the LDPR's estimated savings. Growing Pressure on Migrant Families The proposed fees follow a series of Russian restrictions that have already made it more difficult for Central Asian families to educate their children in Russia. Since April 2025, foreign children seeking admission to Russian schools have been required to demonstrate sufficient Russian-language proficiency and provide documentation establishing their legal residence. Enrollment among children from Uzbekistan, Tajikistan, and Kyrgyzstan fell by 27% in the 2025–26 school year, from approximately 122,000 to 89,000. In January 2026, Tajikistan's Minister of Education and Science Rahim Saidzoda reported that approximately 9,000 Tajik children had returned from Russia during 2025 following difficulties continuing their education there. Kyrgyzstan's membership in the Eurasian Economic Union (EAEU) raises a separate legal question. The EAEU treaty recognizes the right of migrant workers' children to receive education in the country where their parents work, subject to that country's legislation. However, it does not explicitly guarantee free tuition, leaving unclear whether children of workers from EAEU member states would qualify for exemptions. For migrant families, the immediate consequences would depend on the eventual tuition charges and exemptions. Some parents might choose vocational education for their children after grade nine, while others could leave them with relatives in their home countries rather than incur additional schooling expenses in Russia. Additional education costs could discourage migrant workers from bringing their families to Russia, even as the country continues to rely on Central Asian labor. Central Asia's Dependence on Remittances The proposed fees would affect families whose earnings are often vital to their home countries' economies. Tajikistan is the most dependent on remittances relative to the size of its economy, Kyrgyzstan relies particularly heavily on earnings from Russia, and Uzbekistan receives the largest remittance inflows in absolute terms. According to The Times of Central Asia's Central Asia Balance...
Kyrgyzstan Expands Foreign Worker Quotas While Citizens Work Abroad

Kyrgyzstan plans to allow up to 120,000 foreign nationals to work in the country in 2027, even as more than 700,000 of its own citizens have worked abroad this year. Although official estimates are lower than four years ago, the country remains heavily dependent on money sent home by migrant workers, particularly those in Russia. According to the National Bank of the Kyrgyz Republic, Kyrgyzstan received approximately $3.5 billion in transfers from abroad in 2025, more than 90% of which came from Russia. The Ministry of Labor, Social Security, and Migration reported that 736,600 citizens had worked abroad so far in 2026, compared with 798,400 in 2025. The largest group, more than 472,000 people, was reported to be in Russia in March. Approximately 70,000 were working in Kazakhstan, 60,000 in the United States, 35,000 in Turkey, and 20,000 in Germany. In 2022, the authorities estimated that 1.118 million Kyrgyz citizens were working abroad, including more than one million in Russia. However, the figures do not establish exactly how many people have returned home and how many have moved to other countries for work. Russia has tightened its migration requirements and stepped up enforcement of residency regulations. In a report covering the second half of 2025, the International Organization for Migration (IOM) found that 94% of emigrants surveyed had left to find employment or better economic opportunities. Foreign Minister Jeenbek Kulubaev discussed these changes in labor migration during a parliamentary committee meeting on October 13. According to Kulubaev, more Kyrgyz citizens are choosing Turkey and the U.S. for employment, while demand for workers from Kyrgyzstan remains strong in South Korea and Japan. He said representatives from some European countries had offered to accept workers from Kyrgyzstan on the condition that the country accommodate migrants from Afghanistan and African nations. Kulubaev did not disclose which countries had made the offer, saying only that Bishkek rejected the proposal. There has been no public confirmation of the arrangement from the European participants in the negotiations. Within Kyrgyzstan, the unemployment rate fell from 5.8% in 2020 to 3.2% in 2025. The decline coincided with growth in construction, trade, and services, although employment figures alone do not show how much wages have increased or how many former migrants have found jobs at home. During a recent visit to the Batken region, President Sadyr Japarov again urged citizens working abroad to return home. The initial quota for foreign nationals arriving to work in Kyrgyzstan for 2025 was 25,000 people. The limit was raised to 100,000 for 2026. Expanding the quota allows businesses to recruit more employees from abroad, particularly for construction, manufacturing, and other industries where employers face staffing needs. According to the Ministry of Labor, by December 2025, approximately 18,900 Chinese, 11,700 Bangladeshis, and 8,300 Pakistanis had received work permits. An IOM study conducted in the first half of 2025 found a substantial presence of workers from Uzbekistan, approximately 10,800 people. The largest numbers of foreign workers covered by the survey were in the Jalal-Abad region,...

Central Asia Economic Growth Expected to Slow in 2027

After several years of rapid expansion, Central Asian economies are expected to lose some momentum. The European Bank for Reconstruction and Development (EBRD) forecasts that regional economic growth will slow from 5.8% in 2026 to 5.3% in 2027. However, growth in manufacturing and construction will not necessarily translate into comparable increases in household incomes. The forecast appears in the EBRD’s September report. The bank’s Central Asia figures also include Mongolia, so the regional growth rate should not be interpreted as an average for the five Central Asian countries alone. The Eurasian Fund for Stabilization and Development (EFSD) has published its own projections for Kazakhstan, Kyrgyzstan, and Tajikistan. They differ somewhat from the EBRD’s forecasts but also anticipate continued economic growth. Kyrgyzstan and Tajikistan Maintain Strong Growth The EBRD expects the economies of Kyrgyzstan and Tajikistan to grow by 7% in 2027, the highest rates projected for the five countries in the region. Kyrgyzstan has experienced a construction boom in recent years, driven by investment in roads, housing, and energy infrastructure. The service sector is also expanding. The country’s economy grew by 11.9% in the first half of 2026. However, rapid growth has been accompanied by rising food and fuel prices. The country's performance is closely tied to economic conditions in Russia, where a significant number of Kyrgyz migrant workers are employed and from which Kyrgyzstan imports the vast majority of its fuel. Changes in the Russian labor market can affect remittances and household spending in Kyrgyzstan. In Tajikistan, growth is supported by investment and exports, particularly precious metals and mineral resources. The economy expanded by 8.2% in the first half of 2026. Tajikistan also relies heavily on imported goods and equipment, with spending on imports exceeding export earnings. Remittances from migrant workers in Russia are an even more important source of household income for Tajiks than for their Kyrgyz neighbors, while rising fuel costs are putting additional pressure on family budgets. Kazakhstan Remains Dependent on Oil Exports For Central Asia’s largest economy, the EBRD forecasts growth of 4.5% in 2027, while the Eurasian Fund for Stabilization and Development expects 5%. In 2026, Kazakhstan’s economy has been constrained by disruptions to oil production and exports. Problems arose at the Tengiz oil field and along the Caspian Pipeline Consortium (CPC) export route, through which a significant share of Kazakhstan’s oil reaches global markets via Russia. Meanwhile, Kazakhstan’s factories increased production. But even growth in industries outside the oil sector has yet to eliminate the country’s dependence on commodity exports. For international buyers, the reliability of supply routes is also important. Disruptions to the CPC can restrict Kazakhstan’s oil exports regardless of demand or global prices. The Times of Central Asia recently examined the challenges facing Kazakhstan’s oil logistics. Inflation is another concern. According to the EFSD, prices in Kazakhstan are expected to rise by approximately 9.5% by the end of 2026. This means economic expansion will not necessarily be accompanied by a noticeable improvement in household purchasing power. Uzbekistan’s Growth Driven by...

Uzbekistan Proposes One-Stop Center for Migrant Workers Heading to Russia

Uzbekistan has proposed establishing a one-stop center where citizens planning to work in Russia could complete key migration procedures before departure. The initiative was discussed at a meeting between Uzbekistan Migration Agency Director Muhsinxo‘ja Abdurahmonov and Russian Ambassador to Uzbekistan Alexey Yerkhov. The Migration Agency also wants Russian-language examinations to be available in the regions so applicants do not have to travel to Tashkent. It said the necessary infrastructure has been prepared in four regions. Uzbekistan is proposing that citizens travel to Russia for specific vacancies. Prospective workers would know their employer and working conditions in advance. In 2025, Tashkent and Moscow considered conducting medical examinations and Russian-language tests at branches of Russian universities in Tashkent and Jizzakh. The latest initiative comes as work-related travel from Uzbekistan to Russia has declined. In January-June 2026, Uzbek citizens made more than 1.1 million entries into Russia declaring work as the purpose of their trip, down 13.2% from a year earlier. Across Uzbekistan, Tajikistan, and Kyrgyzstan, work-related entries fell by about 15%, from more than 2.3 million to 1.9 million. The figures count border crossings rather than individual workers, meaning the same person can be counted more than once. Despite fewer work-related entries into Russia, cross-border remittances to Uzbekistan reached $9.3 billion in the first half of 2026, up 13% year-on-year. The Central Bank attributed the increase to sustained demand for labor and relatively high wages in traditional destination countries for Uzbek migrant workers, as well as the strengthening of national currencies. The Central Bank also pointed to signs of diversification in the geography of labor migration. Transfers from the United Kingdom increased by 62% year-on-year, those from European Union countries by 27%, and those from the United States by 19%.

Kazakhstan Remains Far Less Remittance-Dependent Than Its Neighbors

Money transfers from abroad play very different roles in different economies. In some countries, funds sent by labor migrants are a key source of household income. In Kazakhstan, however, their impact remains minimal. That is the conclusion reached by analysts at Finprom.kz. According to the study, the volume of international money transfers through remittance systems in Kazakhstan continues to decline. In January-April 2026, around $376.3 million was sent abroad from Kazakhstan, compared with $388.8 million in the same period last year. Inflows from other countries also decreased, from $138.2 million to $128.8 million. Kazakhstan has traditionally sent significantly more money abroad than it receives. In the first four months of this year, outgoing transfers were almost three times higher than incoming transfers. This trend has persisted for many years and indicates that remittance inflows do not have a significant impact on the country’s economy. Russia remains the main destination for outgoing transfers. From January to April, around $162.2 million was sent there, compared with $135.7 million a year earlier. It was followed by Uzbekistan with $66.5 million and Turkey with $63.9 million. Among the countries from which Kazakhstan receives the largest amount of money, Russia also ranks first with $29 million. The U.S. follows with $21.6 million, and Turkey with $16.5 million. Another $13.7 million came from Uzbekistan. Analysts say the dynamics of transfers between Kazakhstan and Uzbekistan are particularly illustrative. In January-April this year, the volume of transfers from Kazakhstan to the neighboring country was almost five times higher than the reverse flow. This pattern has been observed for many years. For comparison, in the same period of 2015, around $23.1 million was sent from Kazakhstan to Uzbekistan, while only $4.9 million came in the opposite direction. In 2021, the figures stood at $114.5 million and $33.3 million, respectively. The money-transfer data covers remittance systems, while the World Bank’s GDP comparison uses the broader category of personal remittances received. Both measures point to the same conclusion: Kazakhstan is not structurally dependent on remittance inflows. Comparing the role of remittances in different economies reveals an even sharper contrast. According to World Bank data, remittance inflows worldwide averaged 0.8% of GDP in 2024. Tajikistan was the most remittance-dependent country in the World Bank’s 2024 data, with remittances accounting for 47.9% of GDP. High dependence was also seen in Kyrgyzstan at 26.6%, Nepal at 26.2%, and Honduras at 25.7%. Uzbekistan, where remittances accounted for 14.4% of GDP, ranked among the world’s 15 most remittance-dependent countries. Among former Soviet states, only Tajikistan and Kyrgyzstan recorded higher levels. Against this backdrop, Kazakhstan stands out as one of the least dependent countries. In 2024, incoming remittances accounted for just 0.1% of GDP. The same figure was recorded in Russia. Compared with Uzbekistan, Kazakhstan’s dependence on foreign remittance inflows is dozens of times lower. Long-term statistics also confirm this gap: over the past decade, Kazakhstan’s inbound remittances have consistently remained within the range of 0.1-0.3% of GDP, while in Uzbekistan, the figure rose from 8.4% in...

Russian Inflows Drive Kyrgyz Remittance Surge

Kyrgyzstan recorded a sharp increase in remittance inflows during the first five months of 2025, reaching USD 1.367 billion —a 16% rise compared to the same period in 2024, according to data from the National Bank of the Kyrgyz Republic (NBKR). The increase was particularly notable in April and May, traditionally high-transfer months ahead of the summer season. In May alone, remittances totaled USD 299 million, up from USD 253 million in May 2024. Russia remains the dominant source of remittances, accounting for 94% of total inflows between January and May. The NBKR reported USD 1.2 billion in transfers from Russia during this period, reflecting a year-on-year increase of USD 188 million. This growth comes despite a significant drop in the officially registered number of Kyrgyz labor migrants in Russia from 650,000 in previous years to around 350,000 in 2025. Unofficial estimates, however, suggest the actual figure may exceed one million. The higher remittance volume suggests increased per-capita transfers or improved earnings among Kyrgyz migrants. In 2023, remittances from Russia stood at USD 2.532 billion. Even as the migrant workforce declined sharply in 2024, total transfers from Russia rose by USD 34 million, indicating persistent reliance on income from abroad. Other countries contributed relatively little to Kyrgyzstan’s remittance inflows. Transfers from the United States edged up to USD 27.6 million in the first five months of 2025, an increase of USD 600,000 from the previous year. In contrast, remittances from South Korea and Turkey declined sharply. Transfers from South Korea fell from USD 28.2 million to just USD 1 million, while Turkey’s contribution dropped from USD 6.9 million to USD 4 million. Remittances continue to play a central role in Kyrgyzstan’s economy, historically making up more than 30 percent of GDP. Yet the country’s ongoing reliance on Russia for these financial inflows highlights its exposure to external risks such as geopolitical tensions, currency fluctuations, and changes in foreign labor market policies. Looking ahead, the NBKR expects the upward trend in remittances to persist through 2025. However, long-term sustainability may hinge on diversifying migration destinations and strengthening domestic employment opportunities.