• KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
14 November 2026

Viewing results 1 - 6 of 7

Opinion: A Deeper Understanding of Transshipment

The White House recently issued a report on the transshipment of goods. It focuses on allegations that some countries with lower tariffs seek to evade U.S. tariffs on China by exporting goods that are really produced in China and only slightly modified, if at all, before further export to the U.S. The report groups more than 40 countries in what it terms a “shadow transshipment network” into three different categories based on how much it estimates the risk of transshipment and the integration of the economy into supply chains involving China. The first tier, mostly advanced countries, are larger economies where transshipment can show up in otherwise “broadly legitimate” trade. The second tier are a few larger developing countries, which have close links with the Chinese economy. The third tier the report terms “small, opportunistic Chinese targets” with “specific weak-link advantages” that increase transshipment risk. To be clear, transshipment is a risk in some economies. There is also legitimate transshipment (for instance, through normal supply chains and logistics channels) and illegal transshipment (where an exporter files a false certification as to the origin, character, or value of goods). False certifications are punishable by civil and criminal penalties in the U.S. and in most other countries. The World Customs Organization also has international standards on transshipment. So there are reasons to be vigilant about the risk of illegal transshipment. But to see why the report also misses the mark, consider the example of a country increasingly important to the U.S. with a fast-growing economy. To top it off, the country borders China. It’s Kazakhstan. First, the report is wrong to call Kazakhstan “small.” It’s 49th in the world by GDP – quite an accomplishment for a country which was formerly part of the Soviet Union. Second, to term Kazakhstan an “opportunistic Chinese target” is simply not accurate. There is strong trade and investment between China and Kazakhstan, as one would expect from large neighboring countries. And Kazakhstan, particularly at its Khorgos border cooperation center, plays a vital role in the rapidly growing Middle Corridor of trade between China and Europe. But this is legitimate transshipment of goods, and it is deeply unfair to suggest that Kazakhstan may not be fulfilling its duties. Let’s also not forget why the Middle Corridor is growing: because the West sought another route for Chinese goods after the Russian invasion of Ukraine made shipment through Russia impractical or subject to sanctions. Kazakhstan is a regional and even global leader in digitalization of both tax and Customs systems. The “smart border” policy is a success in facilitating legal trade while maintaining vigilance and security: in the first half of 2026, about 60% of declarations of goods were automatic, and 80% of transit declarations were completed without the need for Customs control forms. Deepening digital exchange protocols with regional partners including China, Uzbekistan, and Azerbaijan will speed legal trade even further. Digitalization builds honest systems, free from corruption – and by definition lowering the risk of transshipment. Kazakhstan...
Uzbekistan–Türkiye Trade Agreement to Cover More Products

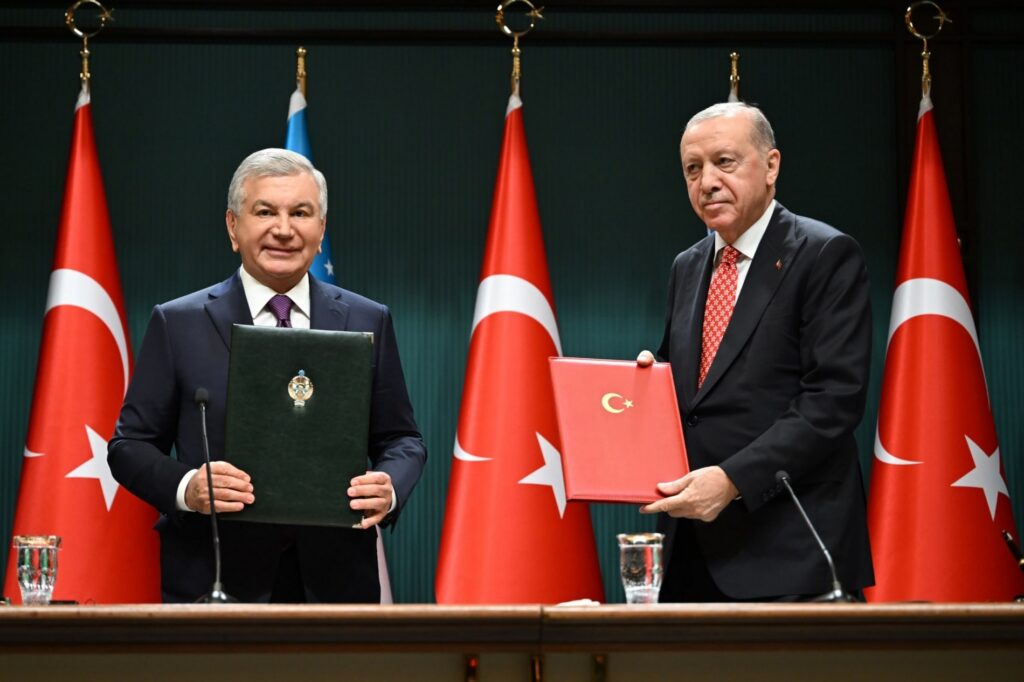
Uzbekistan and Türkiye have agreed to expand the list of goods eligible for preferential trade treatment and signed agreements on business support and social security. Five documents were signed in Ankara on October 29 following talks between Presidents Shavkat Mirziyoyev and Recep Tayyip Erdoğan. Turkish Trade Minister Ömer Bolat explained the expansion in an interview with Aziza Kurbonova, first deputy head of the Communications Department of Uzbekistan’s Presidential Administration. "In addition to the 12 products on each side already benefiting from preferential treatment, we mutually agreed to add another eight products each," Bolat said. The minister estimated annual bilateral trade at approximately $3.25 billion, with the two countries aiming to increase it to $5 billion in the near term and $10 billion in the medium term. Their presidents set the near-term target in January 2026. The new trade preferences will take effect once both countries complete their approval procedures. The other agreements signed in Ankara include one establishing a High-Level Business Support Council. Two cover social security and the implementation of those arrangements, while the fifth amends a 2022 agreement on exchanging customs information about goods and vehicles before they cross borders. According to Bolat, a Turkish business delegation led by Vice President Cevdet Yılmaz is scheduled to visit Uzbekistan on November 18 to discuss joint projects. A meeting of the Joint Intergovernmental Commission on economic cooperation is expected to take place in Ankara in December. A Turkish Trade Ministry delegation is also expected to visit Tashkent to share its experience with free trade zones. Under the existing preferential trade agreement, Uzbek agricultural exports, including onions, nuts, and dried fruit, receive preferential access to Türkiye, while Turkish industrial products, including machinery and electrical equipment, benefit from reduced import duties in Uzbekistan. The additional products covered by the new agreement have not yet been disclosed.

Kyrgyzstan Urges EAEU to Remove Import Duties on Key Goods

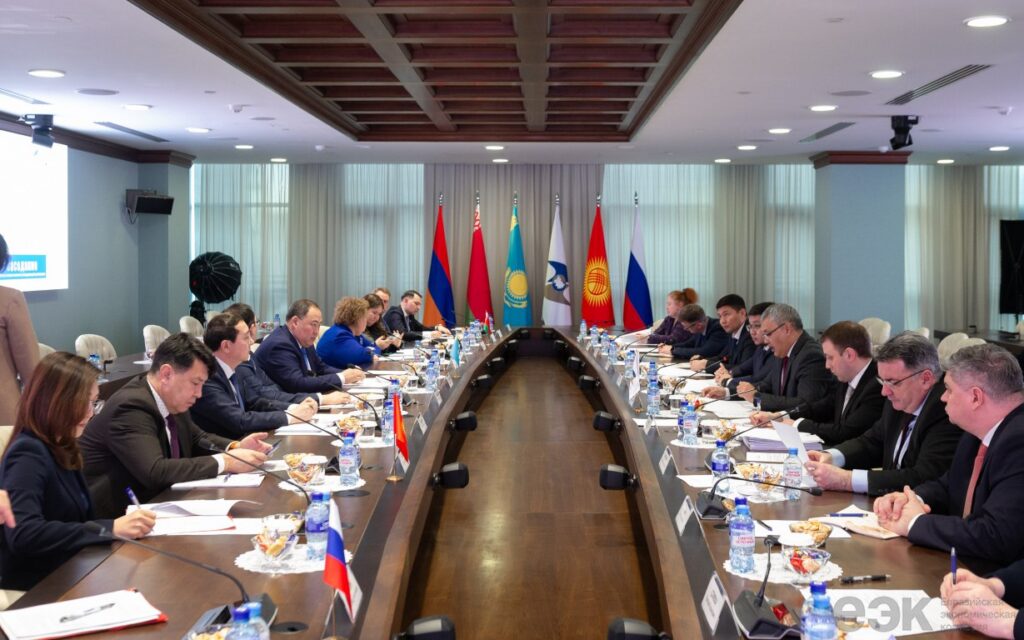
Kyrgyzstan has appealed to its partners in the Eurasian Economic Union (EAEU) to eliminate import duties on a range of socially significant goods, arguing that the measure would help ease the impact of global inflation and slow domestic price growth, according to an official government statement. The proposal was presented during a meeting of the Eurasian Economic Commission (EEC) held in Moscow on March 13. Kyrgyz officials stressed that the country’s economic conditions differ markedly from those of the bloc’s larger member states, making more flexible trade mechanisms necessary. The initiative covers goods considered critical for food security, including flour, vegetable oil, fruits and vegetables, as well as cocoa powder used in the confectionery industry. Authorities in Bishkek believe that removing import duties on these items would lower procurement costs and reduce the transmission of global price increases to the domestic market. “We are seeing rising inflation worldwide, including for the goods we import, particularly agricultural products. In effect, when we import goods at higher prices, we are also importing inflation. Eliminating duties will help reduce the cost of these products,” said Elimbek Kanybek uulu, head of the EAEU Coordination Department, at a press conference in Bishkek. The full list of goods eligible for preferential treatment, along with import volume thresholds, is expected to be published within a month after the EEC formally approves the decision. According to Kanybek uulu, Kyrgyzstan has previously sought similar temporary measures for meat imports. At that time, the suspension of duties contributed to a reduction of around 10% in the price of imported meat. Food security remains a major policy priority. President Sadyr Japarov has said that Kyrgyzstan is currently self-sufficient in six of the nine staple food items included in the national food basket. The government plans to gradually expand domestic production of the remaining products, including flour, vegetable oil, and certain types of fruit. Analysts say future food price dynamics in Kyrgyzstan will depend on both global commodity trends and decisions within the EAEU regarding trade preferences and tariff policy.

Kyrgyzstan Plans Gradual Electricity Tariff Increases to Address Energy Sector Deficit

Kyrgyzstan will raise household electricity tariffs starting May 1, as part of a broader reform program aimed at reducing subsidies and bringing tariffs closer to the actual cost of power generation. Under the new policy, the household tariff will increase by approximately $0.003 per kilowatt-hour, reaching $0.018 per kWh. According to the Ministry of Energy, tariffs are expected to continue rising each May until at least 2030, when they are projected to fully cover production costs. The government has outlined a tentative schedule for further increases: 2027: rise of about $0.004 per kWh 2028: rise of about $0.0045 per kWh 2029: rise of about $0.005 per kWh 2030: rise of about $0.0065 per kWh Even after the planned increase in 2026, households will cover only around 45% of the real cost of electricity, Timur Orozaliev, Director of the Department for Regulation of the Fuel and Energy Complex, told the Kabar state news agency. He said the cost of electricity production in 2026 is estimated at approximately $0.034 per kWh, meaning the new tariff will pay for less than half of actual generation costs. Electricity tariffs for industrial enterprises, financial institutions, restaurants, and government agencies are already two to three times higher than those for households. Despite the planned increases, electricity prices in Kyrgyzstan remain among the lowest in Central Asia. Electricity demand continues to grow. In 2025, national consumption reached 19.3 billion kWh, an increase of 900 million kWh compared with the previous year. Of this total, 15.4 billion kWh was generated domestically, while 3.9 billion kWh was imported from Turkmenistan, Uzbekistan, Kazakhstan, and Russia. Kyrgyzstan regularly experiences seasonal power shortages, particularly during winter, when many households rely on electricity for heating. To address the deficit, the government is working to build new hydropower plants and modernise existing facilities as part of a broader strategy to stabilise the national energy system and reduce dependence on electricity imports.

Kazakhstan’s Emerging Role in Global Rare-Earth Supply Chains

October 10 was one of the most consequential days for global trade policy and one of the most volatile for world markets since the U.S.–China tariff conflict first reignited. After China announced tighter export controls on rare earths, U.S. President Donald J. Trump first posted on Truth Social that “there seems to be no reason” anymore for him to meet with the Chinese leader Xi Jinping at the APEC summit in two weeks' time. Several hours later, the official White House account on X posted a message from Trump that he had learned that "effective November 1st, 2025, [China will] impose large-scale Export Controls [sic] on virtually every product they make, and some not even made by them." He then followed with the declaration that the U.S. will impose a 100% tariff on Chinese imports starting November 1, "or sooner," and launch export controls on critical software. As Washington and Beijing escalate their economic confrontation, the scramble for stable rare-earth supply chains has broadened beyond East Asia. Attention is shifting to Central Asia, where mineral potential and trade corridors align with the broader effort to reduce dependence on China. Kazakhstan has drawn particular attention, not as a single solution, but as a state seeking to leverage its Soviet-era industrial base and access to the Caspian to help meet emerging supply chain needs. Although Kazakhstan has made the most progress in translating its mineral reserves into a functioning mining industry, it remains part of a broader regional effort to diversify away from a single external partner, most notably China. Other Central Asian states are testing their own capabilities to meet global supply chain demands, though most remain constrained by infrastructure, financing, or lack of processing capability. Kazakhstan’s Position in the Emerging Supply Realignment On reserves, Kazakhstan’s rare-earth potential is rooted as much in continuity as it is in discovery. Decades of geological mapping under Soviet administration established its mineral profile, and recent joint surveys by Kazgeology and private firms have both confirmed and expanded those earlier findings. New delineated deposits in the east and center of the country, including the Zhana Kazakhstan site in Karagandy, have reinforced its status as a prospective non-Chinese source of critical materials, with verified concentrations of neodymium, praseodymium, dysprosium, terbium, and samarium. If current resource estimates are validated, the Zhana Kazakhstan deposit could rank among the largest rare-earth reserves in the world. These elements are essential inputs for high-efficiency magnets used in electric vehicles, wind turbines, and advanced defense systems. The U.S. Department of Defense classifies these rare earths as “critical defense materials,” a designation that underscores their strategic relevance rather than any immediate shift in supply. Both the Pentagon and the Defense Logistics Agency have begun increasing stockpiles and exploring alternative processing sources, but for now, the question in Kazakhstan is not geological endowment, which is established, but the terms under which that endowment can be brought to market. On processing capacity, Kazakhstan’s experience in large-scale mining of uranium, copper, and other critical minerals has...

Kazakhstan’s Telecommunications Market Set to Slow in Coming Years

Kazakhstan’s telecommunications market is projected to experience a slowdown in the coming years, with average annual growth expected to hover around 6% for 2025-2027, nearly half the rate seen over the past two years. According to a joint study by Russian firm Nexign and the TelecomDaily agency, the sector grew by 11% in 2024, reaching $2.4 billion, the highest figure in three years. However, analysts attribute this recent surge not to organic market expansion, but to a sharp rise in communication tariffs, which increased by an average of 20%. The price hikes were largely driven by infrastructure modernization costs, the rollout of 5G networks, and increased mobile data usage. Looking ahead, sector growth is expected to be fueled by expanding the customer base, rising service consumption, and the development of digital offerings. Mobile communications accounted for 17% of telecom revenues in 2024, while internet access comprised a dominant 53%. In the past two years, mobile data consumption in Kazakhstan has doubled, placing the country among the global top ten for mobile internet usage per capita. As of March 2025, Kazakhstan had 26 million active SIM cards, more than the total population of approximately 20 million, indicating widespread use of multiple connections. Over 18 million people now have access to mobile internet, and another 3.2 million are connected to fixed broadband. The only segment in decline is fixed-line telephony, which saw a 10% drop in subscribers over the past year, falling to 2.3 million. The study notes that telecom operators will concentrate on expanding 5G coverage, enhancing service quality, and deploying fixed wireless access (FWA) technologies, seen as a more affordable alternative to fiber-optic infrastructure in rural areas. Kazakhstan is also advancing in satellite communications. In 2024, 750 rural schools were connected to the internet via Starlink, while OneWeb launched a ground control center in the country. The Times of Central Asia previously reported that Starlink’s commercial rollout in Kazakhstan is scheduled for the third quarter of 2025. The sector could also benefit from the integration of artificial intelligence in public services and various industries, offering potential new avenues for growth. Nonetheless, key challenges remain for the 2025-2027 period. These include the high costs of extending network coverage to remote areas, escalating prices for imported telecom equipment amid ongoing geopolitical tensions, and intensifying competition among major players. The primary operators in Kazakhstan’s telecom market include Kazakhtelecom JSC (and its subsidiary Kcell JSC), Beeline Kazakhstan (Kar-Tel LLP), Tele2/Altel (Mobile Telecom Service LLP), Transtelecom JSC, Alma TV (AlmaTel Kazakhstan JSC), and Jusan Mobile JSC (KazTransCom).