• KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00222
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
09 November 2026

Viewing results 1 - 6 of 181

Developer of Kazakhstan Tungsten Projects Drops Merger and Plans U.S. Listing

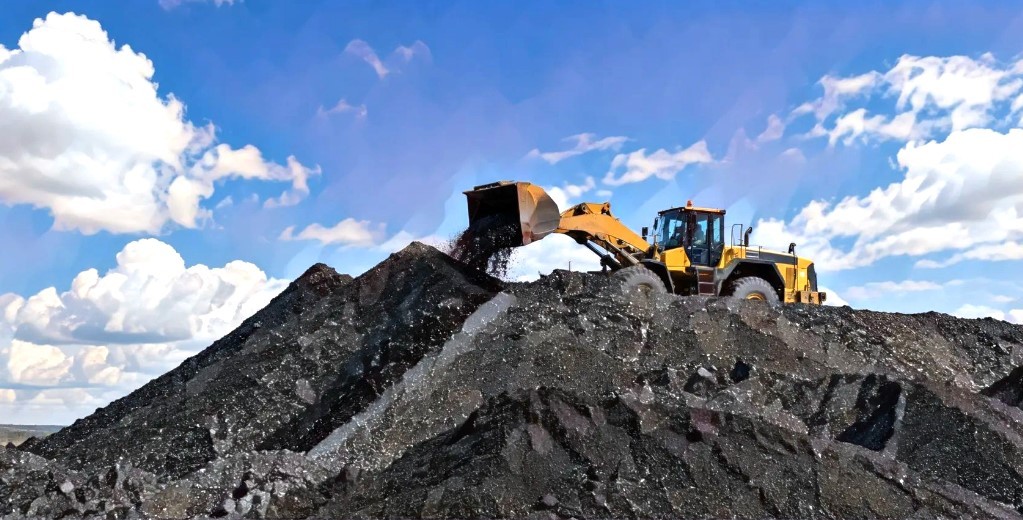
Cove Kaz, the U.S. company developing two major tungsten deposits in Kazakhstan, has dropped its planned merger with Skyline Builders. It now plans to list its shares directly on a U.S. stock exchange in the first half of 2027. The change comes alongside a $32 million investment commitment intended to fund work on the projects. Together, the announcements reshape how Cove Kaz plans to finance development and bring its Kazakhstan business to public investors. The companies announced the mutual termination of their merger agreement on November 2. American Ventures has committed to buying four million Cove Kaz shares at $8 each, implying a company valuation of $1.97 billion. The investment still needs to close. “The additional capital will fund engineering and construction-related work to shorten our time to production,” said Cove Kaz Executive Chairman Pini Althaus. Under its new listing plan, Cove Kaz intends to become a Delaware corporation and adopt the name Kaz Resources Inc. It also plans to bring other affiliated Kazakhstan assets into the company, subject to regulatory approval. The company has not named an exchange and plans to file a registration statement with U.S. securities regulators. Skyline would remain an investor under the revised arrangements. In its own announcement, it said its existing investment and outstanding loan would be exchanged for shares in Cove Kaz. Its stake would be approximately 26% after the new funding closes. Skyline said the revised arrangement should allow its shareholders to realize the value of their investment faster than the merger. The underlying mining venture centers on Northern Katpar and Upper Kairakty in Kazakhstan’s Karaganda Region. Cove Kaz acquired 70% of Severniy Katpar LLP, which holds the project licenses, in April. Kazakhstan’s national mining company, Tau-Ken Samruk, retains the remaining 30%. [caption id="attachment_59844" align="aligncenter" width="1774"] The Northern Katpar tungsten project site in Kazakhstan’s Karaganda Region. Image: Cove Kaz Capital Group.[/caption] The original merger agreement was intended to create a listed supplier of tungsten and other critical minerals for U.S. customers. Tungsten is used in industrial tools, aerospace and defense equipment, making alternative supplies important to Washington’s efforts to reduce dependence on China. Chinese companies already have a foothold in Kazakhstan’s tungsten sector. A $300 million processing plant opened in Almaty Region in November 2024, with Jiangxi Copper among its participants. Cove Kaz’s planned mine and refinery would establish another supply route, focused on U.S. customers. Work at Northern Katpar has moved into engineering and feasibility studies. Cove Kaz’s August update said the definitive feasibility study began in July and was expected to finish before the end of 2027. It covers the mine and a planned refinery in Kazakhstan that would produce ammonium paratungstate, a material used in tungsten manufacturing. The study will help establish the costs and design needed for a final investment decision. It will also support assessments by potential lenders, including U.S. government agencies. Cove Kaz has cited earlier studies indicating potential combined annual production of about 12,000 metric tons from the two deposits, equivalent to roughly 15% of...
Kazakhstan’s Carbon Black: Finding Value in Mining By-Products

London-listed Ferro-Alloy Resources (FAR) is developing a large vanadium deposit in Kazakhstan, as The Times of Central Asia reported in July, and operates a smaller concentrate-processing plant that recovers vanadium, molybdenum and nickel from purchased concentrates. The project could supply growing markets for vanadium and other critical materials. Beyond its core business, FAR has found additional value in by-products already present in the ore. These include its proprietary Carbon Black Substitute (CBS), a rubber-reinforcing filler that the company says is commercially viable, as well as uranium and rare earth minerals, which are not yet in the project economics and could add to future earnings if they prove profitable. Nicholas Bridgen, FAR’s CEO until October 26 and now its non-executive deputy chairman, told TCA: “Our ore gives us multiple sources of revenue. The vanadium pays for the mine and much else, while the carbon and silica left behind, not to mention rare earth metals, become products in their own right.” At an 8% post-tax discount rate, FAR’s Phase 1 delivers a $748 million net present value (NPV) and a 22% internal rate of return (IRR), the company reports, rising to US$931.6 million and 31% on lower capex (November 2025). These figures already include the original CBS, made from vanadium-plant tailings; FAR’s New CBS, made from waste rock, is excluded and would be additional. Rubber manufacturers represent 93% of carbon black demand, making them a potential market for CBS. FAR estimates that the product could sell for about 60–74% less than the conventional carbon black prices cited below and have approximately 90% lower production emissions. Carbon black Carbon black is a reinforcing filler found in most rubber goods, including tires, hoses, conveyor belts, and shoe soles. Its primary particles, only tens of nanometers wide, fuse into aggregates with very high surface area, and rubber chains attach to that surface through both physical and chemical bonds. This makes the rubber stronger, harder, and more resistant to wear. Amorphous silica performs a comparable role, with its surface silanol groups linked to the rubber by silane coupling agents, and it is frequently used alongside carbon black. Unlike graphite, a naturally occurring, highly ordered crystalline carbon prized for conductivity, lubrication and batteries, carbon black is an engineered, near-spherical amorphous carbon made in a furnace for rubber reinforcement. The global carbon black market stood at 15.15 million tonnes in 2025 and is forecast to reach 21.83 million tonnes by 2034, expanding at a CAGR of 4.14%. Rising demand for tires and automotive products is driving much of the growth. Why it is costly Barry Angeline, chemical engineer and polymer physicist, explains that “more than 95% of carbon black is manufactured through the oil-furnace process, which heats and decomposes hydrocarbon feedstocks at high temperatures. The resulting microscopic carbon particles,” he continued, “are quenched, separated from exhaust gases, then processed into pellets for use primarily as a reinforcing agent in rubber. Roughly 1.5 tonnes of fossil feedstock is consumed per tonne of carbon black, and 2.5 tonnes or more of...

Kazatomprom Secures New Uranium Block as Nuclear Demand Expands

Kazakhstan has granted its state-controlled uranium producer Kazatomprom six-year exploration rights to the Kyzyltu block in the Kyzylorda region, where preliminary resources are estimated at around 10,000 metric tons. Kazatomprom announced the exploration license on September 21 and said geological exploration would begin shortly to determine the block’s commercial potential. Kazakhstan remains the world’s largest uranium producer, accounting for roughly 40% of global mine production. Kazatomprom reported output of 25,839 metric tons in 2025 on a 100% basis, including its partners’ shares. The new exploration rights follow a wider effort by Kazatomprom to replenish its resource base. In March, the company outlined six prospective exploration areas covering more than 1,000 square kilometers, with planned exploration spending through 2030 of $155 million to $176 million. The company is also pursuing longer-term supply agreements with overseas buyers. An August outlook from Bloomberg Intelligence expects Kazatomprom and Canada’s Cameco to provide much of the increase in global uranium mine production during the remainder of this decade. Bloomberg estimates mined supply could rise 23% from 2025 levels to around 193 million pounds of U₃O₈ annually during 2028–2031. It estimates Kazatomprom could reach around 80 million pounds of U₃O₈ annually if sufficient sulfuric acid is available. In this base scenario, the uranium market could remain in surplus through 2031 before moving into deficit from 2032, as demand rises and depletion of low-cost reserves in Kazakhstan and Canada constrains supply. New mines generally require long development periods, limiting the ability of supply to respond quickly to higher demand. China is the largest near-term source of additional demand, accounting for 45% of nuclear capacity currently under construction or planned and has set a target of 110 gigawatts of nuclear capacity by 2030. The United States and European Union are also major markets for Central Asian uranium. U.S. civilian reactor operators purchased 46.9 million pounds of U₃O₈ equivalent in 2025, with Kazakhstan accounting for 28% of deliveries and Uzbekistan 7%, according to the U.S. Energy Information Administration. EU utilities purchased 14,678 metric tons of natural uranium in 2025, with Kazakhstan accounting for 20.3% of deliveries and Uzbekistan 10.4%, according to the Euratom Supply Agency. The European Commission’s nuclear investment assessment projects EU nuclear capacity rising from 98 gigawatts in 2025 to around 109 gigawatts by 2050. Kazakhstan also retains a production-cost advantage. Bloomberg attributes this largely to the widespread use of in-situ recovery, which allows uranium to be extracted without conventional open-pit or underground mining. Sulfuric Acid Supply Remains a Constraint Kazatomprom’s September 21 announcement also addressed Russian sulfuric-acid deliveries, an important issue because the chemical is used extensively in Kazakhstan’s in-situ uranium operations. The company said Russian measures introduced on September 12 had changed export approval procedures through the end of 2026, but had not prohibited exports. Russian suppliers had confirmed their intention to fulfill existing 2026 contracts and were seeking the necessary approvals. Kazatomprom said it did not expect the changes to have a material effect on its 2026 operations or production guidance. Talks over supplies...

Kazakhstan Mining Royalty System Delayed Until 2029

Kazakhstan plans to delay a new mining royalty system until 2029, postponing a reform that would tax raw ore more heavily than metals processed inside the country. The government backed the two-year delay, saying parts of the system still need further work. The royalty regime would apply only to new mining licenses issued from 2027 onward for areas where mining rights have not previously been granted. For example, a company receiving a new license to develop a previously unlicensed copper deposit would come under the royalty system, while an existing copper mine would continue paying the current mineral extraction tax, or MET. The main difference is when and how the tax is calculated. Under MET, tax is charged on minerals extracted from the ground. Under the proposed royalty system, the payment would instead be linked to the sale of the mineral product. This approach is more closely tied to actual sales. More significantly, the tax rate would fall as the mineral is processed further. The Tax Code sets a rate of 13% for ore, 10% for concentrate, and 7% for metals. A miner selling raw ore would therefore face almost twice the royalty rate of a company producing metal, giving businesses an incentive to process more of their output in Kazakhstan. Putting the system into practice has proved more difficult. The government says it still needs to decide how royalties should be calculated on minerals recovered from old tailings and other mining waste, and how the rules should treat expensive new projects and valuable minerals produced alongside a mine’s main commodity. The proposed rules will be tested against mining companies’ financial models before they take effect. The Finance Ministry had previously raised concerns about a rapid transition to royalties. In 2024, the State Revenue Committee estimated that applying rates similar to those used in Western Australia could reduce annual budget revenue by about KZT 270 billion ($606 million), while extending royalties to all subsoil users could result in losses of about KZT 450 billion ($1.01 billion). Those estimates do not apply directly to the much narrower reform now planned, which covers only future licenses in areas where subsoil use rights had not previously been granted. They do, however, help explain the government’s caution over changes to subsoil taxation. The State Revenue Committee says tax payments from more than 7,000 subsoil users, including oil and gas producers, account for around 35% of Kazakhstan’s republican budget revenue. The postponement therefore leaves the main structure of the reform intact but gives the government another two years to decide how it will work in practice. The Times of Central Asia previously examined the arguments surrounding the reform and Kazakhstan’s effort to link mining taxation with greater domestic processing.

South Korea Steps Up Central Asia Critical Minerals Push

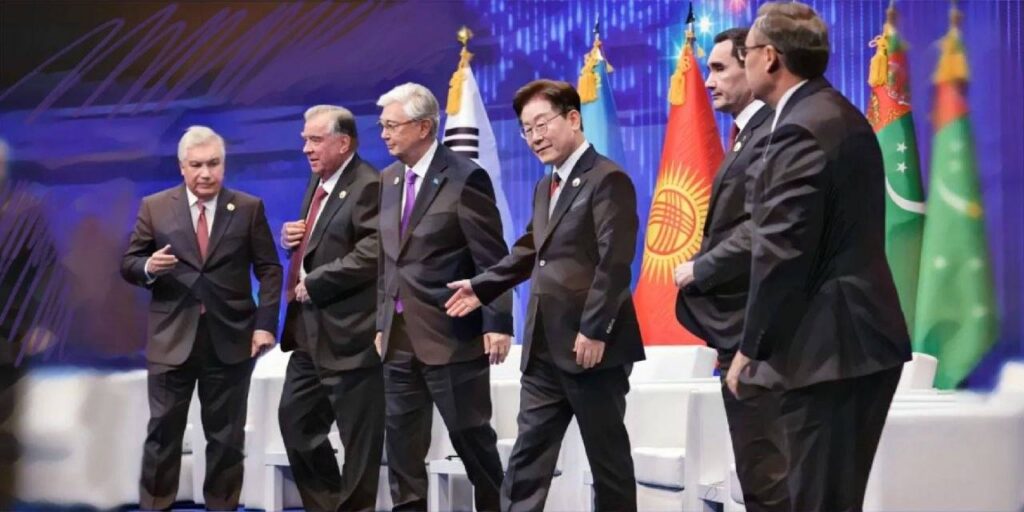
The first South Korea–Central Asia summit, held in Seoul on September 16, capped three days of bilateral meetings that produced more than 70 agreements and memorandums. The leaders agreed to meet every two years, a separate C5+1 forum for industry ministers was established, and critical minerals took a central place on the new agenda. The main question now is how many of those documents will translate into mines, processing plants, and long-term contracts. South Korea needs reliable supplies of metals for its automotive, electronics, battery, and energy industries. Central Asia wants to use that demand to develop domestic processing and reduce its reliance on raw material exports. Seoul proposed combining the region’s resources with its own exploration, mineral processing, and manufacturing technologies. President Lee Jae Myung spoke of cooperation across the production chain, from identifying deposits to manufacturing finished products. Rare metals centers being established at key locations in Central Asia are intended to support joint research and specialist training. Until now, South Korea has worked with the region’s countries largely through bilateral ties. The new C5+1 format adds a regional mechanism to those relationships. Kazakhstan will host the next summit in 2028. Kazakh financier and analyst Rasul Rysmambetov believes the value of the new format will depend on the region’s ability to secure tangible industrial results. He sees South Korea as an attractive partner because of its experience with rapid industrialization and its strengths in building industrial facilities. “The priority for Central Asia is to stop selling raw materials. We need to establish processing in the region. The heads of state’s visit to Seoul was highly productive. In fact, all summits in similar formats have been productive. The main question now is how to move away from exporting raw materials and toward joint industrialization,” Rysmambetov told The Times of Central Asia. Uzbekistan put forward a broader regional proposal. President Shavkat Mirziyoyev called for an investment alliance for critical minerals, with processing clusters bringing together exploration, mining, and the production of high-value goods. Uzbekistan and South Korea are already developing a joint rare metals center and have agreed to strengthen cooperation throughout the production chain. Kazakhstan offered Korean businesses a broader package covering rare metals, nuclear and clean energy, and artificial intelligence. Urban development was also part of the talks, including the Alatau Smart City project near Almaty. The countries upgraded their ties to a comprehensive strategic partnership and signed a memorandum on the peaceful use of nuclear energy. The energy agreements also cover conventional resources. In April, South Korea said it had secured 18 million barrels of Kazakh crude oil. In Kyrgyzstan, Korean organizations are working with their Kyrgyz counterparts to identify possible antimony and tungsten projects and strengthen exploration capacity. Tajikistan is also offering cooperation on antimony, as well as precious metals, building on the first Korea–Tajikistan Minerals Forum, which took place in August. The minerals agenda is complemented by Korean willingness to invest in transport and infrastructure. South Korea and Uzbekistan agreed to expand Korean participation in...

Astana Finance Days: From BlackRock to Mining and Data Centers

In a trading hall in Astana, BlackRock was explaining why investors have become more cautious. A few floors away, geologists were pitching 23 mining projects, while financiers debated how many megawatts the next wave of artificial intelligence will require. That was how the first day of Astana Finance Days unfolded, as Kazakhstan brought together financial groups managing more than $26 trillion in assets – and sought to show them where that money could be put to work in Central Asia. The ninth Astana Finance Days is taking place on September 9–10 at the Astana International Financial Centre (AIFC), Kazakhstan’s special financial jurisdiction with its own regulator and a court system based on English common law principles. According to the organizers, around 8,000 participants from 90 countries registered for the forum. Institutions represented include BlackRock, Goldman Sachs, Capital Group, Brookfield, Rothschild & Co., Hong Kong Investment Corporation, and IFC Asset Management Company. The stated $26 trillion refers to the combined assets under management of participating firms worldwide – not investment pledged to Kazakhstan. More concrete signals emerged on the sidelines. Meshal Jaber AlFaras, Janus Henderson Investors’ head of the Middle East, Africa, and Central Asia, said the investment group is considering direct investments in Kazakhstan and plans to expand its presence in the country. Janus Henderson manages around $500 billion in assets. AlFaras did not disclose potential projects or investment amounts. A New Price for Risk One of the first day’s most prominent discussions took place at the Astana International Exchange (AIX), the AIFC’s stock exchange. Ben Powell, Chief Investment Strategist for the Asia-Pacific region at the BlackRock Investment Institute, spoke about how geopolitics is reshaping capital flows. “Today, we are in a structurally new regime – moving into a more complicated world where geopolitical fragmentation is intensifying, alliances are breaking down, and international relationships are changing. Of course, this affects investors. They need to completely rethink their approaches to investing,” Powell said. Higher inflation and interest rates, he continued, are changing attitudes toward risk. For smaller emerging markets, that means greater scrutiny of currency stability, regulation, and liquidity. A few halls away, that global discussion was already turning into pitches for specific mineral projects. From the Geological Map to the Investor Fifteen companies brought 23 mining projects to Astana Finance Days. Most are still at the exploration stage. In the industry, such companies are known as juniors. They search for mineral deposits and try to demonstrate that the resources they discover can eventually be mined profitably. For an ordinary bank, the risk is high: a promising area on a geological map does not yet guarantee a working mine. At the forum, companies briefly pitched their projects before moving into individual negotiations. More than ten Kazakh and international investors and strategic partners attended the pitch session. The Junior Mining Platform, launched this spring, is intended to turn this search for capital into a permanent mechanism. Private investors take on early geological risk; as reserves are confirmed and technical uncertainty declines, larger...