• KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10850
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
01 November 2026

Viewing results 1 - 6 of 10

Japanese Firms Test Middle Corridor Freight Route as Tokyo Funds Aktau Port Upgrade

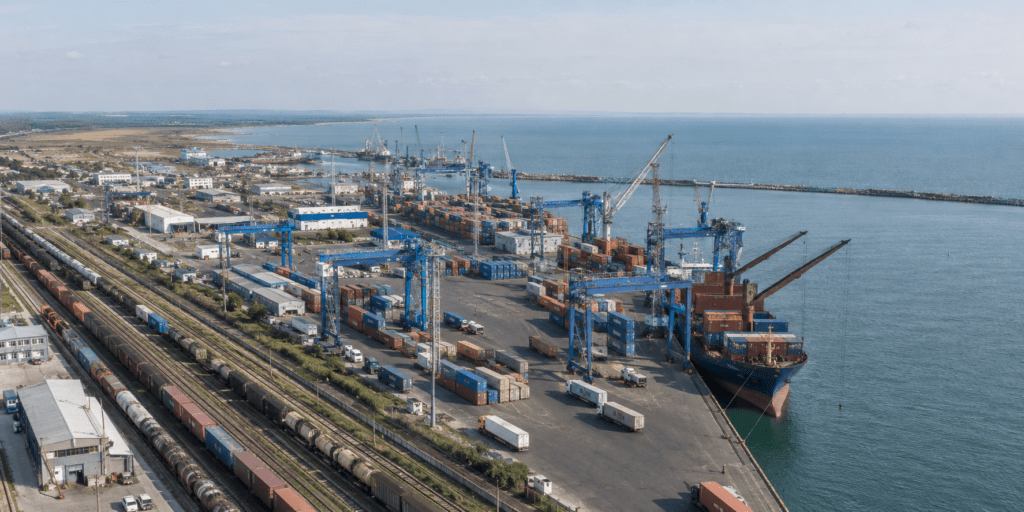
Japan is assessing greater use of the Middle Corridor following trial shipments by Japanese companies, as Tokyo funds customs upgrades at Kazakhstan’s port of Aktau worth up to $4.5 million. The results of the trials were presented at an October 19 conference in Tokyo, which focused on Japan’s transport links with Central Asia and the Caucasus. The trials assessed delivery times and costs, alongside customs procedures and logistics services. Japan’s funding provides for the installation of a stationary X-ray inspection system for large cargo at Aktau, where containers are shipped across the Caspian Sea to Azerbaijan. The grant, agreed in January, is valued at up to 719 million yen (approximately $4.5 million). The equipment is expected to reduce inspection times by two-thirds. Kei Takagi, Japan’s State Minister of Economy, Trade and Industry, linked Tokyo’s interest in the Middle Corridor to efforts to diversify international transport routes and strengthen trade with Central Asia and the Caucasus. For Japanese exporters, the Middle Corridor could provide an alternative way to reach markets across Central Asia and onward to Europe. Japanese cargo must first reach the corridor by sea, through China or another point connecting to the overland transport network. The route’s attractiveness therefore depends on transshipment costs and reliable connections, including efficient customs clearance. In 2025, the Middle Corridor handled 4.12 million metric tons of freight, down from 4.48 million tons in 2024 but approximately five times the volume recorded seven years earlier. According to Kazakhstan’s Ministry of Transport, transit times along the corridor have fallen from 28–32 days to 13–17 days. The ministry’s estimate is for the corridor, rather than a quoted delivery time from Japan. Beyond freight transport, conference participants discussed digital infrastructure across the Caspian Sea. The Kazakh side highlighted the October 15 inauguration of a 380-kilometer fiber-optic cable linking Kazakhstan and Azerbaijan. The cable across the Caspian seabed is intended to carry international internet traffic between Central Asia and the South Caucasus, with adjustments to the line continuing through the end of 2026. Direct air connections were also discussed. Air Astana plans to launch scheduled flights between Almaty and Tokyo’s Narita Airport in December 2026.
Azerbaijan–Kazakhstan Ties Could Reorient Central Asian Integration

The five Central Asian presidents met with Azerbaijan’s Ilham Aliyev in Avaza on October 8 for the Consultative Meeting of the Heads of State of Central Asia and the Republic of Azerbaijan. Azerbaijan’s participation brings a principal outlet for Central Asian trade into the six governments’ economic deliberations. Within their consultative format, the states can coordinate industrial projects with the transport services through which regional producers reach foreign markets. If Azerbaijan and Kazakhstan connect cross-Caspian transport more closely to industrial cooperation, the corridor could become an organizing axis for regional integration. The Case for Trans-Caspian Integration Closer Azerbaijan–Kazakhstan cooperation would make cross-Caspian transport more dependable if trains reach Kazakhstani ports in time for Caspian sailings and cargo arriving at Azerbaijani terminals connects with onward services through Georgia. A 2023 assessment by the International Bank for Reconstruction and Development (IBRD), also called the World Bank, identified trade among Kazakhstan, Azerbaijan, Georgia, and Europe as a driver of corridor demand, giving regional exporters a place alongside China–Europe transit traffic. Onward connections from the China–Kyrgyzstan–Uzbekistan (CKU) railway now under construction could run through Turkmenistan and across the Caspian to Azerbaijan, providing an alternative to routes through Iran. Conflict involving Iran strengthens Azerbaijan’s position as the more dependable western outlet for Europe-bound exports. Greater predictability could offset the cost of a Caspian crossing by reducing the stocks firms must hold against delays and the losses caused by interrupted deliveries. Extending the operating coordination developed with Kazakhstan to these southern connections could make Azerbaijan commercially preferable for Central Asian exporters serving European markets. Kazakhstan and Azerbaijan occupy the principal positions in this prospective reorientation. Together, they represent approximately one-third of the six countries’ population but account for more than three-fifths of their nominal GDP. Yet bilateral merchandise trade amounted to only $470.7 million in 2025. Their combined economic weight is thus disproportionate to the commerce presently linking them. The infrastructure and institutions connecting industrial investment to markets across the Caspian could give the two countries a basis for organizing wider regional integration, provided firms sustain commercial relationships through those connections. The Bilateral Basis for Regional Integration Export commitments depend on the cost and timing of the complete transport service. At Avaza, Kazakhstan’s President Kassym-Jomart Tokayev attached “particular importance” to developing the Trans-Caspian International Transport Route (TITR), also known as the Middle Corridor. His Azerbaijani counterpart, Ilham Aliyev, advocated joint investment, manufacturing, and entry into foreign markets. For firms undertaking joint production, the commercial viability of Aliyev’s proposal would depend on transport coordinated from departure to delivery. Kazakhstan is developing the Middle Corridor along with the eastern branch of the International North–South Transport Corridor, which links Russia and Iran through Kazakhstan and Turkmenistan. At Avaza, Turkmenistan’s President Serdar Berdimuhamedov supported the development of North–South corridors in addition to East–West routes. Tokayev also highlighted the continuing importance to Kazakhstan of the North–South route in cooperation with Russia. Kazakhstan’s multi-vector approach thus extends to transport infrastructure: the Middle Corridor strengthens westward access without displacing the commercial connections maintained...

Kazakhstan Weighs a Second Major Oil Export Route

Following repeated disruptions to the Caspian Pipeline Consortium (CPC) system, Kazakhstan’s leading oil producers are examining a much larger Trans-Caspian export route. A working group representing eight shareholders responsible for production in the Tengiz and Kashagan fields has commissioned a feasibility study for moving crude from the Atyrau area to Aktau, across the Caspian to Baku, and onward through the Baku–Tbilisi–Ceyhan (BTC) pipeline. The study is expected to go to shareholders in November. The current proposal follows a policy line set out in July 2022, when President Kassym-Jomart Tokayev identified the Trans-Caspian route as a priority and instructed KazMunayGas to examine options, including possible participation by Tengiz investors. The present study puts a much larger export channel under commercial examination. CPC remains indispensable, carrying more than four-fifths of Kazakhstan’s oil exports. Of the 78.7 million tons of oil that Kazakhstan exported in 2025, 64.8 million went through CPC. Existing alternatives are small by comparison. Even the eastbound flow to China and the Schwedt route through Russia together absorb only a fraction of CPC volumes, while current Trans-Caspian shipments are smaller still. What has changed is the cost of concentrating so much of Kazakhstan’s oil exports on CPC, not its underlying commercial importance. The producers are in fact studying two alternatives, a subsea pipeline or a much larger tanker fleet. The Trans-Caspian pipeline idea itself is not new. Variants surfaced in 2009 and appeared again in 2016. What is new is the present combination of shareholder sponsorship, operational urgency, and contemplated scale. Each option is intended to support volumes of up to 35 million metric tons a year. KazMunayGas (KMG) moved 1.3 million tons from Aktau toward BTC in 2025, while its agreement with SOCAR provides for a phased increase to 2.2 million tons annually. The shareholder proposal would expand the existing Trans-Caspian route into a second major export channel. Why Redundancy Now Repeated interruptions in CPC flows have converted the risks of route concentration into lost oil production and a lower national production target. In July, for example, attacks struck tankers loading or approaching the CPC marine terminal, repeatedly suspending operations. Energy Minister Yerlan Akkenzhenov later put production lost to January, June, and July disruptions at about 3.5 million tons and reduced the 2026 production target from 98 million to 96 million tons. Even temporary interruptions reduce revenues and force urgent production decisions upstream. A Trans-Caspian route capable of carrying 35 million tons a year would not replace CPC, but it would materially reduce Kazakhstan’s exposure to a prolonged interruption. The reported figure equals more than half the 64.8 million tons exported through CPC in 2025 and is almost sixteen times the 2.2-million-ton level contemplated under the existing KMG–SOCAR expansion agreement. It would allow Kazakhstan to divert a substantially larger share of production during disruptions. Kazakhstan can now reroute one or two million tons relatively quickly, but not the tens of millions carried through CPC. The first constraint is inside Kazakhstan. Tengiz and Kashagan lack a high-volume pipeline connection to...

From Critical Minerals to Connectivity: South Korea’s Stakes in Central Asia

On September 16, Seoul hosted the first Korea–Central Asia Summit, bringing President Lee Jae Myung together with the heads of all five Central Asian states. The meeting elevated a dialogue that has run at a ministerial level since 2007 to the level of heads of state. The leaders adopted a Seoul Declaration setting the terms for future engagement and agreed to hold summits every two years. On September 14, trade and industry ministers from South Korea and the five Central Asian states met in Seoul for the first C5+Korea Industry Ministers’ Meeting. They signed a joint statement launching a standing platform for industrial cooperation. Uzbekistan’s Ministry of Investment, Industry and Trade used the occasion to push for a shift away from raw-material trade toward joint production and localization. Behind the diplomatic choreography sits a practical problem: the minerals both sides keep discussing cannot move without a route to carry them. A Minerals Agenda with Separate Tracks South Korea relies heavily on imported minerals for its manufacturing industries. Seoul has been developing separate plans with each country. With Tajikistan, discussions have focused on gold and silver, alongside antimony. With Kyrgyzstan, Seoul has been discussing antimony and tungsten. Cooperation with Uzbekistan covers minerals and digital manufacturing. With Kazakhstan, a central issue is moving beyond raw exports toward processing inside the country, as The Times of Central Asia reported ahead of the summit. South Korean firms are pursuing supply diversification independently. POSCO International and LX International have been expanding overseas mineral investments, including graphite and nickel projects, amid Chinese export restrictions. The Transport Connection Consider the Bolashak chrome mine in Kazakhstan, which Eurasian Resources Group launched in late 2024. The company plans to ramp it up to a design capacity of 7.5 million metric tons of chrome ore a year. Production on that scale makes reliable transport an essential part of the commercial equation. An Atlantic Council analysis identifies limited processing capacity and underdeveloped westward routes as obstacles to U.S. mineral partnerships with Central Asia. It presents the Trans-Caspian Middle Corridor as a route to Western markets that avoids Russian and Iranian territory. That argument needs a distinction when applied to Korea. The corridor runs westward toward Europe; it is not a prerequisite for minerals to reach South Korea. Its relevance is the wider choice of buyers it could offer Central Asian producers, including potential Korean-backed processing ventures serving those markets. That corridor is being built out. The Aktau container hub has a planned capacity of 240,000 twenty-foot equivalent units. The World Bank-backed Mointy–Kyzylzhar railway is meant to remove a 149-kilometer detour and accommodate 30 train pairs a day, against roughly ten on the existing constrained route. Traffic is already rising: 125 container trains crossed Kazakhstan on the Trans-Caspian route in the first quarter of 2026, up 34.4% year-on-year. Japan has also become involved, pledging in August 2025 to help modernize customs operations at the port of Aktau. The Seoul Declaration also backs Korean participation in transport infrastructure, including modernization and digitalization. In...

Middle Corridor Freight Grows, but Eastbound Cargo Lags

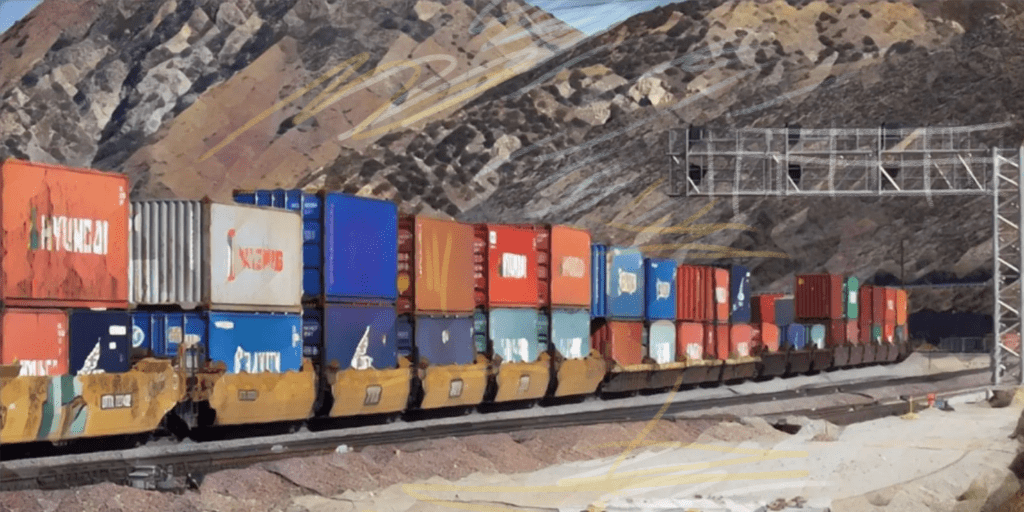
Container traffic is growing along the Middle Corridor from China and Central Asia toward Europe, but the route is far less busy in the opposite direction. In the first eight months of 2026, about 80% of container traffic moved westward and only 20% eastward. Operators are now looking for goods in Europe and Türkiye that can be shipped back across the Caspian Sea and Kazakhstan toward Central Asia and China. Container traffic totaled 53,574 TEU along the Trans-Caspian International Transport Route, also known as the Middle Corridor, in January–August. One TEU is equivalent to a standard 20-foot container. During the same period last year, the figure was 48,326 TEU, meaning traffic increased by 11%. But the flows were highly uneven. According to ADY Express, 42,642 TEU moved from east to west, compared with just 10,932 TEU in the opposite direction – a ratio of almost four to one. Interest in the route increased sharply after 2022, when companies began looking for additional ways to move goods between China and Europe without transiting Russia. Over the past several years, participants in the Middle Corridor have focused on increasing shipments from China. New train services have been introduced, while countries along the route have invested in railways, terminals, and Caspian ports. Chinese freight has grown, but there is still not enough cargo for the return journey. For transport operators, the issue comes down to finances. Once containers reach Europe, they need to be used again or repositioned. If there is cargo for the return journey, the equipment generates revenue in both directions. Without it, operators can face the cost of moving empty equipment. The 80%-to-20% split, however, does not establish how many containers actually make the return journey without cargo. Railway companies themselves are now acknowledging the shortage of eastbound cargo. “For this, backhaul freight is necessary,” Emil Mammadov, Adviser to the Chairman of Azerbaijan Railways, said at the Black Sea and Caspian Freight Forum 2026 in Baku. According to Mammadov, attracting cargo from Europe would help increase freight volumes, optimize transportation costs, and allow at least some containers to be returned to their countries of origin. Until now, the route has been promoted more actively in China, Kazakhstan, Azerbaijan, Georgia, and Türkiye. European companies have received less attention. Railway operators are now looking for customers at the western end of the corridor as well. A shipment from Türkiye showed what such a return journey could look like. In May, KTZ Express and Pasifik Eurasia dispatched a train from Izmir to China carrying household refrigerators. Fifty 40-foot containers crossed the Caspian Sea, traveled through Kazakhstan, and continued into China via the Altynkol border station. For now, such shipments remain limited. The Chinese side continues to push for more westbound traffic. On September 9, Azerbaijan Railways held talks with Shanghai International Port Group and Lianyungang Port on expanding shipments of Chinese goods through Kazakhstan, across the Caspian, and through Azerbaijan toward Europe. ADY Express also reported that 265 container block trains operated along...

Insider’s View: Why Uzbekistan’s Caspian Push Might Be Beneficial for Georgia

Over the past year, Georgia has shifted its focus towards Central Asia, establishing strategic partnerships with Kazakhstan and Uzbekistan. The country has long-term plans for the region in several development areas, including trade and transport logistics. However, the current phase of Georgian–Central Asian relations is not solely based on economic pragmatism. It should also be viewed as a means of preserving sovereignty in the face of global challenges that are catalyzing the old-world order to collapse. In this context, strategic connectivity can be defined as a vital component of small states’ long-term stability and security, placing it on a par with defense capabilities. By intensifying political and economic ties with Tbilisi, Tashkent is seeking to reinforce the Western orientation of its foreign policy. This is necessary to successfully balance between the major powers and minimize the risk of becoming overly dependent on neighboring Russia or China, for example. However, this move should not be perceived as a counter to the geopolitical ambitions of non-regional actors in Central Asia and the South Caucasus. It is devoid of political overtones and reflects the parties’ desire to strengthen their sovereignty based on shared economic interests and opportunities. The Trans-Caspian International Transport Route (Middle Corridor) is the key driver in this dynamic, and its significance extends far beyond transport connectivity. It is a mutually beneficial initiative whose ultimate goal is to ensure regional stability and sustainable economic growth. Thus, Uzbekistan gains an alternative route to the European Union market — the country’s third-largest trading partner — via the Georgian ports of Poti and Batumi on the Black Sea coast. Meanwhile, the Trans-Caspian route provides Georgia with access to the rapidly growing markets of East and South Asia via Uzbekistan and neighboring countries. The new transit corridor concepts promoted by Uzbekistan in the context of the expanding Central Asian partnership deserve special attention. Tashkent and Tbilisi have enormous potential to develop transport cooperation by establishing intercontinental logistics chains: China–Kyrgyzstan–Uzbekistan–Turkmenistan–Azerbaijan–Georgia–Turkey/EU, and India–Pakistan–Afghanistan–Uzbekistan–Kazakhstan–Azerbaijan–Georgia–EU. Both projects involve connecting the China-Kyrgyzstan-Uzbekistan (CKU) railway and the Trans-Afghan Railway Corridor (the Kabul Corridor), which are an absolute priority for Uzbekistan, with the Middle Corridor. This will significantly increase the republic’s exports of transport services by attracting additional transit flows from the South Caucasus, Turkey and Europe, while also expanding the freight base for the aforementioned railway corridors. The issue of jointly promoting new trade routes along the east-west and north-south axes (from Europe to China and India, respectively) through Uzbekistan requires ongoing expert discussion to amplify its relevance. To fully realize its own transit potential, it is insufficient for Uzbekistan to focus solely on the infrastructure development of the Middle Corridor. This is because, even after the launch of the China–Kyrgyzstan–Uzbekistan railway, the country’s ability to attract additional transit cargo flows would remain very limited due to Kazakhstan’s dominance in rail transport between the EU, Central Asia, and China via the Caspian Sea. For Uzbekistan, it is far more important to extend the Middle Corridor to China and India. This would...