• KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
20 September 2026

Viewing results 7 - 12 of 345

Kazakhstan and Kyrgyzstan Give Conflicting Accounts of Four-Country Blackout

Kazakhstan and Kyrgyzstan have given differing accounts of what triggered the August 14 blackout that cut electricity across swathes of Central Asia. Three days later, the initiating event remains unresolved, and the times released by the two sides do not fit neatly into the same sequence. Kazakhstan’s national grid operator KEGOC says two hydrogenerators at Kyrgyzstan’s Toktogul Hydropower Plant, with a combined capacity of 600 MW, disconnected at 2:37 p.m. Kazakhstan time. KEGOC said the sudden loss of generation overloaded the North-East-South transit corridor, separating southern Kazakhstan from the rest of the national grid and the interconnected systems of Kyrgyzstan, Uzbekistan, and Tajikistan. A special commission is investigating the causes. Meanwhile, Kyrgyzstan’s National Electric Grid has given a different chronology. It said that at 3:34 p.m. Kyrgyzstan time, an external disconnection occurred on a high-voltage line linking the northern and southern parts of Kazakhstan’s power system. The Central Asian network then split into an isolated section, and Kyrgyzstan temporarily operated separately while automatic protection systems worked to protect equipment. The one-hour difference between the countries’ clocks makes the discrepancy clearer. Kazakhstan has used UTC+5 nationwide since 2024, while Kyrgyzstan uses UTC+6. That puts Kyrgyzstan’s reported line disconnection at 2:34 p.m. Kazakhstan time, three minutes before KEGOC’s stated 2:37 p.m. Toktogul shutdown. The two times may describe different stages of a fast-moving cascade, but they do not establish the same starting point. A third timestamp complicates the sequence. Alatau Zharyq Company said three 500 kV KEGOC transmission lines shut down at 2:38 p.m., and that those lines triggered automatic load-shedding and frequency protection in Almaty and the surrounding region. Taken together, the public statements leave a sequence of 2:34 p.m., 2:37 p.m., and 2:38 p.m. that investigators will need to reconcile. TCA reporters in Almaty and Bishkek experienced power cuts, while local media reported outages in Dushanbe, Khujand, and southern parts of Uzbekistan. In Kazakhstan, the disturbance affected consumers in the Zhambyl, Turkistan, Kyzylorda, Zhetysu, and Almaty regions, with further restrictions in Karaganda, Ulytau, and Abai. KEGOC said supplies were restored across the affected regions later that afternoon. The four-country impact reflects how tightly the systems are connected. Kazakhstan, Kyrgyzstan, Tajikistan, and Uzbekistan operate in parallel through the Central Asian power system. Cross-border links allow operators to share electricity and reserve capacity, but also mean that a sudden loss of generation or a major transmission line can be felt beyond one national grid before protection systems isolate the disturbance. Central Asia has been here before. In January 2022, a major blackout hit southern Kazakhstan, Kyrgyzstan, and Uzbekistan. The event also involved a sharp imbalance on the regional network and the separation of Kazakhstan’s northern and southern grids. Its precise starting point was disputed in the immediate aftermath. The regional grid dates to the Soviet period. Uzbekistan later withdrew from the old electricity ring, leaving Tajikistan largely isolated for years. Regional links have since been rebuilt; Tajikistan began reconnecting to the unified system in 2024. An Asian Development Bank project is adding...
Why Central Asia Growth Forecasts Differ So Sharply

How fast can Central Asia continue to grow? The Eurasian Development Bank (EDB) and the International Monetary Fund (IMF) give markedly different answers. The contrast is sharpest in Kyrgyzstan, where the EDB expects another year of double-digit growth, while the IMF sees a much more pronounced slowdown. Both institutions are looking at the same countries and have access to broadly the same set of macroeconomic data. Their forecasts, however, reflect different assessments of how much of Central Asia’s recent momentum can be sustained. The EDB expects strong investment to keep growth high, while the IMF is more cautious about how long the recent pace of expansion can continue. The EDB is itself a regional development institution. It was established by Russia and Kazakhstan in 2006, with Armenia, Belarus, Kyrgyzstan, and Tajikistan later becoming shareholders. Uzbekistan joined the bank in 2025. The EDB is headquartered in Almaty. The comparison covers the four Central Asian states that are EDB members; Turkmenistan is not included. Its latest forecast for Central Asia is optimistic. In 2026, the EDB expects growth of 10.2% in Kyrgyzstan, 8.3% in Tajikistan, 7.9% in Uzbekistan, and 5.5% in Kazakhstan. The region’s economy as a whole is expected to grow by more than 6.5%, with its combined GDP exceeding $600 billion for the first time. The IMF gives lower figures. Its latest available country projections put 2026 growth at 4.6% for Kazakhstan, 6.8% for Uzbekistan, 6.1% for Kyrgyzstan, and 6.0% for Tajikistan. These projections were published at different times rather than as a single set of four country forecasts. The largest gap is in Kyrgyzstan, where the forecasts differ by 4.1 percentage points, but there are nevertheless modest percentage point gaps between the forecasts for Tajikistan (2.3), Uzbekistan (1.1), and Kazakhstan (0.9). These differences are large enough to raise the question: why the difference in expectations? Part of the answer lies in how the institutions assess the effect of a more uncertain global economy. The IMF expects the world economy to grow by 3% in 2026 and 3.4% in 2027. Its July update said the conflict in the Middle East was weighing particularly heavily on energy importers and warned that renewed conflict or financial-market disruption could weaken the outlook. For the four countries, this means different things. Kazakhstan exports oil and benefits from high prices, although it also depends on the condition of export routes and external demand. Kyrgyzstan and Tajikistan import a significant share of their fuel, while their economies are closely linked to migrant remittances. Uzbekistan has a larger domestic market and its own resource base. Kazakhstan illustrates the logic of the IMF forecast particularly well. Its GDP grew by 6.5% in 2025, one of its strongest performances in recent years. The Fund does not expect that surge to be repeated. Oil production is expected to stabilize after last year’s increase, with growth slowing to 4.6% in 2026, according to the IMF forecast. This does not mean that the Fund attributes everything to oil. Domestic demand remains strong,...

Tajikistan’s Somon Air Adds Routes, Receives First Boeing 737 MAX

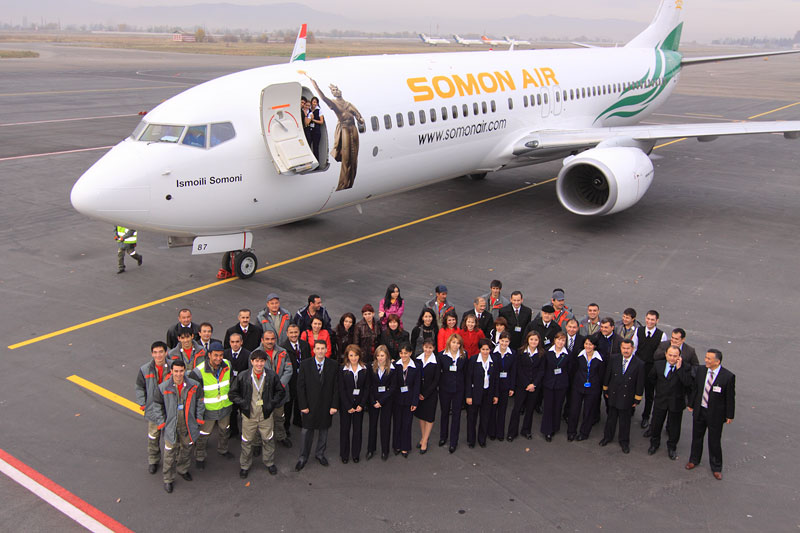
Somon Air, Tajikistan’s national carrier, says it will start direct flights once a week between Dushanbe and Minsk, Belarus, on August 29. “Flights will operate every Saturday,” said the airline, which received its first Boeing 737 MAX aircraft in Dushanbe on August 3 as part of a fleet expansion. The airline, which is adding international routes and working to strengthen its role in the Central Asian aviation market, committed to ordering up to four 787 Dreamliners and up to 10 737 MAX aircraft in an announcement with Boeing in late 2025. At the time of the agreement’s announcement, Somon Air was operating six Next-Generation 737 airplanes to destinations across Europe, Asia and the Middle East, according to Boeing. The expansion of Somon Air’s international flights will “contribute to the development of tourism, cultural exchange, the expansion of economic relations, and the enhancement of Tajikistan's reputation as a country leading the ‘open door´ policy,” the state Khovar news agency reported on Monday. In 2025, Tajikistan introduced an Open Skies policy that lifted many market restrictions as a way to encourage competition, with the aim of generating better prices for passengers, more efficient service, and route diversification. On August 9, Somon Air began direct flights every Sunday between Dushanbe and Jeddah, Saudi Arabia. In June, it also started a weekly direct route between the Tajik capital and Tbilisi, Georgia. In April, the airline introduced a new weekly route between Dushanbe and Ufa in western Russia. Operating since 2009, privately owned Somon Air says it is Tajikistan’s “national air carrier.”

Tajikistan Holds Talks on Fuel Imports from China

Tajikistan has begun negotiations with China on importing gasoline and diesel fuel as the country grapples with a sharp decline in fuel imports. Prices are rising, and filling stations in Dushanbe are experiencing diesel shortages. The two sides are discussing possible transport routes and which companies in Tajikistan would be authorized to import petroleum products. Tajikistan’s Ministry of Energy and Water Resources, cited by Asia-Plus, said Chinese fuel could be delivered directly through the Kulma border crossing or via Tajikistan’s northern neighbors. The volume and timing of any future deliveries have yet to be agreed, while pricing remains under discussion. Dushanbe is also negotiating increased fuel imports from other Central Asian countries and seeking supplies from Iraq. Agreements have already been reached with Iran on imports of petroleum products and crude oil, although implementation has been postponed because of the armed conflict in the region. Additional supplies from Kazakhstan were discussed during a meeting between President Emomali Rahmon and President Kassym-Jomart Tokayev in Astana on July 29. The talks included the possibility of increasing deliveries of petroleum products from Kazakhstan to the Tajik market. Kazakhstan’s presidential administration said the leaders discussed energy cooperation, along with trade and transport logistics. On July 10, Tajikistan’s Minister of Energy and Water Resources, Daler Juma, said the country had sufficient fuel reserves for approximately 60 days. He added that the government was negotiating with several countries in addition to Russia, which remains Tajikistan’s principal fuel supplier. Fuel imports into Tajikistan have fallen sharply over the past month. During the first half of the year, Russia accounted for 72.3% of all fuel supplied to the Tajik market, while domestic refineries produced only about 0.5% of total supply. The Times of Central Asia previously reported that disruptions in Russia’s fuel market had intensified competition for alternative fuel supplies across Central Asia and increased costs for the region’s most import-dependent economies.

Nearly Half of Young Women in Tajikistan Are Not Working or Studying, Survey Finds

New results from Tajikistan’s 2025 Labor Force Survey point to persistent structural weaknesses in the country’s labor market. Although the official unemployment rate remains relatively low, labor force participation is limited, particularly among women and young people. Of the country’s 6.87 million people aged 15–75, 3.02 million are in the labor force, producing a participation rate of 43.9%. The rate is 57.1% among men and 30.9% among women, a gap of 26.2 percentage points. The World Bank previously described Tajikistan’s labor force participation rate as the lowest in Central Asia. The official unemployment rate is 6.3%, but the survey’s expanded measure of labor underutilization presents a less favorable picture. This measure includes unemployed people and the potential labor force, as well as those experiencing time-related underemployment. On this basis, the rate rises to 11.7%. Among women, it approaches 14%. The survey also shows a gradual shift in where employed people live. The urban share of employment increased from 20% in 2004 to 28.4% in 2025, but 71.6% of employed people still live in rural areas. That figure demonstrates the rural concentration of employment, although it does not by itself show how many people work in agriculture. Separately, the World Bank estimates that agriculture employs more than 40% of Tajikistan’s labor force. The findings on young people are particularly stark. Among those aged 15–24, nearly 27% are not in education, employment or training (NEET). The rate is 40.1% among young women, compared with 13.2% among young men. The gender divide is even wider among those aged 15–29. In this group, 45% of women are neither employed nor pursuing education or training, compared with 12.4% of men. The figures suggest that Tajikistan’s main labor-market challenge is not fully captured by the conventional unemployment rate. People who are not working but are neither actively seeking employment nor immediately available to start work are generally not counted as unemployed. Low participation and high NEET rates therefore reveal pressures that the headline unemployment figure does not. Women and young people account for much of this unused labor potential. Expanding their access to employment will be especially important as the country’s working-age population grows. The World Bank estimates that about 600,000 young people will enter Tajikistan’s labor force over the coming decade and that the economy will need to generate approximately 1.4 million jobs during that period. It also describes the country’s economy as heavily dependent on the export of low-skilled labor and the remittances those workers send home. These concerns are reflected in the World Bank Group’s Country Partnership Framework for Tajikistan for fiscal years 2026–2032. The strategy prioritizes a better-skilled and healthier workforce, along with increased private investment. It also seeks to create more and better jobs and calls for measures to raise labor force participation, particularly among women and young people. In May, the World Bank approved the Tajikistan Women’s Economic Empowerment Project. The initiative is expected to create 3,450 jobs and help 850 women-owned or women-led businesses gain access to financial services. It...

The Central Asia Debt Divide: Why the Region’s Borrowing Risks Are Not the Same

Central Asia’s biggest debtor is not necessarily its most vulnerable. Kazakhstan accounts for roughly two-thirds of the region’s external liabilities, but much of that debt sits on corporate balance sheets rather than the government’s. Tajikistan owes a fraction of the amount, yet remains at high risk of debt distress. The contrast highlights the Central Asia debt divide. Kyrgyzstan and Tajikistan rely more heavily on sovereign and concessional borrowing, while Uzbekistan’s external liabilities are now split almost evenly between the public and corporate sectors. Based on the latest available figures from national authorities and international financial institutions, the combined external debt of Kazakhstan, Kyrgyzstan, Tajikistan, and Uzbekistan approached $275 billion in early 2026. Turkmenistan has not been included in the estimate because the country does not publish comprehensive official external debt statistics that can be directly compared with those of its regional neighbors. The total is an approximate calculation compiled from national statistics rather than a regional aggregate published by a single institution. The countries also release their debt data for different reporting dates and use different classifications, requiring caution when making direct comparisons. Total external debt includes obligations owed to non-residents by governments, central banks, commercial banks, private companies, and, in some countries, local subsidiaries of foreign corporations. Government external debt is a narrower measure covering liabilities that are directly serviced or guaranteed by the state. China remains an important bilateral creditor, particularly in Kyrgyzstan and Tajikistan, while multilateral institutions provide much of the region’s infrastructure and public-sector financing. Kyrgyzstan: Rising Debt, but a Broader Creditor Base Kyrgyzstan’s public debt has risen alongside increased infrastructure spending and domestic borrowing, although its creditor base has become more diversified. A smaller share is now owed to a single bilateral lender, while multilateral financing and the domestic securities market have grown in importance. According to the Kyrgyz Ministry of Finance’s public debt data, the country’s total public debt stood at approximately $8.94 billion as of May 31, 2026, including around $6.1 billion in external obligations. The debt debate has also become part of President Sadyr Japarov’s broader economic narrative. In an interview with the Kabar national news agency published on October 8, 2025, Japarov said his government was continuing to borrow but argued that new loans were being directed toward commercial projects expected to repay their own financing rather than place an additional burden on the state budget. He also said Kyrgyzstan intended to repay its older debts by 2035. The International Monetary Fund said in its 2026 Article IV consultation that Kyrgyzstan had recorded strong economic growth for a fourth consecutive year, giving the authorities an opportunity to strengthen fiscal buffers and accelerate structural reforms. It also warned that the outlook remained exposed to significant downside risks. Kazakhstan: A Large External Debt, but a Different Risk Profile Kazakhstan accounts for the largest share of Central Asia’s external debt, but its headline figure can be misleading. Unlike several of its neighbors, the country’s external liabilities are dominated by corporate and intercompany borrowing rather...