• KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00224
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
11 November 2026

Viewing results 1 - 6 of 27

Developer of Kazakhstan Tungsten Projects Drops Merger and Plans U.S. Listing

Cove Kaz, the U.S. company developing two major tungsten deposits in Kazakhstan, has dropped its planned merger with Skyline Builders. It now plans to list its shares directly on a U.S. stock exchange in the first half of 2027. The change comes alongside a $32 million investment commitment intended to fund work on the projects. Together, the announcements reshape how Cove Kaz plans to finance development and bring its Kazakhstan business to public investors. The companies announced the mutual termination of their merger agreement on November 2. American Ventures has committed to buying four million Cove Kaz shares at $8 each, implying a company valuation of $1.97 billion. The investment still needs to close. “The additional capital will fund engineering and construction-related work to shorten our time to production,” said Cove Kaz Executive Chairman Pini Althaus. Under its new listing plan, Cove Kaz intends to become a Delaware corporation and adopt the name Kaz Resources Inc. It also plans to bring other affiliated Kazakhstan assets into the company, subject to regulatory approval. The company has not named an exchange and plans to file a registration statement with U.S. securities regulators. Skyline would remain an investor under the revised arrangements. In its own announcement, it said its existing investment and outstanding loan would be exchanged for shares in Cove Kaz. Its stake would be approximately 26% after the new funding closes. Skyline said the revised arrangement should allow its shareholders to realize the value of their investment faster than the merger. The underlying mining venture centers on Northern Katpar and Upper Kairakty in Kazakhstan’s Karaganda Region. Cove Kaz acquired 70% of Severniy Katpar LLP, which holds the project licenses, in April. Kazakhstan’s national mining company, Tau-Ken Samruk, retains the remaining 30%. [caption id="attachment_59844" align="aligncenter" width="1774"] The Northern Katpar tungsten project site in Kazakhstan’s Karaganda Region. Image: Cove Kaz Capital Group.[/caption] The original merger agreement was intended to create a listed supplier of tungsten and other critical minerals for U.S. customers. Tungsten is used in industrial tools, aerospace and defense equipment, making alternative supplies important to Washington’s efforts to reduce dependence on China. Chinese companies already have a foothold in Kazakhstan’s tungsten sector. A $300 million processing plant opened in Almaty Region in November 2024, with Jiangxi Copper among its participants. Cove Kaz’s planned mine and refinery would establish another supply route, focused on U.S. customers. Work at Northern Katpar has moved into engineering and feasibility studies. Cove Kaz’s August update said the definitive feasibility study began in July and was expected to finish before the end of 2027. It covers the mine and a planned refinery in Kazakhstan that would produce ammonium paratungstate, a material used in tungsten manufacturing. The study will help establish the costs and design needed for a final investment decision. It will also support assessments by potential lenders, including U.S. government agencies. Cove Kaz has cited earlier studies indicating potential combined annual production of about 12,000 metric tons from the two deposits, equivalent to roughly 15% of...
Opinion: A Deeper Understanding of Transshipment

The White House recently issued a report on the transshipment of goods. It focuses on allegations that some countries with lower tariffs seek to evade U.S. tariffs on China by exporting goods that are really produced in China and only slightly modified, if at all, before further export to the U.S. The report groups more than 40 countries in what it terms a “shadow transshipment network” into three different categories based on how much it estimates the risk of transshipment and the integration of the economy into supply chains involving China. The first tier, mostly advanced countries, are larger economies where transshipment can show up in otherwise “broadly legitimate” trade. The second tier are a few larger developing countries, which have close links with the Chinese economy. The third tier the report terms “small, opportunistic Chinese targets” with “specific weak-link advantages” that increase transshipment risk. To be clear, transshipment is a risk in some economies. There is also legitimate transshipment (for instance, through normal supply chains and logistics channels) and illegal transshipment (where an exporter files a false certification as to the origin, character, or value of goods). False certifications are punishable by civil and criminal penalties in the U.S. and in most other countries. The World Customs Organization also has international standards on transshipment. So there are reasons to be vigilant about the risk of illegal transshipment. But to see why the report also misses the mark, consider the example of a country increasingly important to the U.S. with a fast-growing economy. To top it off, the country borders China. It’s Kazakhstan. First, the report is wrong to call Kazakhstan “small.” It’s 49th in the world by GDP – quite an accomplishment for a country which was formerly part of the Soviet Union. Second, to term Kazakhstan an “opportunistic Chinese target” is simply not accurate. There is strong trade and investment between China and Kazakhstan, as one would expect from large neighboring countries. And Kazakhstan, particularly at its Khorgos border cooperation center, plays a vital role in the rapidly growing Middle Corridor of trade between China and Europe. But this is legitimate transshipment of goods, and it is deeply unfair to suggest that Kazakhstan may not be fulfilling its duties. Let’s also not forget why the Middle Corridor is growing: because the West sought another route for Chinese goods after the Russian invasion of Ukraine made shipment through Russia impractical or subject to sanctions. Kazakhstan is a regional and even global leader in digitalization of both tax and Customs systems. The “smart border” policy is a success in facilitating legal trade while maintaining vigilance and security: in the first half of 2026, about 60% of declarations of goods were automatic, and 80% of transit declarations were completed without the need for Customs control forms. Deepening digital exchange protocols with regional partners including China, Uzbekistan, and Azerbaijan will speed legal trade even further. Digitalization builds honest systems, free from corruption – and by definition lowering the risk of transshipment. Kazakhstan...

Kazakhstan’s Warehouse Market Faces Mismatch Between Supply and Demand

Central Asia is seeking a larger role in trade between China and Europe by offering alternative shipping routes that bypass Russia. However, growing interest in transit has not been matched by balanced development of warehouse infrastructure. Some transport hubs face shortages of modern facilities, while others have vacant space. For international freight operators and retailers, this means additional costs. For investors, it raises the risk of financing warehouses that may struggle to attract tenants. These contradictions were discussed on October 15 in Almaty at the Central Asia Warehouse Summit 2026, organized by consulting firm IBC Global. The summit brought together industry representatives and investors. Research presented at the event showed a growing disconnect between warehouse construction and actual demand. Vacant Warehouses Exist, but Not Where They Are Needed According to IBC Global, the vacancy rate for modern warehouse space in Kazakhstan is about 5%. This gives tenants more options when choosing facilities and negotiating rents. However, the national figure masks significant differences between cities and types of warehouse space. Industry estimates put Astana's shortage of modern warehouse space at approximately 350,000–400,000 square meters. Separately, property consultancy Bright Rich reported that Almaty's warehouse vacancy rate had reached 13.3% in May 2026. These estimates come from different periods and surveys, and should not be treated as directly comparable. Class A warehouses are modern facilities with high ceilings, loading docks, security systems, and infrastructure designed to handle large volumes of goods. Kazakhstan's warehouse market is nevertheless expanding rapidly. According to an IBC Global ranking presented at the summit, the total area of Class A warehouses covered by its research increased by 39% over the past year to 730,000 square meters. More than half of that space, approximately 400,000 square meters, is controlled by the five largest property owners. Their facilities are concentrated mainly in Almaty and Almaty Region, Astana, and Shymkent. Developers Continue Building Despite Weaker Demand A survey of more than 100 warehouse market participants across four Central Asian countries revealed a gap between developers' plans and tenants' expectations. According to IBC Global, 81% of developers intend to launch new projects or complete facilities already under construction within the next twelve months. Yet 62% of developers surveyed identified weak tenant demand as the main obstacle to market development, while 52% cited the high cost and limited availability of financing. IBC Global's market sentiment index for Kazakhstan stood at 48.1 points in the third quarter of 2026, below the neutral threshold of 50. However, 52% of respondents expect supply and demand to move closer to equilibrium over the next year. The risks are particularly high for speculative developments launched without a tenant already under contract. Developers expect to secure customers after construction is completed, but by then business requirements and market rental rates may have changed. One alternative is the build-to-suit model, in which a facility is constructed to meet the requirements of a specific tenant. Its location, size, equipment, and operating conditions are agreed upon in advance. This reduces vacancy risk for...

South Korea Steps Up Central Asia Critical Minerals Push

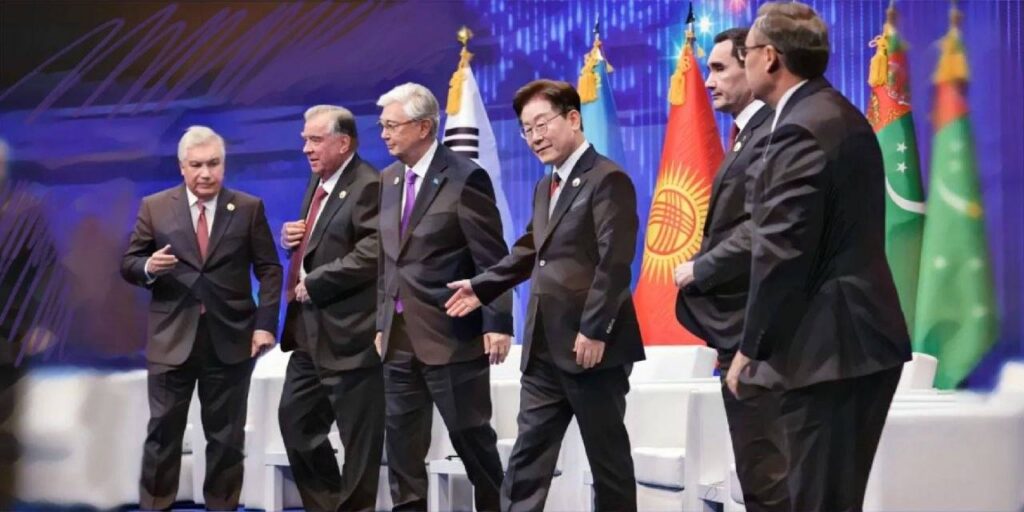
The first South Korea–Central Asia summit, held in Seoul on September 16, capped three days of bilateral meetings that produced more than 70 agreements and memorandums. The leaders agreed to meet every two years, a separate C5+1 forum for industry ministers was established, and critical minerals took a central place on the new agenda. The main question now is how many of those documents will translate into mines, processing plants, and long-term contracts. South Korea needs reliable supplies of metals for its automotive, electronics, battery, and energy industries. Central Asia wants to use that demand to develop domestic processing and reduce its reliance on raw material exports. Seoul proposed combining the region’s resources with its own exploration, mineral processing, and manufacturing technologies. President Lee Jae Myung spoke of cooperation across the production chain, from identifying deposits to manufacturing finished products. Rare metals centers being established at key locations in Central Asia are intended to support joint research and specialist training. Until now, South Korea has worked with the region’s countries largely through bilateral ties. The new C5+1 format adds a regional mechanism to those relationships. Kazakhstan will host the next summit in 2028. Kazakh financier and analyst Rasul Rysmambetov believes the value of the new format will depend on the region’s ability to secure tangible industrial results. He sees South Korea as an attractive partner because of its experience with rapid industrialization and its strengths in building industrial facilities. “The priority for Central Asia is to stop selling raw materials. We need to establish processing in the region. The heads of state’s visit to Seoul was highly productive. In fact, all summits in similar formats have been productive. The main question now is how to move away from exporting raw materials and toward joint industrialization,” Rysmambetov told The Times of Central Asia. Uzbekistan put forward a broader regional proposal. President Shavkat Mirziyoyev called for an investment alliance for critical minerals, with processing clusters bringing together exploration, mining, and the production of high-value goods. Uzbekistan and South Korea are already developing a joint rare metals center and have agreed to strengthen cooperation throughout the production chain. Kazakhstan offered Korean businesses a broader package covering rare metals, nuclear and clean energy, and artificial intelligence. Urban development was also part of the talks, including the Alatau Smart City project near Almaty. The countries upgraded their ties to a comprehensive strategic partnership and signed a memorandum on the peaceful use of nuclear energy. The energy agreements also cover conventional resources. In April, South Korea said it had secured 18 million barrels of Kazakh crude oil. In Kyrgyzstan, Korean organizations are working with their Kyrgyz counterparts to identify possible antimony and tungsten projects and strengthen exploration capacity. Tajikistan is also offering cooperation on antimony, as well as precious metals, building on the first Korea–Tajikistan Minerals Forum, which took place in August. The minerals agenda is complemented by Korean willingness to invest in transport and infrastructure. South Korea and Uzbekistan agreed to expand Korean participation in...

Middle Corridor Freight Grows, but Eastbound Cargo Lags

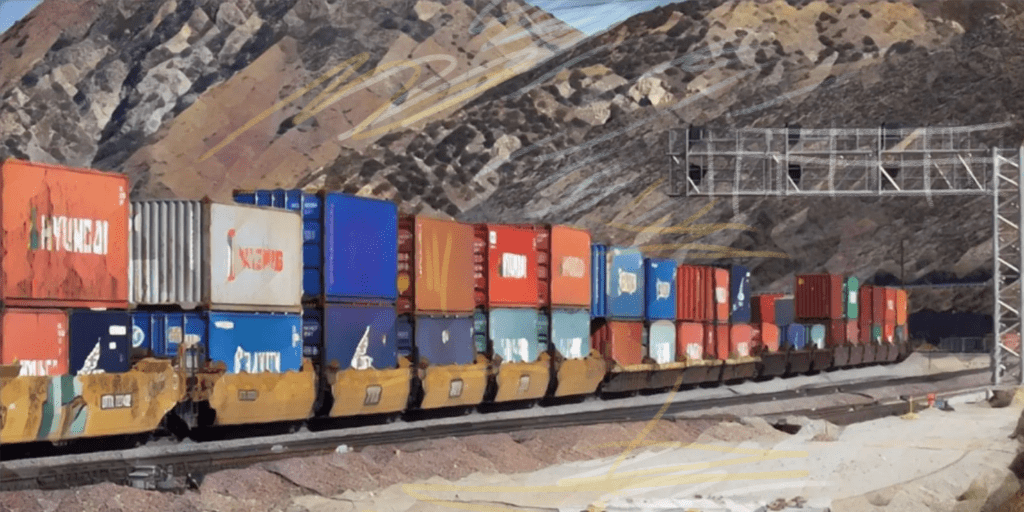
Container traffic is growing along the Middle Corridor from China and Central Asia toward Europe, but the route is far less busy in the opposite direction. In the first eight months of 2026, about 80% of container traffic moved westward and only 20% eastward. Operators are now looking for goods in Europe and Türkiye that can be shipped back across the Caspian Sea and Kazakhstan toward Central Asia and China. Container traffic totaled 53,574 TEU along the Trans-Caspian International Transport Route, also known as the Middle Corridor, in January–August. One TEU is equivalent to a standard 20-foot container. During the same period last year, the figure was 48,326 TEU, meaning traffic increased by 11%. But the flows were highly uneven. According to ADY Express, 42,642 TEU moved from east to west, compared with just 10,932 TEU in the opposite direction – a ratio of almost four to one. Interest in the route increased sharply after 2022, when companies began looking for additional ways to move goods between China and Europe without transiting Russia. Over the past several years, participants in the Middle Corridor have focused on increasing shipments from China. New train services have been introduced, while countries along the route have invested in railways, terminals, and Caspian ports. Chinese freight has grown, but there is still not enough cargo for the return journey. For transport operators, the issue comes down to finances. Once containers reach Europe, they need to be used again or repositioned. If there is cargo for the return journey, the equipment generates revenue in both directions. Without it, operators can face the cost of moving empty equipment. The 80%-to-20% split, however, does not establish how many containers actually make the return journey without cargo. Railway companies themselves are now acknowledging the shortage of eastbound cargo. “For this, backhaul freight is necessary,” Emil Mammadov, Adviser to the Chairman of Azerbaijan Railways, said at the Black Sea and Caspian Freight Forum 2026 in Baku. According to Mammadov, attracting cargo from Europe would help increase freight volumes, optimize transportation costs, and allow at least some containers to be returned to their countries of origin. Until now, the route has been promoted more actively in China, Kazakhstan, Azerbaijan, Georgia, and Türkiye. European companies have received less attention. Railway operators are now looking for customers at the western end of the corridor as well. A shipment from Türkiye showed what such a return journey could look like. In May, KTZ Express and Pasifik Eurasia dispatched a train from Izmir to China carrying household refrigerators. Fifty 40-foot containers crossed the Caspian Sea, traveled through Kazakhstan, and continued into China via the Altynkol border station. For now, such shipments remain limited. The Chinese side continues to push for more westbound traffic. On September 9, Azerbaijan Railways held talks with Shanghai International Port Group and Lianyungang Port on expanding shipments of Chinese goods through Kazakhstan, across the Caspian, and through Azerbaijan toward Europe. ADY Express also reported that 265 container block trains operated along...

What Building Central Asian Supply Chains Taught Me About AI

I took over spare-parts supply at BPK Auto in Ust-Kamenogorsk in the mid-2000s, at the age of 25, moving from selling cars. The company was the general dealer for VAZ in Kazakhstan, assembled Niva models in the city, and was taking on Skoda, Chevrolet, and Kia while building service centers across the country to meet the expectations of those brands for a dealer. My job was to keep parts flowing to all of it. Several thousand vehicles came through in a month, and a single car contains something like 50,000 separate part numbers. The service teams wanted as many of those as possible sitting on the shelves. From where they stood, that made sense, because they were judged on whether a mechanic could start a repair the same day, whether a customer complained, and an ISO audit was running over the service operation at the same time. From the procurement side, the arithmetic looked different. Some parts cost two or three thousand dollars and were fitted once or twice a year, and holding them across four model lines tied up a large share of the company's working capital. I built the forecast in spreadsheets and checked it against actual sales once the month closed in 1C. To run it, I needed the service side's own records: how many vehicles of each type they had seen, and what had been repaired. I asked for them for months. They would not release them. Some of that was habit; a warehouse full of everything being what a well-run operation had looked like for the previous 40 years. More of it sat in how the two departments were counted. My result was recorded the moment the parts moved into the service center. Theirs was recorded much later, when the car left the workshop. Nobody was measured by the number that would have made the forecast work. The forecasting was the straightforward part of that job. The difficult part was building an operation in which people shared the information behind the forecast and were expected to act on its findings. Why a Better Model Would Not Have Changed the Outcome Put one of today's AI demand-forecasting systems into that same warehouse and very little changes. The forecast would be far better than anything I produced by hand. It would still depend on service records that nobody was willing to release, and where records did exist, it would be reading entries written up at the end of a long shift. It could not grant the purchasing manager authority to reorder against it, nor could it alter the measures by which the service department was judged. Better intelligence does not repair the path between operational data and operational action. Every party you add to that path lengthens it. A distribution network across Kazakhstan and Kyrgyzstan can run from a manufacturer to over 45,000 small retail outlets, served through more than 18 distribution centers, with 1,391 field staff taking and checking orders on the ground. An order begins...