• KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
  • KZT/USD = 0.00221
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29760
26 October 2026

Viewing results 49 - 54 of 117

Opinion: Afghanistan and Central Asia – Security Without Illusions

Over the past year, Afghanistan has become neither markedly more stable nor dramatically more dangerous, despite how it is often portrayed in public discourse. There has been neither the collapse that many feared, nor the breakthrough that some had hoped for. Instead, a relatively unchanged but fragile status quo has persisted, one that Central Asian countries confront daily. For the C5 countries, Afghanistan is increasingly less a topic of speculative discussion and more a persistent factor in their immediate reality. It is no longer just an object of foreign policy, but a constant variable impacting security, trade, humanitarian issues, and regional stability. As such, many of last year’s forecasts have become outdated, based as they were on assumptions of dramatic change, whereas the reality has proven far more inertial. Illusion #1: Afghanistan Can Be Ignored The belief that Afghanistan can be temporarily “put on the back burner” is rooted in the assumption that a lack of public dialogue or political statements equates to a lack of interaction. But the actions of Central Asian states show that ignoring Afghanistan is not a viable option, even when countries intentionally avoid politicizing relations. Turkmenistan offers a clear example. Ashgabat has maintained stable trade, economic, and infrastructure ties with Afghanistan for years, all with minimal foreign policy rhetoric. Energy supplies, cross-border trade, and logistical cooperation have continued despite political and financial constraints, and regardless of international debates over the legitimacy of the Afghan authorities. This quiet pragmatism stands in contrast to both isolationist strategies and symbolic or ideological engagement. Turkmenistan may avoid making public declarations about its relationship with Afghanistan, but it nonetheless maintains robust cooperation. This calculated calmness reduces risks without signaling disengagement. Importantly, this approach does not eliminate structural asymmetries or deeper vulnerabilities. But it dispels the illusion that distancing reduces risk. On the contrary, sustained economic and logistical ties foster predictability, without which attempts to “ignore” a neighboring country become a form of strategic blindness. In this sense, Turkmenistan’s experience affirms a broader regional truth: Afghanistan cannot be removed from Central Asia’s geopolitical equation by simply looking away. It must be engaged pragmatically or dealt with later, in potentially more destabilizing forms. Illusion #2: Security Is Achieved Through Isolation Closely related to the first is the illusion that security can be ensured by building walls. Security in Afghanistan, and in the broader Afghan-Pakistani zone, is often seen as an external issue, something that can be kept out by sealing borders or minimizing engagement. Yet in practice, security is determined less by geography and more by the nature of involvement. This is reflected in the recent decision by Uzbekistan and Kazakhstan to participate in U.S. President Donald Trump's “Board of Peace” initiative. While the initiative focuses on resolving crises outside Central Asia, both countries have framed their participation as essential to their own national and regional security interests. As Abdulaziz Kamilov, advisor to the President of Uzbekistan, explained, Tashkent’s involvement stems from three factors: its own security needs, its foreign policy principles,...

Breaking into Project Vault: A U.S. Role for Central Asia’s Strategic Minerals

The Trump Administration has decided to go head-to-head with Beijing to secure an independent supply chain for critical minerals and insulate U.S. industries from supply shocks. Among many initiatives, the United States launched Project Vault on February 2 to establish a U.S. Strategic Critical Minerals Reserve. The public-private stockpile is expected to secure essential minerals and metals for U.S. national security purposes and high-technology industries. The effort formalizes the U.S. strategy to diversify critical mineral supply chains away from rival China and, in the process, harness broader global capacity. As part of this effort, mineral-rich Central Asia is already factoring heavily in U.S. foreign and economic policy thinking. Participating in the front row of the 2026 Critical Minerals Summit, Kazakhstan and Uzbekistan were invited to engage in Washington’s global effort to build resilient global supply chains. But Project Vault is a critical and separate component of the administration’s focus. Formally approved by the Export-Import Bank of the United States (EXIM) on February 2, Project Vault will be backed with up to $10 billion in long-term financing and an additional $2 billion in private sector participation. In sites across the country, the initiative will establish stores of critical minerals and rare earth elements essential for aerospace, defense, semiconductors, advanced manufacturing, renewables, and electric vehicles. The stockpile’s structure will be operated as a public-private partnership that enables manufacturers, trading firms, and private capital providers to jointly participate. Rare earths, copper, lithium, titanium, scandium, gallium, and germanium are all key minerals highlighted by the U.S. Department of the Interior that underpin modern technologies and demonstrate U.S. vulnerability to supply chain disruptions. Why a Strategic Mineral Reserve? The initiative is a direct response to perceived risks posed by China’s relative control of global critical mineral supply chains and markets, as well as Beijing’s use of trade restrictions, protectionism, and the weaponization of access to certain critical minerals. China controls a commanding share of the mining, refining, and processing of rare earths and related materials. Due to years of strategic planning and investment, Beijing has leveraged state subsidies and pricing controls to develop and secure between 80%-100% of rare earth processing capacities that have dominated international markets and disincentivized competitors for decades. Past export controls and export-license restrictions imposed by Beijing have underscored how critical mineral supply can become a tool of geopolitical leverage. China has at times restricted rare earth exports to Japan, Sweden and the United States in what is defined by many as supply-chain protectionism. Such actions can disrupt U.S. production for industries that rely on stable supplies to manufacture semiconductors, defense systems, and clean energy technologies. Project Vault is, therefore, conceived not merely as a reserve but as a mechanism to stabilize U.S. markets, to reduce reliance on China, and to signal a long-term commitment to diversified supply chains. Much like the U.S. Strategic Petroleum Reserve acts to cushion energy price shocks, the mineral reserve is expected to serve as a similar buffer. Operational and Financial Dimensions Project Vault’s financing model expects a...

Opinion – Qosh Tepa Canal: Transboundary Impacts Without a Transboundary Mechanism

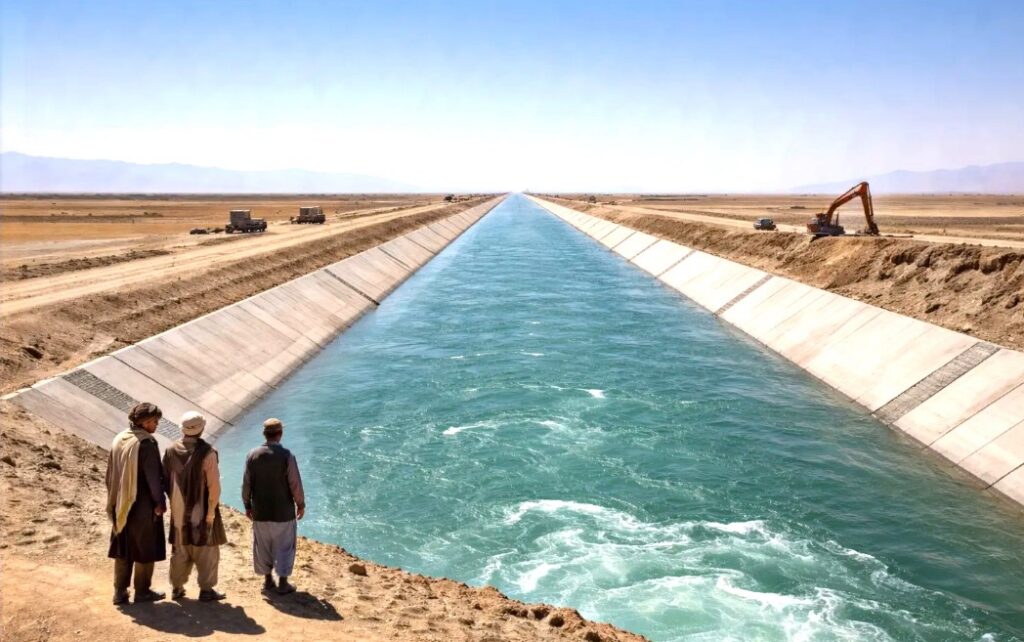
In recent months, media attention has increasingly focused on infrastructure projects underway in Afghanistan. Chief among them is the Qosh Tepa Canal, widely seen not only as an irrigation initiative but as a development with significant transboundary implications for the Amu Darya River basin. The canal draws water from one of Central Asia’s most critical transboundary rivers. For downstream countries, primarily Uzbekistan and Turkmenistan, the Amu Darya is a vital water source, directly linked to agricultural output and the sustainability of rural communities. As such, the conversation surrounding Qosh Tepa extends well beyond Afghanistan’s domestic agenda. Concerns voiced by experts and analysts stem from both the scale of the project and the absence of an inclusive, basin-wide mechanism that includes Afghanistan, which is not a party to the main post-Soviet Amu Darya allocation frameworks. As a result, discussions regarding the canal’s potential impacts are taking place largely outside formal multilateral frameworks. One positive development is the increasing presentation of Qosh Tepa within a broader context, where water flow management is recognized as a factor shaping regional political and economic relations. However, these assessments often highlight not the canal’s stated purpose, but rather the absence of a sustainable mechanism for coordinating discussion of its cross-border effects. [caption id="attachment_43173" align="aligncenter" width="1280"] Image: TCATCA[/caption] A recurring concern among experts is the lack of a structured multilateral platform that enables early-stage evaluation of such projects before they are perceived as risks. Infrastructure development in the region frequently outpaces the establishment of mechanisms for joint impact assessment and management. In this light, Kazakhstan’s initiative to establish a specialized structure within the UN system, the International Water Organization, acquires particular relevance. This proposal is not about building a theoretical global agenda but about addressing a specific institutional gap: the lack of a neutral forum for technical and expert discussion of transboundary water projects at an early stage. The Qosh Tepa Canal, currently a unilateral infrastructure undertaking rather than the result of an international agreement, could serve as a test case for such a preventive mandate. While the project is already underway and its transboundary implications are actively being discussed among experts, it has not yet escalated into a regional dispute. This creates an opportunity for professional dialogue, without entanglement in political or status-related debates. The present situation can be summarized as one of “transboundary implications without a transboundary mechanism.” The project, while entirely within Afghan territory, objectively affects the interests of downstream states, yet it remains disconnected from any multilateral framework for consultation or agreement. Is it in Afghanistan’s interest to engage in multilateral formats? Though the question is often left unanswered, the answer is a clear “yes.” Such engagement would help dispel suspicion not only among Central Asian states, but also in Iran and Pakistan, both of which have voiced concerns over shared water resources. First, it would reduce negative external rhetoric. Currently, Qosh Tepa is largely discussed via external media with alarmist scenarios and with little to no Afghan participation. This reinforces the image...

Opinion: Central Asia–Japan Summit Signals Shift in Eurasian Geoeconomics — and Russia’s Waning Role

In December 2025, Tokyo hosted the first leaders-level Central Asia + Japan summit — a watershed moment for Eurasian diplomacy that quietly reshapes the region’s strategic architecture. The declaration adopted at the summit lays out a clear economic-geostrategic vision: Japan is no longer a peripheral partner, but a central engine of multi-vector engagement with Central Asia. In the process, it exposes a growing gap in Russia’s regional influence — not because of rhetoric, but because of substance. Japan’s Agenda: Economy, Connectivity, Human Capital The Tokyo Declaration pivots on three pragmatic pillars that align tightly with Central Asian development priorities: Green growth and sustainability - decarbonization, energy security, and climate resilience; Connectivity - transport, logistics, customs facilitation, and digital corridors; Human resource development - education, training, exchanges, and technology transfer. This is not diplomatic abstraction. It reflects Japan’s long-term model of engagement: concessional finance, technology cooperation, and capacity building rather than quick geopolitical wins. In practical terms, there is now a numerical investment target - a combined public-private cooperation envelope of three trillion yen (approximately $20 billion) over five years -marking a shift from consultative dialogue to project delivery at scale. Importantly, the summit also reinforced cooperation in emerging domains such as artificial intelligence, digital transformation, and resilient supply chains - areas where Central Asia aims to leap ahead rather than merely catch up. This underscores how cooperation is being framed: not as charity, but as co-production of future-oriented infrastructure and capabilities. The significance of the summit lies not only in the declaration itself, but in the trajectory it has set for Japan–Central Asia engagement in the months ahead. What This Means for Russia: Substance Trumps Symbolism At first glance, Russia’s absence from explicit mention in the declaration may seem benign; after all, engagement with external partners often requires diplomatic balance. Yet silence in this case is meaningful. For decades, Russia’s influence in Central Asia was rooted in security ties, historical institutions, and energy networks. These were powerful structural levers in the twentieth century, but they are increasingly less relevant in an era defined by diversified markets and technological competition. The Tokyo summit highlights several structural realities: Russia does not offer a comparable economic agenda, particularly in green technologies, digital infrastructure, or human capital development. Russia’s model remains reactive, centered on existing corridors and legacy links rather than on new corridors of integration connecting Central Asia with Asian and European value chains. Russia is overweighted in traditional domains such as security and media presence, yet underweighted in economic agency suited to the twenty-first century. By contrast, Japan’s approach addresses precisely the gaps Central Asian states prioritize: employment, logistics, energy transition, and technological self-sufficiency. Even more strikingly, this shift is occurring without anti-Russian rhetoric. The summit was framed as an exercise in cooperation and development, not rivalry. Nevertheless, the outcomes effectively relegate Russia to the background — a clear indicator of the structural erosion of Moscow’s regional primacy. Multi-Vector Policy in Practice: Central Asia’s Agency For Central Asian states, the Tokyo summit...

Opinion: Is Uzbekistan Importing a Future Crisis?

Once hidden from the view of international investors, Uzbekistan is rapidly rewriting its economic narrative. Over the past eight years, the nation attracted over $113 billion in foreign investment, drawing financial firms and mutual funds eager to seize the momentum of Tashkent’s trade liberalization and its ambition to double GDP by 2030. And rightly so; 40% of the country’s population, which is the largest in Central Asia, is under the age of 25, while its gold production is within the top ten globally. Uzbekistan is in its breakout moment. With Uzbek bonds receiving a further upgrade to a BB rating from both Fitch and S&P Global, comparisons to Vietnam or Indonesia no longer seem aspirational. However, the question remains: Is Uzbekistan ready to set foot on the financial global stage, and, more importantly, is it structurally equipped to stay there? Amidst its sweeping economic transformation, IMF officials have warned the administration to remain vigilant against economic shocks beyond its control: volatile commodity prices, contractions in foreign investor liquidity, and consequently, tighter external financing. These warnings are not theoretical. They come from decades of IMF experience with financial crises in other emerging markets, such as the Latin American debt crises in the 1980s, the “Tequila Crisis” in 1994, and the “Asian Flu” in 1997. In those historic cases, newly liberalized economies suffered not because they lacked growth, but because they lacked a defense against the liquidity cycle. The economic reality is that global capital flows are often driven by decisions made in New York or London, not Tashkent. This economic phenomenon is often explained by the “liquidity model,” which argues that changes in exogenous liquidity conditions - driven by the economic situation of investor countries - shape capital flows into emerging markets. Thus, without sufficient financial market depth, emerging capital markets cannot absorb external shocks. And when global liquidity tightens, these flows can abruptly reverse, resulting in prolonged economic instability and loss of monetary sovereignty. The sequence unfolds as follows: capital inflows surge and balance-sheet vulnerabilities quietly build up; then an external shock - such as a monetary tightening in the creditor economy - causes inflows to slow; the local currency depreciates; and a feedback spiral of declining confidence and weakening balance sheets pushes the economy into crisis. Currency loses trust, struggles to recover, and money flees. Some initial signs of this pattern can be observed in Uzbekistan’s current boom. The economy is increasingly reliant on foreign borrowing: external debt as a share of GDP rose from 24.7% in 2017 to 61.4% in 2024, reaching $78.5 billion by June 2025. According to CEIC benchmarks, this level is already comparable to Poland’s 51.8% and Malaysia’s 69.9%, and now exceeds Kazakhstan’s 59.2%, reflecting growing dependence on financing from the World Bank, Eurobond investors, and major East Asian institutions. High debt levels alone do not necessarily imply instability. They can reflect efforts to accelerate domestic development. The real source of fragility in past crises was not the volume of debt but its denomination. When...

Opinion: Central Asia Is Consolidating Its Role as a Full-Fledged Actor in Global Processes

The seventh Consultative Meeting of the Heads of State of Central Asia, held in Tashkent, was far more than a routine regional gathering. It marked a pivotal moment with the potential to shape the political and economic architecture of the region for the next decade or two. President Shavkat Mirziyoyev’s keynote address stood out for articulating a forward-looking and comprehensive strategic vision. Notably, he proposed redefining the format itself from a loose “consultative mechanism” into a more cohesive and institutionalized “Central Asian Community.” At the summit, leaders endorsed several landmark documents: the Concept for Regional Security and Stability in Central Asia, the Catalogue of Threats to Central Asia’s Security and measures for their prevention for 2026-2028 and its implementation plan, a joint appeal supporting the Kyrgyz Republic’s candidacy for the UN Security Council, and the decision to admit Azerbaijan as a full-fledged participant. Taken together, these steps signal that Central Asia increasingly sees itself not as a passive bystander amid global geopolitical turbulence, but as an emerging regional actor capable of shaping its own trajectory. Two broader trends deserve special emphasis. First, the region is moving beyond reactive engagement with external initiatives and power blocs. Rather than relying solely on structures created by outside actors, Central Asia is beginning to develop its own institutions. This shift mirrors a global pattern: as the international order becomes more fragmented and unpredictable, regional communities are strengthening their internal mechanisms as a means of resilience. Second, the format envisioned in Tashkent diverges from “Brussels-style integration.” It does not require the transfer or dilution of sovereignty. Instead, it relies on soft integration, consultation, consensus-building, and phased convergence. As President Mirziyoyev noted, having a shared and realistic sense of “what we want our region to look like in 10-20 years” is essential. Without such a vision, Central Asia risks remaining the object of great-power competition rather than an autonomous participant in it. One of the summit’s most consequential developments was the decision to welcome Azerbaijan as a full-fledged member of the format. The emerging political and economic bridge between Central Asia and the South Caucasus is quickly becoming not only a transit nexus but also a cornerstone of a broader geopolitical space. The strengthening of Trans-Caspian corridors, the advancement of the “China – Kyrgyzstan – Uzbekistan” railway, the Trans-Afghan corridor, and the alignment of Caspian Sea transport routes will significantly expand the region’s strategic and economic potential. A further nuance is worth highlighting: Azerbaijan’s long-standing ties with the Western political and security architecture, through NATO partnership mechanisms and energy corridors, as well as its membership in the Organization of Turkic States, introduce new layers of connectivity. Its inclusion repositions the “Central Asian Community” from a post-Soviet platform into a wider geopolitical constellation spanning Eurasia, the South Caucasus, and the Middle East. For Central Asian states, this new configuration opens additional room for multi-vector diplomacy and reduces the risks of unilateral dependence.   The views expressed in this article are those of the author and do not...