• KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10820
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
09 October 2026

Viewing results 13 - 18 of 182

Opinion: Why Central Asia Cannot Afford to Abandon the Iranian Route

Kazakhstan had barely secured a foothold in Iran’s largest commercial port when renewed military escalation made the southern route risky again. The problem for Central Asia is that Iran is more than a trading partner. For a region without direct access to the open sea, it provides one of the few overland routes to the Persian Gulf and the Indian Ocean. On June 28, Kazakhstan and Iran signed a 27-year build-operate-transfer (BOT) agreement for a Kazakh transport and logistics terminal at Shahid Rajaee Port in Bandar Abbas. The agreement allocates two years for construction and the following 25 for operation. Astana expects the terminal to provide more direct access to markets in the Gulf, South and Southeast Asia, and East Africa. The project almost immediately found itself in a different reality. In July, U.S. strikes hit Iranian railway and coastal infrastructure. The Aq Taqeh Khan bridge on a rail route connecting Iran with Turkmenistan and, further north, with Kazakhstan, was damaged. There was no confirmed halt to Central Asian freight traffic, but military risk was no longer an abstract concern for carriers. That risk has now been compounded by a new U.S. sanctions campaign. On August 24, U.S. Treasury Secretary Scott Bessent launched what Washington calls Operation Economic Outcast, combining direct sanctions with pressure on Iran’s foreign economic partners. The United States said it would set timelines for other countries to shut down economic activity with Iran, while the scope of secondary sanctions was expanded to cover five areas: digital assets, technology, gold, aviation, and shipping. Nearly 60 Iran-linked individuals, entities, and vessels were also sanctioned. The United States has not publicly identified which countries could face penalties first. War and sanctions can make the Iranian route more expensive, slower, and more dangerous. They cannot change geography. Iran gives Central Asia overland access to ports on the Persian Gulf and Gulf of Oman. From Bandar Abbas and Chabahar, cargo can move onward toward India, the Gulf states, and East Africa. Iran also provides a western overland route toward Turkey. This is one of the fundamental differences between the Iranian route and the Middle Corridor, which crosses the Caspian Sea before continuing through Azerbaijan, Georgia, and Turkey. The Middle Corridor requires cargo to move between rail and maritime transport. Iran offers the possibility of a continuous overland chain while also providing access to ports connected to the Indian Ocean. For Kazakhstan, the southern route is already more than a plan. Trade with Iran increased by 26.4% in 2025 to $430.2 million. Freight traffic along the International North-South Transport Corridor reached 3.5 million tons, while rail traffic between Kazakhstan and Iran increased by 69%. It is this expanding transport network that is now exposed to greater military and sanctions risks. There is another factor. A free trade agreement between Iran and the Eurasian Economic Union, which includes Kazakhstan and Kyrgyzstan, entered into force on May 15, 2025. It significantly reduced tariff barriers to trade in goods between the two sides. Uzbekistan offers...
What Building Central Asian Supply Chains Taught Me About AI

I took over spare-parts supply at BPK Auto in Ust-Kamenogorsk in the mid-2000s, at the age of 25, moving from selling cars. The company was the general dealer for VAZ in Kazakhstan, assembled Niva models in the city, and was taking on Skoda, Chevrolet, and Kia while building service centers across the country to meet the expectations of those brands for a dealer. My job was to keep parts flowing to all of it. Several thousand vehicles came through in a month, and a single car contains something like 50,000 separate part numbers. The service teams wanted as many of those as possible sitting on the shelves. From where they stood, that made sense, because they were judged on whether a mechanic could start a repair the same day, whether a customer complained, and an ISO audit was running over the service operation at the same time. From the procurement side, the arithmetic looked different. Some parts cost two or three thousand dollars and were fitted once or twice a year, and holding them across four model lines tied up a large share of the company's working capital. I built the forecast in spreadsheets and checked it against actual sales once the month closed in 1C. To run it, I needed the service side's own records: how many vehicles of each type they had seen, and what had been repaired. I asked for them for months. They would not release them. Some of that was habit; a warehouse full of everything being what a well-run operation had looked like for the previous 40 years. More of it sat in how the two departments were counted. My result was recorded the moment the parts moved into the service center. Theirs was recorded much later, when the car left the workshop. Nobody was measured by the number that would have made the forecast work. The forecasting was the straightforward part of that job. The difficult part was building an operation in which people shared the information behind the forecast and were expected to act on its findings. Why a Better Model Would Not Have Changed the Outcome Put one of today's AI demand-forecasting systems into that same warehouse and very little changes. The forecast would be far better than anything I produced by hand. It would still depend on service records that nobody was willing to release, and where records did exist, it would be reading entries written up at the end of a long shift. It could not grant the purchasing manager authority to reorder against it, nor could it alter the measures by which the service department was judged. Better intelligence does not repair the path between operational data and operational action. Every party you add to that path lengthens it. A distribution network across Kazakhstan and Kyrgyzstan can run from a manufacturer to over 45,000 small retail outlets, served through more than 18 distribution centers, with 1,391 field staff taking and checking orders on the ground. An order begins...

Opinion: Kazakhstan Energy Expansion May Not Guarantee a Lasting Surplus

Kazakhstan plans to commission 13.3 GW of power capacity by the end of 2029, including 12.56 GW of entirely new generation, in a build-out the government says will move the country from deficit to sustained surplus. But new industrial projects and large data centers could absorb part of that margin almost as soon as it appears. According to Energy Ministry projections, Kazakhstan expects to eliminate its electricity deficit by the end of the first quarter of 2027 and move to a sustained surplus by 2029. The projected electricity balance for 2029 calls for generation of 162.1 billion kWh against consumption of 144.5 billion kWh, leaving a surplus of 17.6 billion kWh. However, it is difficult to predict exactly how much electricity the country will need three years from now. Therefore the forecast "surplus" will not necessarily become a reserve available for future industrial projects. Energy Hungry Data Centers Kazakhstan is pursuing a swathe of new energy-intensive industrial projects, while data centers are emerging as another major source of electricity demand. The Data Center Valley project is being developed in Ekibastuz, where the government says 300 MW of power capacity has already been secured, with plans to expand to 1 GW. It cites competitive electricity costs and the ability to scale up as advantages of the location. At full scale, such a cluster would itself become a major electricity consumer. If it drew 1 GW continuously, it would consume about 8.76 billion kWh a year – roughly half the projected national surplus for 2029. Kazakhstan’s digital ambitions already extend beyond a single data center. In June, the government announced $10 billion in agreements with U.S.-based Firebird and NVIDIA to build a large AI computing center using 100,000 advanced computer chips. The project will form part of the Data Center Valley initiative. By the end of 2029, Kazakhstan plans to commission 13.3 GW of capacity, of which 12.56 GW will come from entirely new generating facilities and 0.74 GW will replace existing capacity. According to the Energy Ministry, 7.4 GW of the total will be baseload generation and another 5.9 GW will come from renewable energy sources. The full 13.3 GW cannot be treated as spare power for new factories and data centers. Some will be needed to meet rising demand and make the electricity system more reliable. Solar and wind power also cannot produce at full capacity all the time. This is particularly important during periods of peak demand, when the power system must cope simultaneously with high consumption and possible maintenance or outages at generating facilities. A projected annual surplus measured in billions of kilowatt-hours and the amount of capacity available during a particular peak hour are therefore different measures. Upkeep of Current Power Sources The condition of existing generation remains a separate problem. Much of Kazakhstan’s thermal generation is aging and requires modernization. The Energy Ministry reported that 411 billion tenge was allocated to the 2025 repair campaign, during which 10 power units, 63 boilers, and 39 turbines were repaired. It said...

Kazakhstan’s Mineral Future Still Carries an Oil Risk Premium

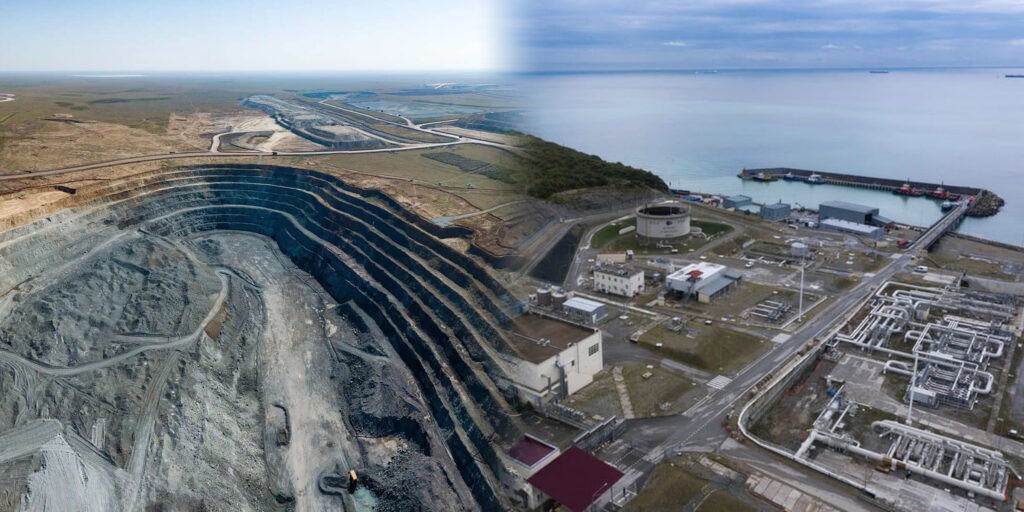
In June, President Kassym-Jomart Tokayev went to Brussels with a future-facing offer: Kazakhstan could become Europe’s non-Chinese option in critical minerals. Astana presented the country as a base for processing, long-term offtake, and industrial cooperation, rather than another source of ore. A month later, Kazakhstan’s older vulnerability reappeared. Drone attacks near the Caspian Pipeline Consortium terminal at Novorossiysk disrupted loadings and forced production cuts in Kazakhstan. By July 27, loading had resumed, with tankers receiving crude supplied by Tengizchevroil. The interruption was brief, but it exposed a structural problem. Kazakhstan’s future mineral offer still rests on an economy whose main export artery runs through Russia and the Black Sea. That is the central tension in Kazakhstan’s new resource diplomacy. Astana wants Europe to help build a future supply chain. Its present still depends on an oil corridor it does not fully control. Kazakhstan is asking Europe to make future demand bankable. A mineral deposit does not become part of a European supply chain when officials announce it in a joint statement. It needs geological confirmation, financing, processing technology, reliable power, water, logistics, and customers prepared to sign contracts years before the first shipment. This is why offtake sits at the heart of Tokayev’s proposal. Long-term purchase commitments can turn European concern over Chinese dominance into financeable projects. If Europe wants another source tomorrow, it must help fund extraction, processing, and internationally accepted standards today. Kazakhstan says it is ready to supply 21 of the 34 materials on the EU’s critical raw materials list. It also wants more of the value chain to remain at home. European capital and technology would support local processing, laboratories, skills, and higher-value production instead of simply moving raw materials abroad. Europe has good reason to listen. China dominates the processing of many minerals used in batteries, advanced manufacturing, digital infrastructure, and defence. European industry wants alternatives, but diversification cannot be improvised after a supply shock. Mines and processing plants take years to finance, permit, construct, and qualify. For Kazakhstan, the minerals offer is also an attempt to upgrade an older relationship. Western companies already know the country through Tengiz, Kashagan, and decades of oil investment. Astana now wants to move from extraction towards processing and a stronger position in industrial supply chains. But the old oil story still prices the new minerals story. The CPC episode showed why. The pipeline carries crude from Tengiz, Kashagan, and Karachaganak through Russian territory to Novorossiysk. It handles more than 80% of Kazakhstan’s oil exports and ties much of the country’s hard-currency income to a route outside Astana’s full control. A short halt was enough to cut output sharply at fields more than 1,500 kilometres away. Tokayev’s call in Omsk to freeze the war in Ukraine should be read partly in that context. It reflected more than the diplomatic caution expected from a neighbour of Russia. The war is now touching Kazakhstan’s export system through tanker security, insurance risk, production schedules, and investor confidence. Astana wants European finance for...

Kazakhstan AI Infrastructure: Can It Become a Regional Hub?

Computing infrastructure for artificial intelligence has joined fossil fuel reserves and transport corridors on the list of the world's most valuable strategic assets. The United States, Gulf states, and China are investing tens of billions of dollars in vast data-center projects. Kazakhstan has also joined the race, developing computing capacity with an eye on neighboring markets. For a country traditionally associated with commodity exports, the idea may seem unexpected. Yet the modern AI economy requires vast computing resources, specialized processors, reliable data centers, and, above all, large amounts of electricity. The AI market is therefore creating revenue opportunities not only for those who develop models, but also for countries able to provide the conditions in which they operate. From Digitalization to Infrastructure In 2024, Kazakhstan ranked among the world’s top 25 countries for e-government development and was also among the 10 countries with the broadest public access to government services. The focus of state digital policy is now shifting. Kazakhstan has begun investing more in the infrastructure needed for artificial intelligence. In 2025, the state-owned Samruk-Kazyna fund and the UAE-based company Presight AI developed a national supercomputing cluster. The project placed Kazakhstan 86th in the global ranking of countries operating the world’s most powerful computing systems. This year, the government announced a partnership with NVIDIA and Firebird to develop high-performance computing infrastructure and build modern data centers. A national AI ecosystem is also being developed around Astana Hub, while telecommunications and cloud companies are expanding their own data-processing facilities. Digitalization in Kazakhstan was previously focused mainly on the delivery of public services. The country is now building infrastructure that can be used by research institutions, businesses, and government agencies. At sufficient scale, it could serve not only the domestic market but also users elsewhere in Central Asia. Factors Working in Kazakhstan’s Favor If Kazakhstan intends to enter the regional market, an obvious question arises: what can it offer data-center operators and cloud-service providers? The country’s relatively modest domestic market is not the decisive factor. For such projects, the cost and reliability of electricity, the quality of digital infrastructure, international connectivity, and conditions for long-term investment matter far more. Kazakhstan lies between Europe and Asia and is gradually becoming part of new transregional digital routes, including the Trans-Caspian fiber-optic link. For cloud-service providers, this could mean lower data-transfer latency and easier access to customers in several countries. The Astana International Financial Centre also offers foreign investors a legal framework based on English common law, reducing uncertainty for long-term infrastructure projects. Electricity prices are another important factor. They remain competitive compared with many neighboring countries, while energy is one of the largest operating costs for modern data centers. Kazakhstan’s geography, digital connectivity, investment framework, and energy resources together give it a chance to become a regional location for computing infrastructure. Not Algorithms but Megawatts Artificial intelligence is often associated with software, algorithms, and increasingly sophisticated language models. In reality, AI has become just as much an infrastructure business. Training and operating systems...

Opinion: Could Vanadium Be Kazakhstan’s Next Breakout Critical Metals Story?

Vanadium is viewed as a critical mineral by the United States, the European Union, Russia, China and many other countries because of its importance to energy storage and industrial alloys. At the Astana Metals & Metallurgy (AMM) Congress, Ferro-Alloy Resources CEO Nicholas Bridgen discussed the company’s assets, strategy, and valuation with The Times of Central Asia, noting that the company appears undervalued amid supply chain disruptions and the rising strategic importance of vanadium. The discussion highlighted vanadium’s emerging demand-supply imbalance and efforts to better align market perception with fundamentals. Of the critical metals that will define the next half-century, vanadium has perhaps the strongest claim to indispensability: it hardens the steel in our infrastructure and defense systems, and it stores the energy that our grids will increasingly depend on. Yet the market has consistently failed to price that future in, and nowhere is that mispricing more visible than in the vanadium deposits of Kazakhstan. In 1941, with the Second World War raging, Soviet geologists fanned out across Central Asia looking for strategic minerals. Around 180 kilometers east of Almaty, in the foothills of the Tian Shan mountain range along the borders with China and Kyrgyzstan, they found tungsten at the Boguty deposit. At roughly the same time, they were delineating what would become the Northern Katpar and Upper Kairakty tungsten deposits. The geology was well understood, and the resource was real, but nothing happened for the better part of 75 years. The deposits sat idle not because tungsten was unimportant, but because there was no pressing reason for, first, the Soviet Union or later the West to develop them. That changed when the scale of China's dominance in critical metals became impossible to ignore. By the early 2020s, China was producing over 75% of the world’s tungsten output, alongside similarly dominant shares of rare earth elements and a range of other strategic minerals. This concentration of supply was not accidental. It was the product of decades of deliberate industrial policy, patient capital, and a willingness to operate at low margins long enough to drive out competitors. The Tungsten Lesson Chinese mining company Jiaxin International Resources Investment Ltd. moved in 2014 to acquire Boguty for an undisclosed sum, almost certainly a modest one. The deal further consolidated China’s grip on global tungsten supply. Jiaxin then spent approximately $300 million developing the deposit and listed on the Hong Kong Stock Exchange at a valuation in excess of $600 million. The investment thesis seemed straightforward enough at the time. In 2025, it looked positively prescient: China imposed export controls on tungsten, and key prices outside China more than doubled. According to the Financial Times, Jiaxin’s market capitalization stands at close to HKD 22.3 billion, equal to $2.84 billion, approximately 9.5 times the stated development expenditure. [caption id="attachment_52262" align="aligncenter" width="1432"] Image: Kaz Resources[/caption] Meanwhile, Skyline Builders Group Holding Ltd. and Cove Kaz Capital Group LLC (“Cove Kaz”) have moved to acquire the two other formerly dormant tungsten deposits in Kazakhstan, Northern Katpar and Upper Kairakty. On this...