• KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
21 September 2026

Viewing results 7 - 12 of 174

Opinion: Kazakhstan Energy Expansion May Not Guarantee a Lasting Surplus

Kazakhstan plans to commission 13.3 GW of power capacity by the end of 2029, including 12.56 GW of entirely new generation, in a build-out the government says will move the country from deficit to sustained surplus. But new industrial projects and large data centers could absorb part of that margin almost as soon as it appears. According to Energy Ministry projections, Kazakhstan expects to eliminate its electricity deficit by the end of the first quarter of 2027 and move to a sustained surplus by 2029. The projected electricity balance for 2029 calls for generation of 162.1 billion kWh against consumption of 144.5 billion kWh, leaving a surplus of 17.6 billion kWh. However, it is difficult to predict exactly how much electricity the country will need three years from now. Therefore the forecast "surplus" will not necessarily become a reserve available for future industrial projects. Energy Hungry Data Centers Kazakhstan is pursuing a swathe of new energy-intensive industrial projects, while data centers are emerging as another major source of electricity demand. The Data Center Valley project is being developed in Ekibastuz, where the government says 300 MW of power capacity has already been secured, with plans to expand to 1 GW. It cites competitive electricity costs and the ability to scale up as advantages of the location. At full scale, such a cluster would itself become a major electricity consumer. If it drew 1 GW continuously, it would consume about 8.76 billion kWh a year – roughly half the projected national surplus for 2029. Kazakhstan’s digital ambitions already extend beyond a single data center. In June, the government announced $10 billion in agreements with U.S.-based Firebird and NVIDIA to build a large AI computing center using 100,000 advanced computer chips. The project will form part of the Data Center Valley initiative. By the end of 2029, Kazakhstan plans to commission 13.3 GW of capacity, of which 12.56 GW will come from entirely new generating facilities and 0.74 GW will replace existing capacity. According to the Energy Ministry, 7.4 GW of the total will be baseload generation and another 5.9 GW will come from renewable energy sources. The full 13.3 GW cannot be treated as spare power for new factories and data centers. Some will be needed to meet rising demand and make the electricity system more reliable. Solar and wind power also cannot produce at full capacity all the time. This is particularly important during periods of peak demand, when the power system must cope simultaneously with high consumption and possible maintenance or outages at generating facilities. A projected annual surplus measured in billions of kilowatt-hours and the amount of capacity available during a particular peak hour are therefore different measures. Upkeep of Current Power Sources The condition of existing generation remains a separate problem. Much of Kazakhstan’s thermal generation is aging and requires modernization. The Energy Ministry reported that 411 billion tenge was allocated to the 2025 repair campaign, during which 10 power units, 63 boilers, and 39 turbines were repaired. It said...
Kazakhstan’s Mineral Future Still Carries an Oil Risk Premium

In June, President Kassym-Jomart Tokayev went to Brussels with a future-facing offer: Kazakhstan could become Europe’s non-Chinese option in critical minerals. Astana presented the country as a base for processing, long-term offtake, and industrial cooperation, rather than another source of ore. A month later, Kazakhstan’s older vulnerability reappeared. Drone attacks near the Caspian Pipeline Consortium terminal at Novorossiysk disrupted loadings and forced production cuts in Kazakhstan. By July 27, loading had resumed, with tankers receiving crude supplied by Tengizchevroil. The interruption was brief, but it exposed a structural problem. Kazakhstan’s future mineral offer still rests on an economy whose main export artery runs through Russia and the Black Sea. That is the central tension in Kazakhstan’s new resource diplomacy. Astana wants Europe to help build a future supply chain. Its present still depends on an oil corridor it does not fully control. Kazakhstan is asking Europe to make future demand bankable. A mineral deposit does not become part of a European supply chain when officials announce it in a joint statement. It needs geological confirmation, financing, processing technology, reliable power, water, logistics, and customers prepared to sign contracts years before the first shipment. This is why offtake sits at the heart of Tokayev’s proposal. Long-term purchase commitments can turn European concern over Chinese dominance into financeable projects. If Europe wants another source tomorrow, it must help fund extraction, processing, and internationally accepted standards today. Kazakhstan says it is ready to supply 21 of the 34 materials on the EU’s critical raw materials list. It also wants more of the value chain to remain at home. European capital and technology would support local processing, laboratories, skills, and higher-value production instead of simply moving raw materials abroad. Europe has good reason to listen. China dominates the processing of many minerals used in batteries, advanced manufacturing, digital infrastructure, and defence. European industry wants alternatives, but diversification cannot be improvised after a supply shock. Mines and processing plants take years to finance, permit, construct, and qualify. For Kazakhstan, the minerals offer is also an attempt to upgrade an older relationship. Western companies already know the country through Tengiz, Kashagan, and decades of oil investment. Astana now wants to move from extraction towards processing and a stronger position in industrial supply chains. But the old oil story still prices the new minerals story. The CPC episode showed why. The pipeline carries crude from Tengiz, Kashagan, and Karachaganak through Russian territory to Novorossiysk. It handles more than 80% of Kazakhstan’s oil exports and ties much of the country’s hard-currency income to a route outside Astana’s full control. A short halt was enough to cut output sharply at fields more than 1,500 kilometres away. Tokayev’s call in Omsk to freeze the war in Ukraine should be read partly in that context. It reflected more than the diplomatic caution expected from a neighbour of Russia. The war is now touching Kazakhstan’s export system through tanker security, insurance risk, production schedules, and investor confidence. Astana wants European finance for...

Kazakhstan AI Infrastructure: Can It Become a Regional Hub?

Computing infrastructure for artificial intelligence has joined fossil fuel reserves and transport corridors on the list of the world's most valuable strategic assets. The United States, Gulf states, and China are investing tens of billions of dollars in vast data-center projects. Kazakhstan has also joined the race, developing computing capacity with an eye on neighboring markets. For a country traditionally associated with commodity exports, the idea may seem unexpected. Yet the modern AI economy requires vast computing resources, specialized processors, reliable data centers, and, above all, large amounts of electricity. The AI market is therefore creating revenue opportunities not only for those who develop models, but also for countries able to provide the conditions in which they operate. From Digitalization to Infrastructure In 2024, Kazakhstan ranked among the world’s top 25 countries for e-government development and was also among the 10 countries with the broadest public access to government services. The focus of state digital policy is now shifting. Kazakhstan has begun investing more in the infrastructure needed for artificial intelligence. In 2025, the state-owned Samruk-Kazyna fund and the UAE-based company Presight AI developed a national supercomputing cluster. The project placed Kazakhstan 86th in the global ranking of countries operating the world’s most powerful computing systems. This year, the government announced a partnership with NVIDIA and Firebird to develop high-performance computing infrastructure and build modern data centers. A national AI ecosystem is also being developed around Astana Hub, while telecommunications and cloud companies are expanding their own data-processing facilities. Digitalization in Kazakhstan was previously focused mainly on the delivery of public services. The country is now building infrastructure that can be used by research institutions, businesses, and government agencies. At sufficient scale, it could serve not only the domestic market but also users elsewhere in Central Asia. Factors Working in Kazakhstan’s Favor If Kazakhstan intends to enter the regional market, an obvious question arises: what can it offer data-center operators and cloud-service providers? The country’s relatively modest domestic market is not the decisive factor. For such projects, the cost and reliability of electricity, the quality of digital infrastructure, international connectivity, and conditions for long-term investment matter far more. Kazakhstan lies between Europe and Asia and is gradually becoming part of new transregional digital routes, including the Trans-Caspian fiber-optic link. For cloud-service providers, this could mean lower data-transfer latency and easier access to customers in several countries. The Astana International Financial Centre also offers foreign investors a legal framework based on English common law, reducing uncertainty for long-term infrastructure projects. Electricity prices are another important factor. They remain competitive compared with many neighboring countries, while energy is one of the largest operating costs for modern data centers. Kazakhstan’s geography, digital connectivity, investment framework, and energy resources together give it a chance to become a regional location for computing infrastructure. Not Algorithms but Megawatts Artificial intelligence is often associated with software, algorithms, and increasingly sophisticated language models. In reality, AI has become just as much an infrastructure business. Training and operating systems...

Opinion: Could Vanadium Be Kazakhstan’s Next Breakout Critical Metals Story?

Vanadium is viewed as a critical mineral by the United States, the European Union, Russia, China and many other countries because of its importance to energy storage and industrial alloys. At the Astana Metals & Metallurgy (AMM) Congress, Ferro-Alloy Resources CEO Nicholas Bridgen discussed the company’s assets, strategy, and valuation with The Times of Central Asia, noting that the company appears undervalued amid supply chain disruptions and the rising strategic importance of vanadium. The discussion highlighted vanadium’s emerging demand-supply imbalance and efforts to better align market perception with fundamentals. Of the critical metals that will define the next half-century, vanadium has perhaps the strongest claim to indispensability: it hardens the steel in our infrastructure and defense systems, and it stores the energy that our grids will increasingly depend on. Yet the market has consistently failed to price that future in, and nowhere is that mispricing more visible than in the vanadium deposits of Kazakhstan. In 1941, with the Second World War raging, Soviet geologists fanned out across Central Asia looking for strategic minerals. Around 180 kilometers east of Almaty, in the foothills of the Tian Shan mountain range along the borders with China and Kyrgyzstan, they found tungsten at the Boguty deposit. At roughly the same time, they were delineating what would become the Northern Katpar and Upper Kairakty tungsten deposits. The geology was well understood, and the resource was real, but nothing happened for the better part of 75 years. The deposits sat idle not because tungsten was unimportant, but because there was no pressing reason for, first, the Soviet Union or later the West to develop them. That changed when the scale of China's dominance in critical metals became impossible to ignore. By the early 2020s, China was producing over 75% of the world’s tungsten output, alongside similarly dominant shares of rare earth elements and a range of other strategic minerals. This concentration of supply was not accidental. It was the product of decades of deliberate industrial policy, patient capital, and a willingness to operate at low margins long enough to drive out competitors. The Tungsten Lesson Chinese mining company Jiaxin International Resources Investment Ltd. moved in 2014 to acquire Boguty for an undisclosed sum, almost certainly a modest one. The deal further consolidated China’s grip on global tungsten supply. Jiaxin then spent approximately $300 million developing the deposit and listed on the Hong Kong Stock Exchange at a valuation in excess of $600 million. The investment thesis seemed straightforward enough at the time. In 2025, it looked positively prescient: China imposed export controls on tungsten, and key prices outside China more than doubled. According to the Financial Times, Jiaxin’s market capitalization stands at close to HKD 22.3 billion, equal to $2.84 billion, approximately 9.5 times the stated development expenditure. [caption id="attachment_52262" align="aligncenter" width="1432"] Image: Kaz Resources[/caption] Meanwhile, Skyline Builders Group Holding Ltd. and Cove Kaz Capital Group LLC (“Cove Kaz”) have moved to acquire the two other formerly dormant tungsten deposits in Kazakhstan, Northern Katpar and Upper Kairakty. On this...

Opinion: Kazakhstan’s Demining Expertise Could Provide Boost to Afghanistan

According to the United Nations Office for the Coordination of Humanitarian Affairs (OCHA), Afghanistan remains one of the most heavily mined countries in the world. During the first five months of 2026 alone, 175 people were killed or injured by landmines and unexploded ordnance, with children accounting for approximately 75% of the victims. Behind these figures lies a daily reality of fear: farmers cannot safely cultivate their fields, children cannot walk to school without risk, and road construction equipment cannot reach critical transport routes. In practice, this continues to hinder the development of the entire region. Mine-contaminated land prevents the recovery of agriculture, blocks the construction of roads, complicates the return of displaced populations, and significantly increases the cost of infrastructure projects. According to the Landmine and Cluster Munition Monitor, Afghanistan ranks among the world’s most heavily mined territories, alongside Bosnia and Herzegovina, Cambodia, Ethiopia, Iraq, and Ukraine.  A Barrier to Central and South Asian Integration For Kazakhstan and the other countries of Central Asia, this issue also carries  strategic significance. Without stability in Afghanistan, the implementation of Eurasian transport projects and the expansion of trade links with South Asia become increasingly difficult. Globally, humanitarian demining is no longer viewed simply as a charitable activity. Today, it represents the starting point of any major infrastructure project. Railways cannot be laid, nor can high-voltage transmission lines be built, where the ground itself remains hostile to human activity. Virtually every prospective transport corridor connecting Central Asia with ports on the Indian Ocean passes through Afghan territory, including major projects such as the development of the Trans-Afghan Corridor and the CASA-1000 project electricity project. International experience demonstrates that humanitarian demining in Cambodia, Bosnia and Herzegovina, Croatia, and Azerbaijan created the conditions for economic recovery, the return of displaced populations, and the attraction of foreign investment. From Kazbat’s Experience to a New Humanitarian Mission Unlike most countries in the region, Kazakhstan possesses substantial practical experience in conducting mine-clearance operations. Between 2003 and 2008, Kazakhstan’s military engineering unit, Kazbat, participated in the international mission in Iraq, destroying approximately 4.5 million explosive devices. Initially, Kazakh sappers cleared residential neighborhoods and agricultural land of unexploded ordnance. Later, they expanded their operations to locating and destroying underground and above-ground weapons depots abandoned after the conflict. These operations prevented millions of rounds of ammunition from falling into the hands of terrorist organizations. The mission came at a cost. In January 2005, 29-year-old Captain Kairat Kudabayev was killed when munitions detonated during preparations for disposal, while several other Kazakh servicemen were injured. Kazakh specialists also supplied local communities with purified drinking water and provided medical assistance, demonstrating a comprehensive approach to post-conflict recovery. More than 5,000 Iraqi civilians received medical treatment, while approximately 7,000 cubic meters of drinking water were purified. The expertise Kazakhstan accumulated could now evolve into a civilian-focused mission centered on protecting civilian populations and supporting Afghanistan’s long-term economic recovery. How a New Regional Platform Could Operate Kazakhstan’s international development agency, KazAID, could serve as the national...

Karakabak Silk Road Finds Reveal Ancient Trade Links

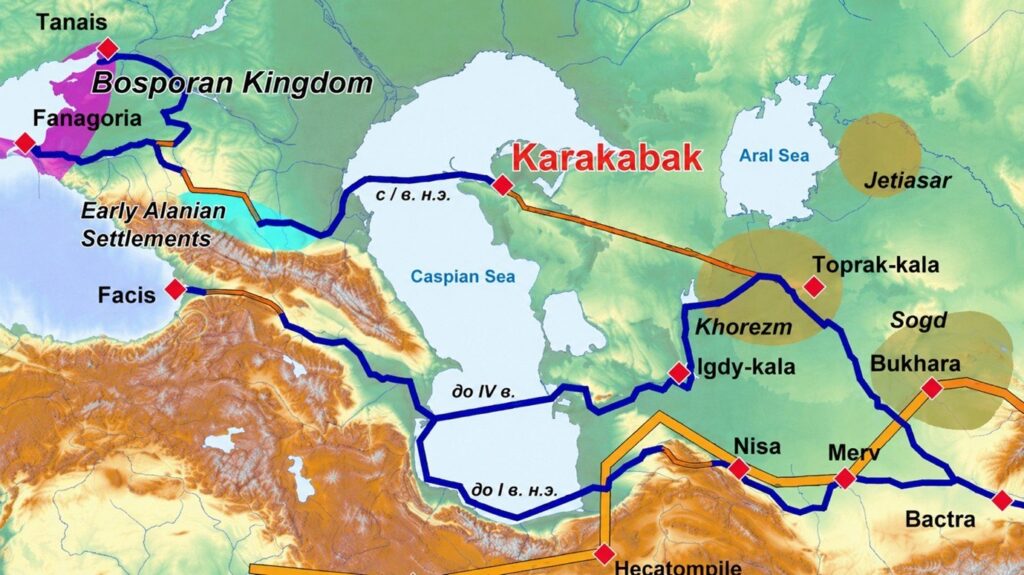
In 568, the Sogdian diplomat Maniakh led an embassy from the Turkic Khagan Istemi to the court of Byzantine Emperor Justin II. The mission sought to negotiate direct silk trade with the Byzantines and an alliance against Sasanian Iran, which controlled the principal overland routes between Central Asia and Byzantium. Historians have traditionally associated this diplomatic mission with the development of direct commercial and diplomatic links along the northern routes of the Silk Road. However, archaeological research conducted over the past decade in Mangystau, western Kazakhstan, has opened new perspectives on the study of ancient trade networks and offers a fresh interpretation of this long-held assumption. One of the most significant recent discoveries is the ancient settlement of Karakabak, located on the shore of Kochak Bay along the northeastern coast of the Caspian Sea. Preliminary evidence suggests that the settlement existed from the first century CE until the middle of the sixth century. The settlement likely emerged alongside the development of local mineral resources, including the extraction and processing of copper, iron, lead, and bitumen. Craftsmen at Karakabak produced jewelry, ceremonial and everyday belt fittings, clothing, weapons, horse harnesses, and saddles. Silver, gold, garnets, amber, lapis lazuli, carnelian, red coral, and pearls were imported for jewelry making and processed at the site. [caption id="attachment_51864" align="aligncenter" width="602"] Image: Andrey Astafyev[/caption] The settlement also produced a wide range of ceramic vessels, some of which were distributed well beyond the region. Glass beads and cullet were imported from across the Caspian Sea to support local glassworking. This provides compelling evidence that Karakabak was integrated into international economic networks during antiquity. Glass found at the site included material originating in both the Roman Empire and Iran. Taken together, the archaeological evidence allows Karakabak to be interpreted as a major manufacturing and processing center that participated in extensive interregional exchange networks serving the nomadic world. Archaeologists have recovered a substantial collection of more than 150 coins dating from the first century through the first half of the sixth century CE. The collection includes coins from Parthia, Ancient Khorezm, Bukhara Sogdiana, Sasanian Iran, the Kushano-Sasanian Kingdom, the Byzantine Empire, and China. [caption id="attachment_51866" align="aligncenter" width="1379"] Image: Andrey Astafyev[/caption] Research has established that Karakabak maintained commercial ties with the Zhetyasar culture in the lower Syr Darya region of present-day Kyzylorda Region, the Kerder culture in the Amu Darya delta, Sasanian Iran, Caucasian Albania, the North Caucasus, the Azov region, the Lower and Middle Volga, and the Southern Urals. This demonstrates the settlement’s high commercial and economic status. In terms of its role within international trade networks, Karakabak may be compared to the modern Port of Aktau on the Caspian Sea. The discovery of an entire enclave-type archaeological complex centered on Karakabak represents a unique archaeological phenomenon in southwestern Kazakhstan. It also requires a reassessment of the site’s place and role within the transport infrastructure of the Great Silk Road. Evidence of economic ties with the Zhetyasar culture, together with the discovery of Parthian coins, suggests that alongside...