• KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
20 September 2026

Viewing results 1 - 6 of 1604

Kazakhstan Mining Royalty System Delayed Until 2029

Kazakhstan plans to delay a new mining royalty system until 2029, postponing a reform that would tax raw ore more heavily than metals processed inside the country. The government backed the two-year delay, saying parts of the system still need further work. The royalty regime would apply only to new mining licenses issued from 2027 onward for areas where mining rights have not previously been granted. For example, a company receiving a new license to develop a previously unlicensed copper deposit would come under the royalty system, while an existing copper mine would continue paying the current mineral extraction tax, or MET. The main difference is when and how the tax is calculated. Under MET, tax is charged on minerals extracted from the ground. Under the proposed royalty system, the payment would instead be linked to the sale of the mineral product. This approach is more closely tied to actual sales. More significantly, the tax rate would fall as the mineral is processed further. The Tax Code sets a rate of 13% for ore, 10% for concentrate, and 7% for metals. A miner selling raw ore would therefore face almost twice the royalty rate of a company producing metal, giving businesses an incentive to process more of their output in Kazakhstan. Putting the system into practice has proved more difficult. The government says it still needs to decide how royalties should be calculated on minerals recovered from old tailings and other mining waste, and how the rules should treat expensive new projects and valuable minerals produced alongside a mine’s main commodity. The proposed rules will be tested against mining companies’ financial models before they take effect. The Finance Ministry had previously raised concerns about a rapid transition to royalties. In 2024, the State Revenue Committee estimated that applying rates similar to those used in Western Australia could reduce annual budget revenue by about KZT 270 billion ($606 million), while extending royalties to all subsoil users could result in losses of about KZT 450 billion ($1.01 billion). Those estimates do not apply directly to the much narrower reform now planned, which covers only future licenses in areas where subsoil use rights had not previously been granted. They do, however, help explain the government’s caution over changes to subsoil taxation. The State Revenue Committee says tax payments from more than 7,000 subsoil users, including oil and gas producers, account for around 35% of Kazakhstan’s republican budget revenue. The postponement therefore leaves the main structure of the reform intact but gives the government another two years to decide how it will work in practice. The Times of Central Asia previously examined the arguments surrounding the reform and Kazakhstan’s effort to link mining taxation with greater domestic processing.
Kazakhstan’s Shin-Line Group Plans Food Industry Cluster With South Korean Support

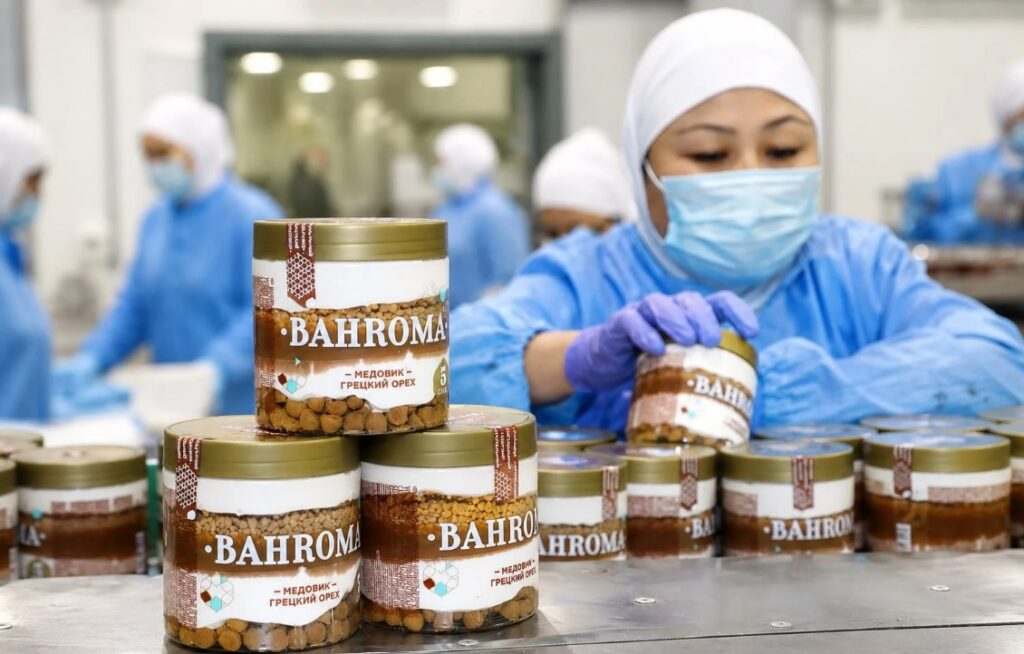
Kazakhstan’s Shin-Line Group, a food manufacturer best known as Central Asia’s largest ice cream producer, plans to establish a food industry cluster modeled on South Korea’s Foodpolis. Korean specialists will help develop its management model and services for producers seeking to enter overseas markets. Under the agreement, the Korean side will provide consulting and expert support on the cluster’s management and development strategy. Kazakhstan’s Ministry of Agriculture describes it as the country’s first project of its kind. Foodpolis operates in the South Korean city of Iksan. The cluster brings food manufacturers and research laboratories together with centers that help businesses develop and test products. The centers also assist with certification and access to overseas buyers. Shin-Line intends to adapt this system to Kazakhstan’s market. “It is important for us to create not just a standalone site, but an entire ecosystem where producers can access technology and expertise, develop processing, and enter new markets. This is a long-term project, and we are starting by studying and adapting the best Korean experience,” Shin-Line Group President Andrey Shin said in a statement released by Kazakhstan’s Ministry of Agriculture. Shin-Line makes instant noodles and frozen prepared foods in addition to ice cream. Its total production reached 37,000 metric tons in 2025, the company reported. Kazakhstan’s Ministry of Agriculture said Shin-Line exported about 14,200 metric tons of ice cream that year, generating more than $49 million in export revenue and accounting for up to 95% of Kazakhstan’s ice cream exports. Its exports reach ten countries, including Central Asian states, China, Mongolia, and markets in the Caucasus. Korean companies also hope to use Shin-Line’s distribution network to enter Kazakhstan’s market. The two sides discussed placing Foodpolis products in approximately 70 CU convenience stores operating in Kazakhstan. This could give the companies a ready-made route into Kazakhstan’s retail market and, eventually, other Central Asian markets. The agreement continues a series of Asian partnerships for Shin-Line. In September, the company established a joint venture with Japan’s Shigemitsu Industry to develop the Ajisen Ramen chain. The partners plan to open up to 50 restaurants in Kazakhstan and other Eurasian countries between 2027 and 2031. A central kitchen will be established at Shin-Line’s facility in the Almaty Region to supply the network. Kazakhstan aims to increase the share of processed goods in its agricultural exports. In 2025, exports from its agricultural and food-processing sector generated $7 billion, up 37% from the previous year. Processed products accounted for about $3.6 billion. Expanding exports, however, depends on more than production volumes. Businesses also need help developing and certifying products, as well as access to retail networks. Shin-Line wants to bring these functions together in the future cluster.

South Korea’s YPP Considers $2 Billion Green Ammonia Project in Kazakhstan

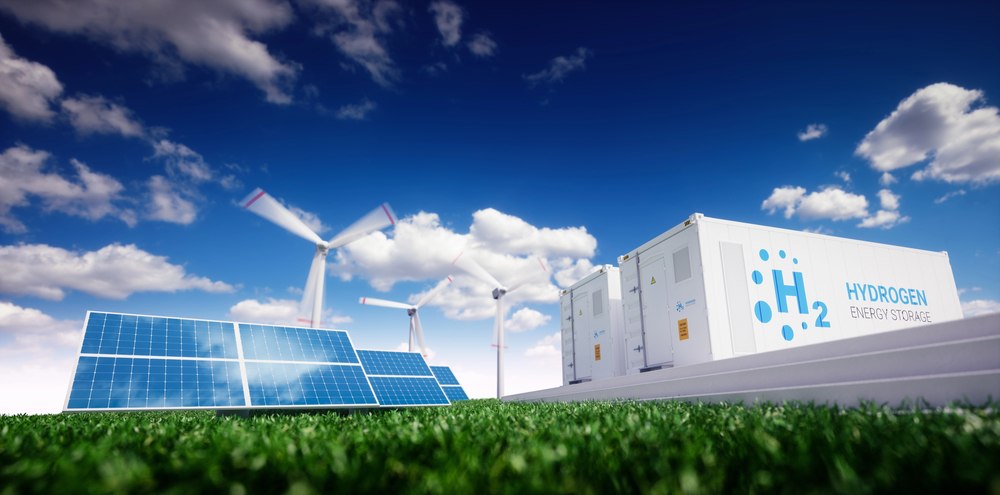
South Korea’s YPP Corporation is considering building a green hydrogen and ammonia complex in the East Kazakhstan Region at an estimated cost of $2 billion. The project, outlined in a memorandum signed during President Kassym-Jomart Tokayev’s visit to South Korea, could produce up to 55,000 metric tons of green hydrogen or 310,000 metric tons of green ammonia annually. Green ammonia is made by combining nitrogen with hydrogen produced using renewable electricity. Most ammonia is currently used to make fertilizer, but it is also being developed as a low-carbon fuel and as a way of transporting hydrogen, which is more difficult and expensive to move over long distances in its pure form. For South Korea, which depends heavily on imported energy, ammonia is part of a wider effort to reduce emissions from power generation and industry. Its latest electricity plan envisages clean hydrogen and ammonia supplying 6.2% of electricity generation by 2038. Kazakhstan’s Ministry of Energy, the regional authorities, and YPP signed a memorandum covering cooperation on the Green Energy Complex project. It envisages around 1 GW of renewable generation, including wind and solar power. The Ministry of Energy says the project would proceed if it proves economically viable. YPP, a South Korean energy engineering company, signed a framework agreement with Kazakh Invest to develop the Green Energy Complex in July 2025. The project was initially conceived on a larger scale. A 2025 proposal envisaged investment of up to $3.1 billion and 2 GW of renewable power, with annual hydrogen production of as much as 75,000 metric tons. Under the latest version, the estimated cost is about $2 billion, with renewable capacity of around 1 GW. Hydrogen production is now projected at up to 55,000 metric tons a year, while planned ammonia production remains unchanged at up to 310,000 metric tons. Kazakhstan has some obvious attractions for such a project: ample space for large renewable-energy developments and an established industrial base. East Kazakhstan is one of the country’s main metallurgical and power-producing regions. It also contains a significant share of Kazakhstan’s water resources, an important consideration because producing green hydrogen by electrolysis requires both electricity and water. The harder question is whether Kazakhstan can turn those advantages into ammonia that is competitive on international markets. Green ammonia remains substantially more expensive to produce than conventional ammonia. The International Energy Agency estimated in 2025 that ammonia made using electrolysis cost about three times as much on average before policy support and carbon pricing were taken into account. Competition for Asian buyers is also growing. Samsung C&T, which was named in 2025 as a potential buyer for the project in Kazakhstan, signed a binding 15-year agreement with India’s Reliance Industries in March 2026 for green ammonia produced in India. The deal is worth more than $3 billion, with supplies due to begin in the second half of fiscal year 2029. Kazakhstan also faces a geographical disadvantage. The country is landlocked, and ammonia produced in East Kazakhstan for South Korea or other overseas markets...

Kazakhstan’s Jewelry Market Faces New Rules on Gold and Hallmarking

Kazakhstan produces and exports billions of dollars’ worth of gold, yet officially recorded domestic jewelry production amounted to just $7.2 million in 2025. The government now plans to tackle the gray areas of the market, from the origin of gold used by workshops to scrap from pawnshops and mandatory hallmarking of jewelry. According to the Ministry of Industry and Construction, the domestic jewelry market was worth about $168 million last year, up 3.4% from 2024. But market participants say that a significant share of trade in precious metals and jewelry remains outside the formal economy. The contrast is particularly striking given Kazakhstan’s position as a major gold producer and exporter. According to international trade statistics for 2025, Switzerland imported more than $1.1 billion worth of unwrought and semi-manufactured gold from Kazakhstan, the United Kingdom about $561 million, and Azerbaijan about $262 million. Together, those three destinations alone accounted for nearly $2 billion. Kazakhstan’s own reported export figures under the same trade category were considerably lower, highlighting a substantial discrepancy between the two sets of customs data. The path gold takes from extraction to a local jewelry workshop remains one of the industry’s weak points. Deputy Prime Minister and Minister of National Economy Serik Zhumangarin said jewelers need a legal and affordable source of raw material. “We have major jewelry centers, and it is important to preserve this heritage and bring as much of the industry as possible into the legal economy,” Zhumangarin said, citing the importance of giving jewelers access to legally sourced gold. Pawnshops are another part of the gray market. In 2025, they sent about 3.2 metric tons of precious-metal scrap and waste to Tau-Ken Altyn for processing, down from 3.8 tons a year earlier. Tau-Ken Altyn operates a major precious-metals refinery in Astana. Refining involves purifying mined or recycled metal to a high degree of purity. The government is now considering requiring jewelry scrap and waste to be transferred to refiners. The authorities also want to revise the rules governing its acceptance and subsequent sale. The exact size of the shadow market is unknown. In 2024, Kaysar Zhumagaliyev, head of Kazakhstan’s League of Jewelers, said as much as 99% of the market was operating in the shadows. The association estimated the gray market at approximately $850 million to $960 million a year, using the average exchange rate for 2024. Zhumagaliyev linked it to underground workshops, smuggling, and gold purchases outside official channels. The government’s latest figures offer a more cautious picture, but they clearly illustrate the gap between registered businesses and the control system. In 2024, only 45 market participants submitted jewelry for mandatory hallmarking. In 2025, that number rose to 959. Tax authorities count 3,520 taxpayers working with jewelry, meaning that about 27% of them submitted products for mandatory hallmarking last year. A hallmark certifies the fineness of the precious metal and indicates that a piece has passed through the legal control system. The procedure therefore provides the authorities with one of the few measurable indicators...

Karachaganak Maintenance to Cut Kazakhstan’s Oil Output by Up to 450,000 Tons

Karachaganak, one of Kazakhstan’s three largest oil and gas fields, entered planned maintenance on September 7, a shutdown expected to reduce the country’s oil and gas condensate output by 400,000–450,000 metric tons before work ends on October 1. The interruption comes in a year when the government has already lowered its national production forecast following repeated disruptions to the Caspian Pipeline Consortium (CPC), the main export route for Kazakhstan’s oil. In August, Energy Minister Yerlan Akkenzhenov said Kazakhstan had lowered its 2026 oil production target from 98 million to 96 million metric tons. He put production losses from attacks on CPC infrastructure in January, June, and July at about 3.5 million metric tons. CPC loadings rebounded by 22% in August after July’s disruptions, reaching around 1.6 million barrels per day (bpd). CPC exports are expected to fall to about 1.5 million bpd in September, partly because of the Karachaganak maintenance. More than 80% of Kazakhstan’s oil exports move through CPC. The July shutdown at the Black Sea terminal showed how quickly an export disruption can force production cuts at fields far inland. On July 22, Kazakhstan’s oil and gas condensate output fell by about 21%, while output at Tengiz dropped 56%, from roughly 925,000 to 406,000 bpd. Karachaganak also depends on Russian processing infrastructure. Raw gas from the field is sent to Russia’s Orenburg gas processing plant. In June, Karachaganak reduced production after an incident at the plant sharply curtailed its intake of gas from the field. Karachaganak Petroleum Operating B.V. (KPO), the field’s operator, is expanding its gas reinjection capacity. The process returns some of the produced gas to the reservoir, helping to maintain pressure and sustain oil and gas condensate output. A fifth gas reinjection compressor began operating in 2024. In June 2026, KPO announced that the KEP-1B project, which includes a sixth compressor, had begun reinjecting gas ahead of schedule. The Energy Ministry has said the two compressors would help maintain Karachaganak’s liquid hydrocarbon production at around 11–12 million metric tons a year. Following the expansion of Tengiz, Kazakhstan had expected national oil production to approach 100 million metric tons a year. Its production capacity has increased, but the events of 2026 have exposed the limits of the infrastructure used to move that oil to market. In May, Akkenzhenov said there was no full-scale alternative to CPC. Some oil can be rerouted across the Caspian into the Baku-Tbilisi-Ceyhan pipeline or east to China, but these routes cannot absorb CPC-scale volumes. CPC can carry up to 72.5 million metric tons a year from Kazakhstan. Whether or not the maintenance reduction was already incorporated into the revised forecast, Kazakhstan has little room for further disruption to the export and processing infrastructure on which its production depends.

From Critical Minerals to Connectivity: South Korea’s Stakes in Central Asia

On September 16, Seoul hosted the first Korea–Central Asia Summit, bringing President Lee Jae Myung together with the heads of all five Central Asian states. The meeting elevated a dialogue that has run at a ministerial level since 2007 to the level of heads of state. The leaders adopted a Seoul Declaration setting the terms for future engagement and agreed to hold summits every two years. On September 14, trade and industry ministers from South Korea and the five Central Asian states met in Seoul for the first C5+Korea Industry Ministers’ Meeting. They signed a joint statement launching a standing platform for industrial cooperation. Uzbekistan’s Ministry of Investment, Industry and Trade used the occasion to push for a shift away from raw-material trade toward joint production and localization. Behind the diplomatic choreography sits a practical problem: the minerals both sides keep discussing cannot move without a route to carry them. A Minerals Agenda with Separate Tracks South Korea relies heavily on imported minerals for its manufacturing industries. Seoul has been developing separate plans with each country. With Tajikistan, discussions have focused on gold and silver, alongside antimony. With Kyrgyzstan, Seoul has been discussing antimony and tungsten. Cooperation with Uzbekistan covers minerals and digital manufacturing. With Kazakhstan, a central issue is moving beyond raw exports toward processing inside the country, as The Times of Central Asia reported ahead of the summit. South Korean firms are pursuing supply diversification independently. POSCO International and LX International have been expanding overseas mineral investments, including graphite and nickel projects, amid Chinese export restrictions. The Transport Connection Consider the Bolashak chrome mine in Kazakhstan, which Eurasian Resources Group launched in late 2024. The company plans to ramp it up to a design capacity of 7.5 million metric tons of chrome ore a year. Production on that scale makes reliable transport an essential part of the commercial equation. An Atlantic Council analysis identifies limited processing capacity and underdeveloped westward routes as obstacles to U.S. mineral partnerships with Central Asia. It presents the Trans-Caspian Middle Corridor as a route to Western markets that avoids Russian and Iranian territory. That argument needs a distinction when applied to Korea. The corridor runs westward toward Europe; it is not a prerequisite for minerals to reach South Korea. Its relevance is the wider choice of buyers it could offer Central Asian producers, including potential Korean-backed processing ventures serving those markets. That corridor is being built out. The Aktau container hub has a planned capacity of 240,000 twenty-foot equivalent units. The World Bank-backed Mointy–Kyzylzhar railway is meant to remove a 149-kilometer detour and accommodate 30 train pairs a day, against roughly ten on the existing constrained route. Traffic is already rising: 125 container trains crossed Kazakhstan on the Trans-Caspian route in the first quarter of 2026, up 34.4% year-on-year. Japan has also become involved, pledging in August 2025 to help modernize customs operations at the port of Aktau. The Seoul Declaration also backs Korean participation in transport infrastructure, including modernization and digitalization. In...