• KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
03 November 2026

Viewing results 1 - 6 of 52

Opinion: Central Asia’s Minilateral Diplomacy and the Limits of Cooperation

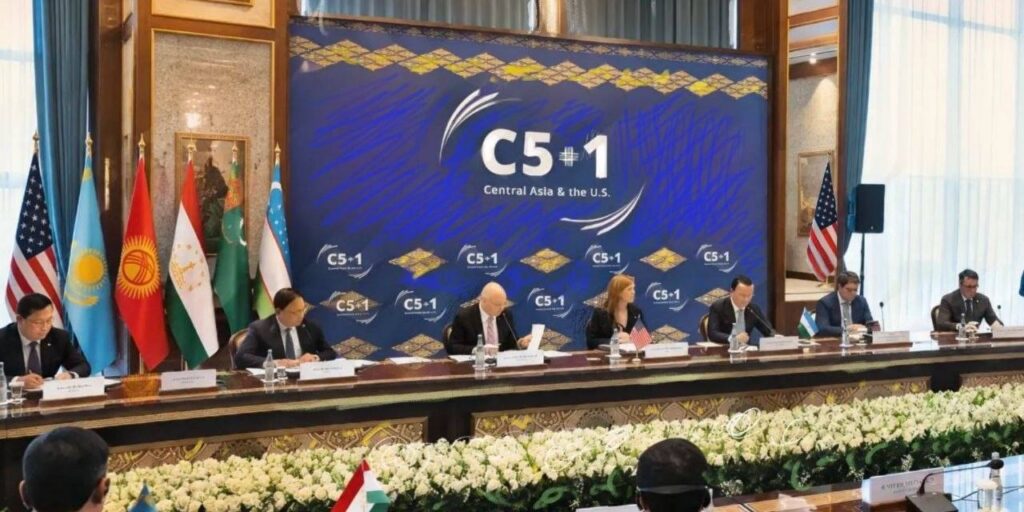
In the contemporary, largely fragmented world order, the concept of minilateralism has become increasingly relevant. As less powerful, smaller states are struggling with often ineffective multilateral diplomatic frameworks, cooperation on a smaller scale has been gaining momentum in international relations. Central Asian countries, although with an intrinsic set of strengths and resources, still lack the power to individually address some of their own issues and advocate more proactively for their interests, especially in global forums dominated by major powers and entities. Geopolitical weaknesses of each Central Asian country lie in insufficiently developed domestic economic and military power to compete with much stronger neighbors such as Russia or China. Furthermore, unfavorable geography, where Central Asia, as a landlocked region, has limited access to global trade chains, also dilutes its geopolitical strength. In addition, the transboundary nature of critical resources, especially concerning water flows and supply, often causes tensions among states of Central Asia. In such discouraging circumstances, minilateralism promises more realistic solutions that can place Central Asia on a more equal footing with external partners and enable the region to play a more significant role in regional and, to some extent, international politics. That is why the consultative meetings of the five Central Asian countries (C5), now expanded to include Azerbaijan as C6, and C5+1 dialogues with external partners have become important platforms for Central Asia’s diplomatic standing. Minilateralism and Central Asia Minilateralism represents an international relations concept that implies cooperation of a smaller group of countries (usually three to nine members) in order to resolve shared problems or pursue mutual objectives. While bilateralism remains the main form of cooperation in international politics and multilateralism is necessary for tackling global issues, minilateralism has emerged as a more appropriate response for addressing specific regional issues in a more flexible and efficient manner. One of the main features of minilateralism is prioritizing shared interests over values or ideological principles, which allows collaborating states to focus more on solving issues and avoid being burdened by ideological discrepancies. Take, for example, the Abraham Accords that managed to gather countries with very different ideological views, especially Israel and the United Arab Emirates, but still produced tangible results of cooperation. Another advantage of minilateralism is a quicker response to crises, as well as opportunities, with less of the bureaucratic hassle that often follows multilateral diplomacy. For Central Asia, working together provides a stronger platform for negotiating better outcomes, especially in the economic area. While the current major geopolitical tensions, such as the Russia-Ukraine conflict and the Iran war, continue to shake the international order, the Central Asian countries have become more aware of their opportunities, especially in terms of transit routes and natural resource demand. Central Asia has definitely caught the attention of major powers, and its geographical position along alternative transportation routes, as well as its considerable wealth of natural resources, including hydrocarbons and critical materials, opens doors for the region to gain more influence and power. However, for all of these opportunities to materialize, Central...
Opinion: Central Asia’s Wider Future: The CAMCA Network Brings Regional Cooperation to Baku

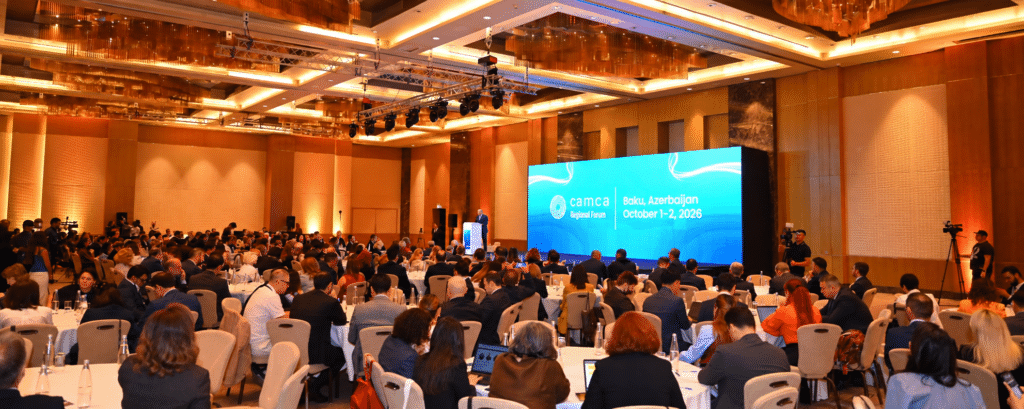
Central Asia is helping shape a wider regional agenda, one that connects trade and investment with technology, education, and security. In Baku, the CAMCA Regional Forum is bringing together the people who can carry that agenda forward, with the CAMCA Network helping turn shared interests into opportunities for cooperation. Taking place on October 1–2 at the Fairmont Baku Flame Towers, the 2026 CAMCA Regional Forum convenes policymakers, business leaders, investors, educators, researchers, and entrepreneurs under the theme “The World and CAMCA: A Region at the Crossroads.” Its central question is how regional cooperation can expand economic opportunities and strengthen the capacity of countries and communities to shape their future. The CAMCA Network helps shape this conversation. As a co-founder and co-organizer of the forum, it connects professionals across Central Asia, Mongolia, the Caucasus, and Afghanistan. Its members contribute expertise, lead discussions, and bring the experience of working in the region into the program. They also give the forum continuity: relationships strengthened in Baku can support collaboration long after the gathering concludes. For Central Asia, that wider community matters. The five countries have distinct economic structures, resources, and international relationships. Cooperation must reflect those differences while identifying where shared effort can expand their choices. Connections with the Caucasus, Mongolia, and Afghanistan offer different opportunities and challenges, each deserving a place in the regional conversation. The CAMCA Regional Forum’s discussions of global shifts through 2030 and greater Central Asia–Caucasus convergence address this strategic landscape. “From C5 to a Wider Framework” asks how a broader geography of cooperation might serve the region’s interests. The underlying issue is the ability of countries to shape their own decisions: how working with neighbors can strengthen their options in a changing international environment. Economic connectivity provides a concrete test. Routes across the Caspian and through the Caucasus can help Central Asian countries reach additional markets and partners. Their value depends on dependable transport, workable procedures, and institutions able to coordinate across borders. Businesses need enough certainty to invest, plan, and build lasting commercial relationships. Today’s discussion on connecting CAMCA to the world brings these questions together. For Central Asia, the opportunity extends beyond moving goods through the region. Better connections can support production, logistics, services, and investment within it. The strategic objective is to create more value locally and give regional enterprises a stronger place in wider markets. The forum’s paired sessions on public policy and the private sector approach that objective from complementary directions. Governments influence the conditions under which companies operate. Businesses decide where to commit capital, develop products, and employ people. Bringing these perspectives together helps clarify which barriers require public action and where commercial initiative can move cooperation forward. Technology adds another dimension. The discussion of artificial intelligence asks where CAMCA fits in a rapidly changing global economy. The Digital Silk Road roundtable connects that question with financial services and innovation. For entrepreneurs in Central Asia, digital connections can open access to customers, payments, financing, and partners across borders. The investment and entrepreneurship...

Opinion: Central Asia Is More Than Minerals

For years, Central Asia was one of those regions that Washington periodically rediscovered and then forgot. Officials visited and announced new initiatives, but the relationship hardly changed. That is no longer the case. Many pundits see the current surge of American interest in Central Asia through the lens of transactional foreign policy: nowadays the focus has been on critical minerals, supply-chain security, and competition with China. Valid so far as it goes, this approach misses the larger story. Central Asia is not suddenly important because of its minerals or because Washington has decided that it is. Increasingly, Washington must pay attention to Central Asia because the region itself is changing, and in largely positive directions. Over three decades, American investors largely dismissed the region as too poorly governed and too distant. Now the region itself is working to change the conditions that made it unattractive. The transformation is far from complete, but it is real. When the Central Asian states emerged from the Soviet Union in 1991, they faced grave disadvantages. State enterprises dominated their economies, and they fell short of Western investors’ expectations in both the rule of law and transparency. While such problems have not disappeared, they are everywhere being worked on. Uzbekistan provides the clearest example. Since 2017, Tashkent has undertaken reforms to liberalize its economy and improve the environment for private investment. The World Bank now describes Uzbekistan as one of the world's top reformers. Kazakhstan has also built more sophisticated financial and regulatory institutions. Its goal is to position itself as a regional hub for logistics, energy, and finance. The World Bank's new 2026–31 country strategy emphasizes a "business-ready Kazakhstan," with greater private-sector participation, improved infrastructure, and better natural-resource management. The pace of change in Kyrgyzstan, Tajikistan, and Turkmenistan has been slower, for understandable reasons. Kyrgyzstan’s early political reforms long left the government rudderless, Tajikistan endured a five-year civil war, and Turkmenistan was stymied by Russia’s total control of its gas industry. Now these countries, too, are belatedly advancing. Central Asia has not become Switzerland. Corruption, political interference, and governance problems still afflict the countries’ economies, and the OECD continues to identify these as important obstacles to investment. The question is not whether Central Asia has solved these problems but whether it has changed enough to become investable. The answer increasingly is yes, it has. Moscow's offensive in Ukraine accelerated changes Washington had sought for decades. Secondary sanctions compelled Central Asians to develop new commercial avenues not subject to international restrictions. While Central Asian governments maintain important relations with Russia, they all seek pragmatic alternatives that reduce their former reliance on Moscow. The countries are expanding regional cooperation while reaching across the Caspian to the South Caucasus and beyond. The resulting Middle Corridor promises direct access to global markets. The measure of its success will be whether Kazakhstan and Turkmenistan gain trans-Caspian pipelines to transport their resources directly to Europe. In short, Central Asia is doing what Washington has long wanted it to do: become more...

The Language Gap: Why the Korean Language Is Outpacing Japanese in Kazakhstan and Uzbekistan

Two weeks ago, Kazakhstan officially joined South Korea’s Employment Permit System (EPS), becoming the 18th country admitted to the program. Even before the change, thousands of Kazakhstani nationals were working in South Korea, many without legal status. Kazakhstani authorities estimated the total at around 15,000 in 2025, including 11,000 without legal documentation. To work legally in South Korea under the EPS, applicants must pass the EPS-TOPIK, a standardized Korean-language test. In this context, learning Korean has become a direct route to better-paid work for many young people in Kazakhstan. Japan, however, has generated no comparable rush. A Widening Gap, By the Numbers The contrast is also evident in language-learning trends. In 2022, Jang Ho-jong, a professor at the Kazakh Ablai Khan University of International Relations and World Languages, told The Korea Times that Korean ranked alongside English and Chinese among Kazakhstan’s three most popular foreign languages and was taught at 15 to 20 universities. About 400 students were taking Korean courses at his university, compared with just three or four when the program opened 20 years earlier. South Korea has also expanded teaching and testing infrastructure. In July 2026, the King Sejong Institute at Akhmet Baitursynuly Kostanay Regional University became Kazakhstan’s first official center for the Sejong Korean Language Assessment (SKA), allowing candidates to take the exam without traveling abroad. Official enrollment data from the King Sejong Institute Foundation show that 1,320 students were enrolled at its institutes in Kazakhstan in 2025, down slightly from 1,481 in 2024. The picture is very different for Japanese. The Japan Foundation counted 581 learners across eight institutions in Kazakhstan in 2024, compared with 1,569 learners in 2006. In Uzbekistan, Korean-language education has expanded even faster. The country recorded the largest increase worldwide in 2025, adding 68 schools offering Korean classes. Sri Lanka placed second with 43. Enrollment at King Sejong institutes in Uzbekistan rose from 1,873 in 2021 to 7,931 in 2024. It eased to 6,308 in 2025, according to the same official dataset. Japanese-language study has also grown in Uzbekistan, but more slowly. The same Japan Foundation survey counted 4,201 learners across 19 institutions in 2024, up from 3,579 at 18 institutions in 2021. Although the two datasets cover different types of institutions, the nationwide Japanese total remained below enrollment in Uzbekistan’s King Sejong network that year. A More Complicated Picture Next Door Across the rest of Central Asia, however, the comparison is less clear-cut. The Japan Foundation’s 2024 regional survey recorded 1,708 Japanese-language learners at 14 institutions in Kyrgyzstan, taught by 50 teachers. That was almost three times Kazakhstan’s total, even though Kyrgyzstan’s population is roughly one-third as large. Among the learners in Kyrgyzstan, 411 were in primary or secondary education. A 2020 account by a Japan Foundation specialist described young people learning through anime and the internet, while Japan International Cooperation Agency volunteers introduced Japanese in rural schools. Some later traveled to Bishkek for more formal study. This points to demand developing from the ground up alongside institutional support. Korean-language...

Opinion: Why Central Asia Cannot Afford to Abandon the Iranian Route

Kazakhstan had barely secured a foothold in Iran’s largest commercial port when renewed military escalation made the southern route risky again. The problem for Central Asia is that Iran is more than a trading partner. For a region without direct access to the open sea, it provides one of the few overland routes to the Persian Gulf and the Indian Ocean. On June 28, Kazakhstan and Iran signed a 27-year build-operate-transfer (BOT) agreement for a Kazakh transport and logistics terminal at Shahid Rajaee Port in Bandar Abbas. The agreement allocates two years for construction and the following 25 for operation. Astana expects the terminal to provide more direct access to markets in the Gulf, South and Southeast Asia, and East Africa. The project almost immediately found itself in a different reality. In July, U.S. strikes hit Iranian railway and coastal infrastructure. The Aq Taqeh Khan bridge on a rail route connecting Iran with Turkmenistan and, further north, with Kazakhstan, was damaged. There was no confirmed halt to Central Asian freight traffic, but military risk was no longer an abstract concern for carriers. That risk has now been compounded by a new U.S. sanctions campaign. On August 24, U.S. Treasury Secretary Scott Bessent launched what Washington calls Operation Economic Outcast, combining direct sanctions with pressure on Iran’s foreign economic partners. The United States said it would set timelines for other countries to shut down economic activity with Iran, while the scope of secondary sanctions was expanded to cover five areas: digital assets, technology, gold, aviation, and shipping. Nearly 60 Iran-linked individuals, entities, and vessels were also sanctioned. The United States has not publicly identified which countries could face penalties first. War and sanctions can make the Iranian route more expensive, slower, and more dangerous. They cannot change geography. Iran gives Central Asia overland access to ports on the Persian Gulf and Gulf of Oman. From Bandar Abbas and Chabahar, cargo can move onward toward India, the Gulf states, and East Africa. Iran also provides a western overland route toward Turkey. This is one of the fundamental differences between the Iranian route and the Middle Corridor, which crosses the Caspian Sea before continuing through Azerbaijan, Georgia, and Turkey. The Middle Corridor requires cargo to move between rail and maritime transport. Iran offers the possibility of a continuous overland chain while also providing access to ports connected to the Indian Ocean. For Kazakhstan, the southern route is already more than a plan. Trade with Iran increased by 26.4% in 2025 to $430.2 million. Freight traffic along the International North-South Transport Corridor reached 3.5 million tons, while rail traffic between Kazakhstan and Iran increased by 69%. It is this expanding transport network that is now exposed to greater military and sanctions risks. There is another factor. A free trade agreement between Iran and the Eurasian Economic Union, which includes Kazakhstan and Kyrgyzstan, entered into force on May 15, 2025. It significantly reduced tariff barriers to trade in goods between the two sides. Uzbekistan offers...

Turkmenistan and the New Geopolitics of Silicon

Central Asia is not foreign to the emerging geopolitics of silicon and artificial intelligence (AI). Kazakhstan especially has made itself noticed, joining the US-led Pax Silica initiative in June and the Chinese-led World Artificial Intelligence Cooperation Organization (WAICO) in July. Kazakhstan is the only country participating in both initiatives, which is characteristic of Astana’s multi-vector diplomacy. Whilst other Central Asian states have joined WAICO, Turkmenistan, consistent with its permanent neutrality stance, has joined neither. Neutrality, however, does not prevent economic participation, and a case has to be made for Turkmenistan. Two Frameworks for International Cooperation Although both initiatives respond to the same underlying reality - the growing strategic importance of artificial intelligence - they differ in scope and emphasis. Pax Silica is built around the material and economic foundations of AI, focusing on securing and coordinating the physical supply chains that make computation possible and aiming implicitly to reduce reliance on China. WAICO, by contrast, is centered on the political and normative dimension of AI, prioritizing governance, safety standards, and international coordination, where Beijing could push its rhetoric in favour of open-source artificial intelligence as a model for AI development. Taken together, they reflect two complementary but distinct ways of structuring the emerging AI order: one rooted in industrial capacity and supply-chain control, the other in multilateral rules. On that matter, Turkmenistan's possible relevance does not lie in software, semiconductor fabrication or AI regulation, but much further upstream: silicon metallurgy. From Gas to Silicon Silicon is abundant in nature, but transforming it into industrial materials is an energy-intensive process. Quartz or quartzite is used to produce both silicon ferroalloys and silicon metal. Ferrosilicon is principally consumed by the iron and steel industries, where it serves as a deoxidizing and alloying agent. Silicon metal, meanwhile, is used in aluminum alloys and chemical production, while a small share is further purified into the extremely high-purity silicon required by the semiconductor industry. Ferrosilicon should not be presented as a material that goes directly into AI chips. But establishing competitive ferrosilicon production can constitute a first industrial step into the broader family of silicon metallurgy. And Turkmenistan has already begun considering precisely that. In 2020, the Turkmen authorities reported that the Ministry of Industry was studying the production of metallurgical-grade silicon using local resources. Practical tests had already been conducted using quartz sand, metal mixtures and petroleum coke, while the government presented the development of domestic mineral resources as part of a broader strategy of industrialization and export diversification. The ambition became more concrete in January 2024. Turkmenistan's Ministry of Industry and Construction Production launched an international tender for a feasibility study for a ferroalloy plant intended to manufacture ferrosilicon, silicon carbide, and technical silicon. A 2024 feasibility study for such a project envisions a plant in Balkan Velayat capable of producing 15,000 tons of FeSi75 ferrosilicon annually. The proposed complex would operate two 12,500 kVA furnaces. Rather than depending exclusively on domestic raw materials, the study envisages sourcing quartzite from nearby Iran and...