• KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
  • KZT/USD = 0.00223
  • TJS/USD = 0.10800
  • UZS/USD = 0.00009
  • TMT/USD = 0.29760
20 September 2026

Viewing results 7 - 12 of 2700

Turkmenistan Advances TAPI Pipeline and Infrastructure Projects in Herat

Turkmenistan has spent years seeking new gas export routes, and in western Afghanistan that effort is taking physical form. By mid-September, 122.3 kilometers of pipe had been welded and laid along the Turkmenistan-Afghanistan-Pakistan-India (TAPI) route in Herat Province. Ashgabat is also pursuing two other connections with Afghanistan along the same corridor. Energy officials are discussing a 500 kV transmission line, while plans call for a railway from the Turkmen border to reach Herat and eventually extend farther south. Herat is becoming the focal point for Turkmen gas, electricity, and freight. For Ashgabat, supplying Herat could give TAPI its first functioning Afghan market without waiting for the entire pipeline to reach Pakistan and India. Afghanistan would gain energy supplies and infrastructure, as well as a chance to connect its western region more closely to regional trade. As of September 15, Afghanistan’s Ministry of Mines and Petroleum reported that 150.3 kilometers of the 153-kilometer TAPI route in Herat Province had been prepared for pipe installation. Of the 122.3 kilometers of pipe welded and laid, 71.5 kilometers had been buried. Hydrostatic testing had been completed on 33 kilometers. The ministry’s estimate of nearly 80% completion applies only to pipe-laying along this section. In May, the ministry reported that 63 kilometers of pipe had been laid. Four months later, the figure had nearly doubled. The pipeline is designed to run roughly 1,814 kilometers from Turkmenistan’s Galkynysh gas field through Afghanistan and Pakistan to the Indian border. Its planned capacity is 33 billion cubic meters a year. At full capacity, the Asian Development Bank’s current project description allocates 5% of the gas to Afghanistan and 47.5% each to Pakistan and India. The pipeline has been under discussion for more than three decades. Conflict, financing shortages, security threats, and disputes over commercial terms have repeatedly delayed it. Work on Afghan territory resumed in September 2024. The latest figures from Herat make it possible, for the first time in years, to measure TAPI’s progress in kilometers of pipeline rather than diplomatic statements. For Turkmenistan, the stakes are high. The country holds the world’s fourth-largest natural gas reserves, but most of its gas exports go to China. Beijing receives around 30 billion cubic meters of Turkmen gas annually and continues to work with Ashgabat on expanding production at Galkynysh. In February, Gurbanguly Berdimuhamedov said diversifying gas export routes was one of the country’s primary goals. Together, Pakistan and India would provide Turkmenistan with markets comparable in scale to its Chinese market. To reach them, however, the pipeline still has to cross most of Afghanistan and then Pakistan. Tensions between Kabul and Islamabad, along with the difficult relationship between Pakistan and India, continue to create political and transit risks for the full project. Herat offers a smaller market that could be reached sooner. A distribution network is planned in the city to supply gas to businesses, power plants, and households. In August, Turkmengaz and Afghan Gas signed a memorandum on the gasification of the province. The memorandum covers local...
Karachaganak Maintenance to Cut Kazakhstan’s Oil Output by Up to 450,000 Tons

Karachaganak, one of Kazakhstan’s three largest oil and gas fields, entered planned maintenance on September 7, a shutdown expected to reduce the country’s oil and gas condensate output by 400,000–450,000 metric tons before work ends on October 1. The interruption comes in a year when the government has already lowered its national production forecast following repeated disruptions to the Caspian Pipeline Consortium (CPC), the main export route for Kazakhstan’s oil. In August, Energy Minister Yerlan Akkenzhenov said Kazakhstan had lowered its 2026 oil production target from 98 million to 96 million metric tons. He put production losses from attacks on CPC infrastructure in January, June, and July at about 3.5 million metric tons. CPC loadings rebounded by 22% in August after July’s disruptions, reaching around 1.6 million barrels per day (bpd). CPC exports are expected to fall to about 1.5 million bpd in September, partly because of the Karachaganak maintenance. More than 80% of Kazakhstan’s oil exports move through CPC. The July shutdown at the Black Sea terminal showed how quickly an export disruption can force production cuts at fields far inland. On July 22, Kazakhstan’s oil and gas condensate output fell by about 21%, while output at Tengiz dropped 56%, from roughly 925,000 to 406,000 bpd. Karachaganak also depends on Russian processing infrastructure. Raw gas from the field is sent to Russia’s Orenburg gas processing plant. In June, Karachaganak reduced production after an incident at the plant sharply curtailed its intake of gas from the field. Karachaganak Petroleum Operating B.V. (KPO), the field’s operator, is expanding its gas reinjection capacity. The process returns some of the produced gas to the reservoir, helping to maintain pressure and sustain oil and gas condensate output. A fifth gas reinjection compressor began operating in 2024. In June 2026, KPO announced that the KEP-1B project, which includes a sixth compressor, had begun reinjecting gas ahead of schedule. The Energy Ministry has said the two compressors would help maintain Karachaganak’s liquid hydrocarbon production at around 11–12 million metric tons a year. Following the expansion of Tengiz, Kazakhstan had expected national oil production to approach 100 million metric tons a year. Its production capacity has increased, but the events of 2026 have exposed the limits of the infrastructure used to move that oil to market. In May, Akkenzhenov said there was no full-scale alternative to CPC. Some oil can be rerouted across the Caspian into the Baku-Tbilisi-Ceyhan pipeline or east to China, but these routes cannot absorb CPC-scale volumes. CPC can carry up to 72.5 million metric tons a year from Kazakhstan. Whether or not the maintenance reduction was already incorporated into the revised forecast, Kazakhstan has little room for further disruption to the export and processing infrastructure on which its production depends.

From Critical Minerals to Connectivity: South Korea’s Stakes in Central Asia

On September 16, Seoul hosted the first Korea–Central Asia Summit, bringing President Lee Jae Myung together with the heads of all five Central Asian states. The meeting elevated a dialogue that has run at a ministerial level since 2007 to the level of heads of state. The leaders adopted a Seoul Declaration setting the terms for future engagement and agreed to hold summits every two years. On September 14, trade and industry ministers from South Korea and the five Central Asian states met in Seoul for the first C5+Korea Industry Ministers’ Meeting. They signed a joint statement launching a standing platform for industrial cooperation. Uzbekistan’s Ministry of Investment, Industry and Trade used the occasion to push for a shift away from raw-material trade toward joint production and localization. Behind the diplomatic choreography sits a practical problem: the minerals both sides keep discussing cannot move without a route to carry them. A Minerals Agenda with Separate Tracks South Korea relies heavily on imported minerals for its manufacturing industries. Seoul has been developing separate plans with each country. With Tajikistan, discussions have focused on gold and silver, alongside antimony. With Kyrgyzstan, Seoul has been discussing antimony and tungsten. Cooperation with Uzbekistan covers minerals and digital manufacturing. With Kazakhstan, a central issue is moving beyond raw exports toward processing inside the country, as The Times of Central Asia reported ahead of the summit. South Korean firms are pursuing supply diversification independently. POSCO International and LX International have been expanding overseas mineral investments, including graphite and nickel projects, amid Chinese export restrictions. The Transport Connection Consider the Bolashak chrome mine in Kazakhstan, which Eurasian Resources Group launched in late 2024. The company plans to ramp it up to a design capacity of 7.5 million metric tons of chrome ore a year. Production on that scale makes reliable transport an essential part of the commercial equation. An Atlantic Council analysis identifies limited processing capacity and underdeveloped westward routes as obstacles to U.S. mineral partnerships with Central Asia. It presents the Trans-Caspian Middle Corridor as a route to Western markets that avoids Russian and Iranian territory. That argument needs a distinction when applied to Korea. The corridor runs westward toward Europe; it is not a prerequisite for minerals to reach South Korea. Its relevance is the wider choice of buyers it could offer Central Asian producers, including potential Korean-backed processing ventures serving those markets. That corridor is being built out. The Aktau container hub has a planned capacity of 240,000 twenty-foot equivalent units. The World Bank-backed Mointy–Kyzylzhar railway is meant to remove a 149-kilometer detour and accommodate 30 train pairs a day, against roughly ten on the existing constrained route. Traffic is already rising: 125 container trains crossed Kazakhstan on the Trans-Caspian route in the first quarter of 2026, up 34.4% year-on-year. Japan has also become involved, pledging in August 2025 to help modernize customs operations at the port of Aktau. The Seoul Declaration also backs Korean participation in transport infrastructure, including modernization and digitalization. In...

Kazakhstan Ranks 38th in IMD World Competitiveness Ranking

Kazakhstan ranked 38th among 70 economies in the 2026 IMD World Competitiveness Ranking. With an index score of 65.4, Kazakhstan ranked ahead of Spain, Portugal, Poland, India, and Italy. Singapore took first place, followed by Hong Kong and Switzerland. The annual ranking assesses economies across four main areas — economic performance, government efficiency, business efficiency and infrastructure. IMD combines statistical data with a survey of senior executives. Hard data account for two-thirds of the ranking and covered 172 criteria in 2026, while responses from around 6,900 executives were used for another 92 criteria. IMD’s methodology explains that the indicators are designed to measure both quantifiable economic conditions and how businesses view the environment in which they operate. Kazakhstan’s strongest results came in government and business efficiency, where it ranked 23rd globally in both categories. Tax policy was a particular strength, placing ninth among the 70 economies assessed. Kazakhstan’s economy expanded by 6.5% in 2025, the sixth-highest growth rate among the economies assessed by IMD. It also ranked sixth among economies with GDP per capita below $20,000. Kazakhstan is the only Central Asian economy included in the 2026 IMD World Competitiveness Ranking. IMD relies heavily on internationally comparable statistics and business survey data. Reliable data is essential for judging competitiveness. Kazakhstan leads Central Asia in the World Bank’s Statistical Performance Indicators and, alongside Kyrgyzstan, was one of only two regional governments to meet the U.S. State Department’s 2026 minimum fiscal-transparency requirements. Kazakhstan has also subscribed to the International Monetary Fund’s Special Data Dissemination Standard since March 2003. The standard sets requirements for the coverage, periodicity, and timeliness of economic data, as well as public access, integrity and information on methodology.

Kyrgyzstan’s High-Wire Act: Sanctions, Compliance, and National Interest

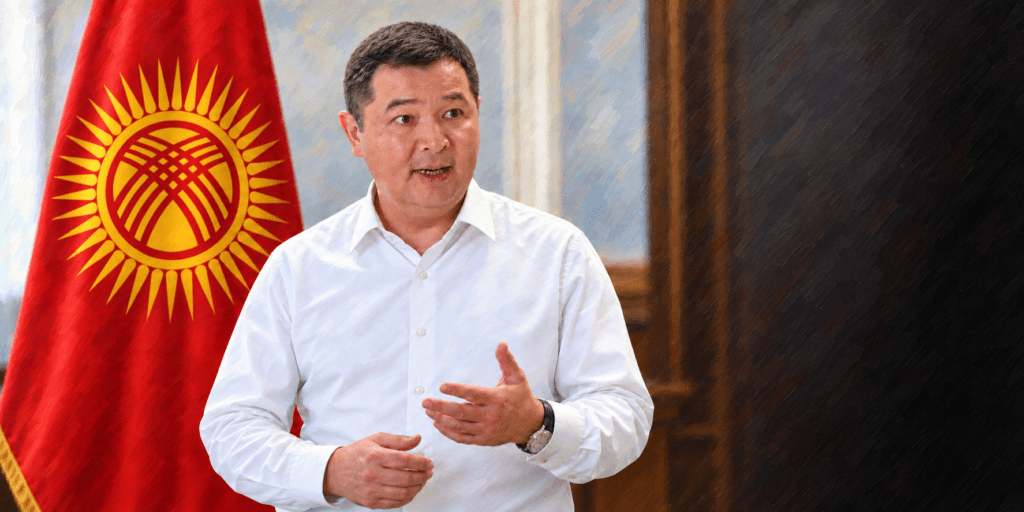
On September 2, the day after the Shanghai Cooperation Organization’s Heads of State Summit in Bishkek, The Times of Central Asia spoke with Bakyt Sydykov, Kyrgyzstan’s Minister of Economy and Commerce and Special Presidential Representative for Sanctions Policy. He outlined the government’s approach to sanctions compliance and protecting Kyrgyz businesses. Sanctions exposure can affect Kyrgyz banks and businesses, as well as their international partners. U.S. secondary sanctions and EU and UK measures affecting foreign entities operate through different legal mechanisms. Some portions of the text have been edited for clarity.   TCA: The sanctions against Russia adopted by the U.S., EU, and UK are not UN Security Council-mandated. Is it correct that Kyrgyzstan’s compliance policy addresses these measures rather than UN-mandated sanctions? Sydykov: That's correct. Secondary sanctions can affect non-U.S., non-EU, and non-UK entities or persons who knowingly facilitate transactions involving sanctioned parties. Our focus is on establishing better and better mechanisms and frameworks that address this bilateral dimension, that is, Kyrgyzstan's direct exposure through its relations with the sanctioning jurisdictions, in order to mitigate our exposure to potential secondary sanctions. TCA: Kyrgyz citizens and businesses can face sanctions exposure through dealings with sanctioned parties, including the risk of U.S. secondary sanctions. What are Kyrgyzstan’s main challenges in improving its compliance regime, and how are you addressing them? Sydykov: For technical reasons, our compliance regime is moving toward putting in place mechanisms that can flag or be anticipatory. I think you would agree that free markets are complicated and circumvention often comes to light only after it has occurred. We are largely equipped to manage these occurrences. We are moving to put in place firewall-like frameworks which would allow the country to identify and respond to occurrences before the fact. It is a great challenge — and one that every country operating in a free-market economy faces — to develop such a capacity, namely, to anticipate and prevent circumvention before it happens. Despite our best efforts, this remains a structural limitation. TCA: What concrete actions have you taken, or are you planning to take? Sydykov: We have established working groups, task forces, and interagency committees capable of swiftly halting the operations of any company engaged in sanctions circumvention. We are also working closely with commercial banks on these efforts. The banks, for their part, have introduced internal compliance committees and, in some cases, adjusted the composition of their boards of directors to strengthen governance and decision-making around potential circumvention risks. The banks are also developing a joint interbank blacklist of sanctioned entities, so that these entities are unable to operate through the banking system going forward. Those are steps to develop a working forward-looking, predictive approach — one that flags suspicious activity before it materializes – central to the comprehensive framework we are building. TCA: Some foreign investors may be reluctant to invest in Kyrgyzstan because of sanctions exposure. How could the measures you are taking address those concerns? Sydykov: Let me first say that we understand the rationale behind...

Kazakhstan to Receive Maximum Weight in New JPMorgan Bond Index

Kazakhstan will receive the maximum 8% country weight in JPMorgan’s new index for frontier market government bonds, creating an opportunity to attract new foreign buyers of tenge-denominated debt. JPMorgan plans to launch the GBI-EM Edge by the end of September. The maximum weight for any single country is capped at 8%, and Kazakhstan will receive the full quota. Vietnam, Pakistan, and Bangladesh will have the same weight. Other major components will include Egypt, Morocco, Nigeria, and Sri Lanka. The index will cover 26 countries, with nearly $330 billion in bonds eligible for inclusion. GBI-EM Edge is designed for frontier markets, relatively less accessible markets outside JPMorgan’s main emerging market benchmark. Inclusion is a separate development from Kazakhstan’s efforts to join that main index. The index will serve as a benchmark for international asset managers. Some funds seek to replicate its composition, while others use it to compare the performance of their own portfolios. A country’s weight can therefore influence how much money investors allocate to its bonds. However, the nearly $330 billion represents the value of bonds eligible for the GBI-EM Edge, not the amount of future investment. JPMorgan has not yet said how much capital will directly track the new index. That will largely determine how significant the additional demand for Kazakh debt may be. Foreign Investors Have Already Increased Their Holdings Foreign investors began actively buying Kazakhstan’s government debt even before JPMorgan’s decision. According to the Analytical Center of the Association of Financiers of Kazakhstan (AFK), non-resident holdings of government securities reached KZT 2.5 trillion, or about $5.4 billion, by the end of June. During the first half of the year, their portfolio grew by 28.3%, while the share of non-residents in the government securities market increased from 6.2% to 6.9%. In June alone, foreign investors added KZT 185.1 billion, or about $400 million. Just a year and a half earlier, non-resident holdings stood at around KZT 1.1 trillion, or about $2.4 billion. Kazakhstan has maintained a high base rate to combat inflation. This has also kept yields on government bonds high. According to AFK, real yields on government securities – meaning returns above inflation – ranged from 5.7% to 7.4% in the first half of the year. The association’s analysts also linked strong demand to expectations of a gradual reduction in the base rate. For a foreign fund, the trade can look attractive: raise money in a market with lower interest rates, buy tenge, and invest in Kazakh government bonds. If the tenge remains stable or strengthens, the investor benefits both from the high interest rate and from the currency movement. If the tenge falls, some of that return disappears when the investment is converted back into dollars. The tenge’s appreciation has already helped foreign bondholders. It strengthened by 2.6% during August, ending the month at KZT 461.57 per dollar, according to the National Bank. AFK points to another effect of foreign purchases. To buy the bonds, non-residents sell foreign currency and purchase tenge, increasing the supply...