• KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
  • KZT/USD = 0.00220
  • TJS/USD = 0.10860
  • UZS/USD = 0.00008
  • TMT/USD = 0.29850
03 November 2026

Viewing results 13 - 18 of 293

Central Asia Growth Forecasts Remain Strong in Latest ADB Outlook

Four of Central Asia’s five economies are expected to grow faster in 2026 than developing Asia and the Pacific as a whole, according to the Asian Development Bank’s September Asian Development Outlook. ADB forecasts growth of 5% across developing Asia and the Pacific this year, compared with 8.9% in Kyrgyzstan, 7% in Uzbekistan and Tajikistan, and 6.3% in Turkmenistan. Kazakhstan is the exception, with growth forecast at 4.8%. Kyrgyzstan is growing faster than its neighbors but is also facing the highest inflation among the five countries. ADB forecasts inflation at 11.2% this year and 8.5% next year. Growth continues to be supported by domestic demand and sustained investment, while ADB says import dependence and electricity-generation shortfalls are contributing to inflationary pressures. For Uzbekistan, ADB forecasts gross domestic product growth of 7% and inflation of 6.7% in 2026. In 2027, the figures are expected to be 6.8% and 5%, respectively. Stronger-than-expected economic activity prompted ADB to upgrade Uzbekistan’s 2026 growth forecast in its September outlook. Tajikistan is also forecast to grow by 7% in 2026, with inflation at 4.5%. Growth is expected to slow to 6.8% in 2027, while inflation is forecast to edge up to 4.7%. ADB lowered its 2026 growth projection in September, saying the escalation of Russia’s war in Ukraine had disrupted fuel imports and constrained near-term economic activity. Kazakhstan, the region’s largest economy, is growing more slowly than its neighbors. ADB expects growth of 4.8% this year and 4.5% next year, with inflation forecast at 10.4% and 9.5%, respectively. The bank left its growth and inflation forecasts unchanged from its previous outlook, with inflation expected to ease only gradually. For Turkmenistan, ADB forecasts growth of 6.3% in 2026 and 6.2% in 2027, with inflation at 6% in both years. The country’s economic indicators remain more difficult to compare with those of its neighbors because of limited access to reliable and detailed economic data. Its economy also remains heavily dependent on natural gas exports, with China its main gas market. Central Asia’s growth figures look strong against the Asian backdrop, but ADB is warning of energy and climate risks across developing Asia and the Pacific. Prolonged disruption to global energy markets could keep oil and gas prices elevated and volatile. For energy importers, that means higher fuel costs and additional inflationary pressure, while hydrocarbon exporters may benefit from higher prices but remain vulnerable to disruption in production and export routes. Another risk is a very strong El Niño, which ADB expects to persist through the first quarter of 2027. Extreme weather could reduce agricultural production and push up food prices, while a decline in hydropower generation could increase demand for other energy sources. For Kyrgyzstan and Tajikistan, where hydropower supplies most electricity, weather and water availability add another layer of vulnerability. The differences between forecasts for the region remain substantial. In August, The Times of Central Asia compared projections from international financial institutions. The Eurasian Development Bank (EDB) forecast 2026 growth of 10.2% for Kyrgyzstan, 8.3% for Tajikistan,...
Central Asia Trade Rises 25% as Kazakhstan and Uzbekistan Dominate

Central Asian countries are trading more actively with one another, although the regional market continues to be dominated by its two largest economies, Kazakhstan and Uzbekistan. In January-July 2026, the five countries exported $8.1 billion worth of goods to their neighbors, up 25.4% from a year earlier. Kazakhstan and Uzbekistan accounted for more than 80% of those shipments. Smaller bilateral routes have expanded as well. Uzbekistan’s trade with Kyrgyzstan increased by more than half, while trade with Tajikistan rose by 45%. Trade between Kyrgyzstan and Tajikistan rose by a factor of 3.3 after several years of border closure and sharply reduced economic ties. In absolute terms, trade between Kazakhstan and Uzbekistan remains the region’s largest bilateral flow. The figures were published by Uzbekistan’s Center for Economic Research and Reforms (CERR). Kazakhstan remains the region’s largest exporter. Over the seven-month period, it shipped $4.5 billion worth of goods to its neighbors, accounting for 55.9% of total intra-regional exports. Uzbekistan exported $2 billion, representing another 24.7%. Kazakhstan’s Central Asian neighbors still account for a relatively small share of the country’s overall foreign trade. In January-July, its total foreign trade turnover amounted to $87.75 billion. Central Asia accounted for around 6.7% of Kazakhstan’s total trade and 8.9% of its exports. By contrast, Kyrgyzstan’s trade volumes are much smaller, but neighboring markets are considerably more important to the country’s exporters, absorbing almost one-third of its exports. During the same period, Kyrgyzstan exported $523 million worth of goods to its neighbors and imported nearly $1.5 billion. Tajikistan buys considerably more from its neighbors than it sells to them. Its imports from Central Asia increased by 35% to $1.2 billion, while exports rose 6.2% to $209 million. Kazakhstan and Uzbekistan account for around 94% of Tajikistan’s trade with the region. Figures reported by Turkmenistan’s trading partners show that the country exported $844 million worth of goods to neighboring countries. Uzbekistan and Kazakhstan remain its main regional markets. The Eurasian Development Bank estimated that trade among Central Asian countries reached $12.3 billion in 2025, nearly double the 2020 level. Kazakhstan accounted for 54% of regional exports, as The Times of Central Asia previously reported. New transport and energy links are developing alongside intra-regional trade. In February, the World Bank approved an $846 million guarantee to mobilize $1.41 billion in commercial financing for a railway project in Kazakhstan. The project includes construction of the 201-mile Mointy-Kyzylzhar railway line on Kazakhstan’s section of the Trans-Caspian International Transport Route, or Middle Corridor. The new line is expected to shorten the route by 149 kilometers and relieve congestion on heavily used sections of the corridor. Central Asian countries are seeking closer integration of their power systems. In January, the World Bank approved the 10-year Regional Electricity Market Interconnectivity and Trade Program, with indicative financing of more than $1 billion, to establish Central Asia’s first regional electricity market. Cross-border electricity trade currently amounts to only around 3% of the region’s total electricity demand. In an earlier CERR analysis, researcher Ruslan Abaturov argued...

Turkmenistan Looks to AI in Customs Modernization Drive

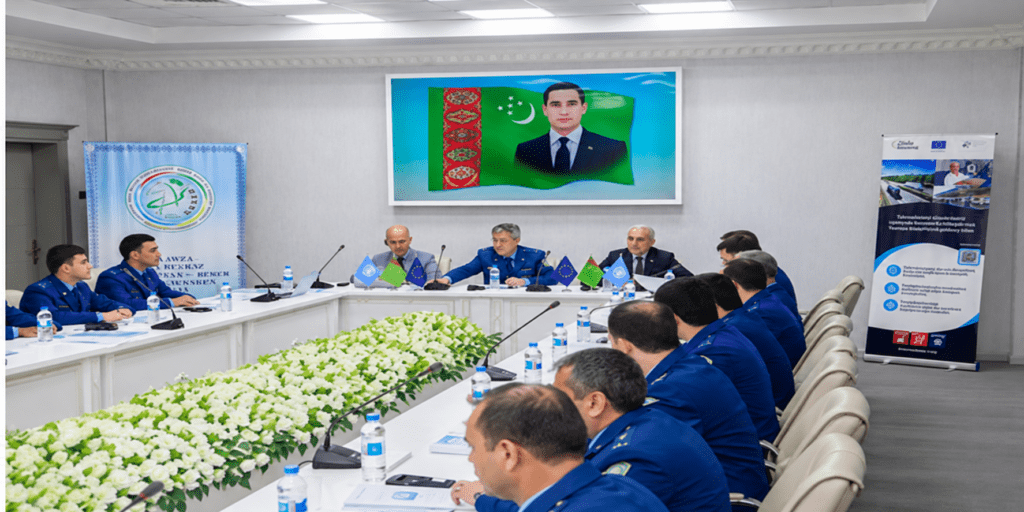
Customs specialists in Turkmenistan discussed the use of artificial intelligence in their work during a seminar last week, as the country steps up efforts to modernize trade systems and expand its role in the Caspian Sea transit corridor. The three-day training course in Ashgabat drew about 30 customs experts and was held at a regional training center. Turkmenistan’s State Customs Service said the event was part of a European Union-funded project to promote trade on the corridor, which links China and Central Asia to Europe by rail and maritime transport. The trainer at the seminar was Sertaç Yapıcı, whose LinkedIn page identifies him as a department head at the Directorate General of Customs Enforcement in Turkey. Yapıcı discussed risk management systems in customs offices and “demonstrated the effectiveness of modern methods of data analysis and the use of artificial intelligence technologies with specific examples,” the Turkmen customs authority said. The customs specialists discussed how to identify risks associated with goods and vehicles crossing borders and how “to adapt the best international approaches to the conditions of our country,” the authority added. The World Customs Organization and the customs service established the center in Ashgabat under a 2025 agreement.

Turkmenistan Advances TAPI Pipeline and Infrastructure Projects in Herat

Turkmenistan has spent years seeking new gas export routes, and in western Afghanistan that effort is taking physical form. By mid-September, 122.3 kilometers of pipe had been welded and laid along the Turkmenistan-Afghanistan-Pakistan-India (TAPI) route in Herat Province. Ashgabat is also pursuing two other connections with Afghanistan along the same corridor. Energy officials are discussing a 500 kV transmission line, while plans call for a railway from the Turkmen border to reach Herat and eventually extend farther south. Herat is becoming the focal point for Turkmen gas, electricity, and freight. For Ashgabat, supplying Herat could give TAPI its first functioning Afghan market without waiting for the entire pipeline to reach Pakistan and India. Afghanistan would gain energy supplies and infrastructure, as well as a chance to connect its western region more closely to regional trade. As of September 15, Afghanistan’s Ministry of Mines and Petroleum reported that 150.3 kilometers of the 153-kilometer TAPI route in Herat Province had been prepared for pipe installation. Of the 122.3 kilometers of pipe welded and laid, 71.5 kilometers had been buried. Hydrostatic testing had been completed on 33 kilometers. The ministry’s estimate of nearly 80% completion applies only to pipe-laying along this section. In May, the ministry reported that 63 kilometers of pipe had been laid. Four months later, the figure had nearly doubled. The pipeline is designed to run roughly 1,814 kilometers from Turkmenistan’s Galkynysh gas field through Afghanistan and Pakistan to the Indian border. Its planned capacity is 33 billion cubic meters a year. At full capacity, the Asian Development Bank’s current project description allocates 5% of the gas to Afghanistan and 47.5% each to Pakistan and India. The pipeline has been under discussion for more than three decades. Conflict, financing shortages, security threats, and disputes over commercial terms have repeatedly delayed it. Work on Afghan territory resumed in September 2024. The latest figures from Herat make it possible, for the first time in years, to measure TAPI’s progress in kilometers of pipeline rather than diplomatic statements. For Turkmenistan, the stakes are high. The country holds the world’s fourth-largest natural gas reserves, but most of its gas exports go to China. Beijing receives around 30 billion cubic meters of Turkmen gas annually and continues to work with Ashgabat on expanding production at Galkynysh. In February, Gurbanguly Berdimuhamedov said diversifying gas export routes was one of the country’s primary goals. Together, Pakistan and India would provide Turkmenistan with markets comparable in scale to its Chinese market. To reach them, however, the pipeline still has to cross most of Afghanistan and then Pakistan. Tensions between Kabul and Islamabad, along with the difficult relationship between Pakistan and India, continue to create political and transit risks for the full project. Herat offers a smaller market that could be reached sooner. A distribution network is planned in the city to supply gas to businesses, power plants, and households. In August, Turkmengaz and Afghan Gas signed a memorandum on the gasification of the province. The memorandum covers local...

From Critical Minerals to Connectivity: South Korea’s Stakes in Central Asia

On September 16, Seoul hosted the first Korea–Central Asia Summit, bringing President Lee Jae Myung together with the heads of all five Central Asian states. The meeting elevated a dialogue that has run at a ministerial level since 2007 to the level of heads of state. The leaders adopted a Seoul Declaration setting the terms for future engagement and agreed to hold summits every two years. On September 14, trade and industry ministers from South Korea and the five Central Asian states met in Seoul for the first C5+Korea Industry Ministers’ Meeting. They signed a joint statement launching a standing platform for industrial cooperation. Uzbekistan’s Ministry of Investment, Industry and Trade used the occasion to push for a shift away from raw-material trade toward joint production and localization. Behind the diplomatic choreography sits a practical problem: the minerals both sides keep discussing cannot move without a route to carry them. A Minerals Agenda with Separate Tracks South Korea relies heavily on imported minerals for its manufacturing industries. Seoul has been developing separate plans with each country. With Tajikistan, discussions have focused on gold and silver, alongside antimony. With Kyrgyzstan, Seoul has been discussing antimony and tungsten. Cooperation with Uzbekistan covers minerals and digital manufacturing. With Kazakhstan, a central issue is moving beyond raw exports toward processing inside the country, as The Times of Central Asia reported ahead of the summit. South Korean firms are pursuing supply diversification independently. POSCO International and LX International have been expanding overseas mineral investments, including graphite and nickel projects, amid Chinese export restrictions. The Transport Connection Consider the Bolashak chrome mine in Kazakhstan, which Eurasian Resources Group launched in late 2024. The company plans to ramp it up to a design capacity of 7.5 million metric tons of chrome ore a year. Production on that scale makes reliable transport an essential part of the commercial equation. An Atlantic Council analysis identifies limited processing capacity and underdeveloped westward routes as obstacles to U.S. mineral partnerships with Central Asia. It presents the Trans-Caspian Middle Corridor as a route to Western markets that avoids Russian and Iranian territory. That argument needs a distinction when applied to Korea. The corridor runs westward toward Europe; it is not a prerequisite for minerals to reach South Korea. Its relevance is the wider choice of buyers it could offer Central Asian producers, including potential Korean-backed processing ventures serving those markets. That corridor is being built out. The Aktau container hub has a planned capacity of 240,000 twenty-foot equivalent units. The World Bank-backed Mointy–Kyzylzhar railway is meant to remove a 149-kilometer detour and accommodate 30 train pairs a day, against roughly ten on the existing constrained route. Traffic is already rising: 125 container trains crossed Kazakhstan on the Trans-Caspian route in the first quarter of 2026, up 34.4% year-on-year. Japan has also become involved, pledging in August 2025 to help modernize customs operations at the port of Aktau. The Seoul Declaration also backs Korean participation in transport infrastructure, including modernization and digitalization. In...

Gazprom Central Asia Gas Supplies Rise Nearly 70% in 2026

Gazprom has increased gas supplies to Kazakhstan, Kyrgyzstan, and Uzbekistan by nearly 70% so far in 2026. Gazprom CEO Alexey Miller announced the increase on September 4 but did not disclose how much gas each of the three countries received. The most significant changes are taking place in Uzbekistan. Until recently, the country was a major gas producer and exporter, but in 2023 it became a net importer. Since then, Tashkent has increased purchases from Russia and Turkmenistan. In 2025, Gazprom supplied Uzbekistan with 6.48 billion cubic meters of gas, 15% more than a year earlier. Russian gas reaches the country through Kazakhstan via the Central Asia–Center pipeline system. Built during the Soviet era to carry Central Asian gas northward to Russia, part of the system now operates in reverse. Supplies continue to rise. The International Energy Agency expects Russian gas supplies to Uzbekistan to exceed ten billion cubic meters in 2026. The reason is evident in Uzbekistan’s own production figures. The country produced 18.3 billion cubic meters of natural gas in the first half of 2026, down 16.4% from a year earlier. Gas imports reached $971.7 million. Russia and Turkmenistan remain the main external suppliers. Tashkent is trying to reverse the decline. Uzbekneftegaz has ordered new wells to be brought online and 16 existing wells to be overhauled, measures intended to add a combined 4.36 million cubic meters per day to production. Kazakhstan is in a different position. It produced 68.2 billion cubic meters of gas in 2025, but marketable gas production was only 27.4 billion cubic meters. Kazakhstan has also become the transit link between Russia and Uzbekistan. Part of the increase reported by Gazprom also reflects direct supplies to Kazakhstan, although the company has not provided a breakdown among the three countries. Kyrgyzstan’s gas market is considerably smaller. The country consumes around 500 million cubic meters a year and is more dependent on imports. Bishkek has signed long-term agreements with Gazprom for gas supplies to the planned CHP-2 and Bishkekselmash power plants through 2040. The increase in Central Asian sales comes as the geography of Russian gas exports has changed dramatically. Following Russia’s invasion of Ukraine and the sharp decline in deliveries to Europe, Gazprom has been looking for more customers to the east and south. China remains Russia’s largest gas market outside the former Soviet Union. Russia expects to supply China with around 50 billion cubic meters of gas this year. Power of Siberia is already operating at around its design capacity, while another route from Russia’s Far East is scheduled to begin deliveries in January 2027. Moscow and Beijing are also discussing a major new pipeline from Western Siberia through Mongolia. Central Asia, however, is not becoming an exclusively Russian gas market. Turkmenistan remains a major supplier to Uzbekistan, while Uzbekistan in particular is rapidly adding solar and wind generation, helping limit gas demand for power generation. But the direction of gas flows has already changed in a literal sense. The Central Asia–Center system was once built to carry...